 BTC
 ETH
 XRP
 SOL
 DOGE
Everyone is talking about what the Fed’s first rate hike in three years means for stocks and mortgages. Almost nobody is talking about the one group it actually helps: savers.
Here is the situation, with verified numbers.
What happened
On September 16, 2026, the FOMC voted 12-0 to raise the federal funds target range by 25 basis points to 3.75%–4.00% — the first increase since July 2023. Chair Kevin Warsh said it plainly: “Today’s action starts to show we’re serious about this, and we will deliver on the price stability objective.” Most of his colleagues expect at least one more hike before the end of the year.
When the Fed raises its benchmark, banks can earn more on reserves — and competitive banks pass some of that on to depositors. That is already happening: even Apple Savings just raised its rate to 3.5%.
The gap is absurd
Per the FDIC (Sep 21, 2026 update), the national average savings rate is 0.37% APY. Per WSJ’s daily rate tracking (Sep 29, 2026), the top high-yield savings accounts pay up to 4.50% APY — GO2bank and St. Mary’s Credit Union both hit that mark.
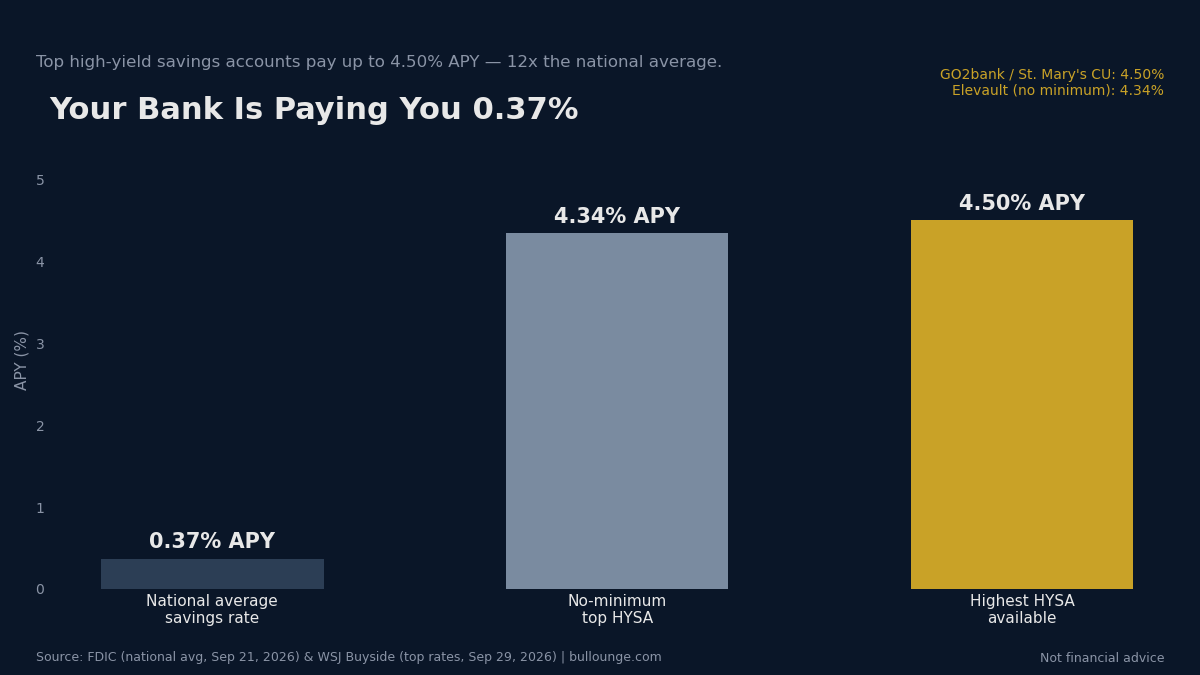
That is a 12x difference. Same dollars, same FDIC insurance (up to $250,000 per depositor), 12x the return.
Put it in dollars
On a $10,000 balance:
| Account | APY | Interest / year |
|---|---|---|
| National average | 0.37% | $37 |
| Typical top HYSA | 4.00% | $400 (+$362/yr) |
| Highest HYSA | 4.50% | $450 |
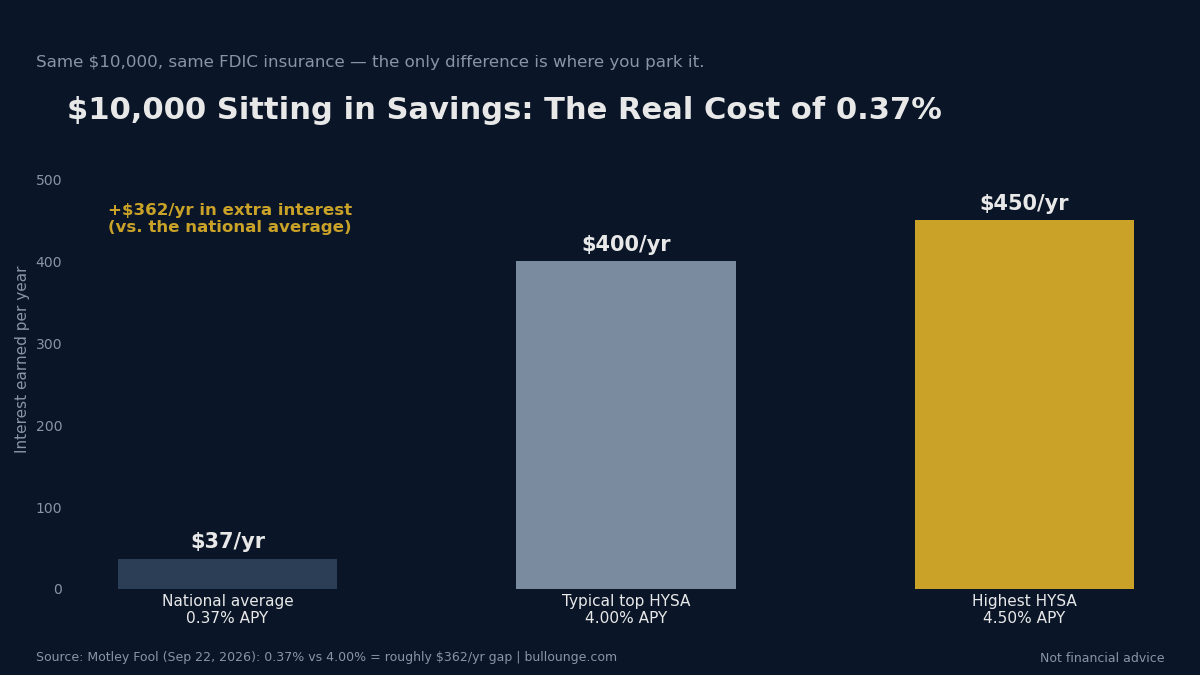
The “+$362/year” figure is Motley Fool’s math (Sep 22, 2026): 0.37% vs 4.00% on $10k. The 4.50% tier is simple multiplication off the verified top rate. No investing skill required — this is a paperwork decision, not a market call.
If you want to lock it in: CDs
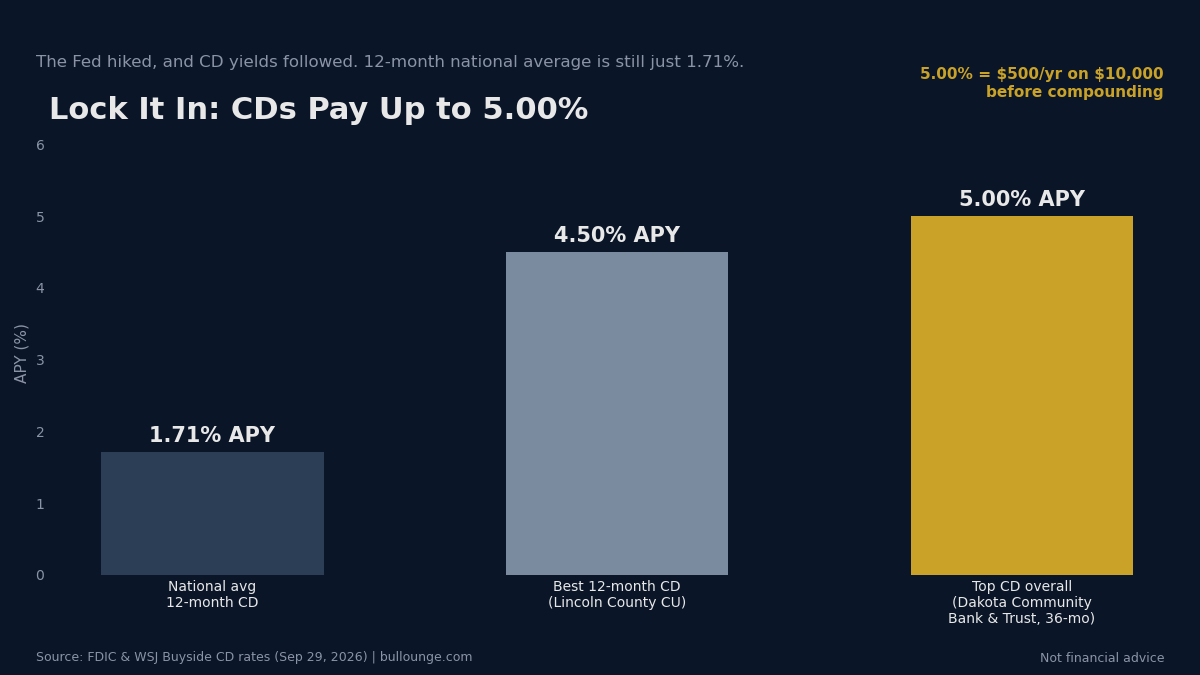
CD yields moved with the hike too. The FDIC national average for a 12-month CD is 1.71% — but the best 12-month CD pays 4.50% (Lincoln County Credit Union), and the top CD overall pays 5.00% APY (Dakota Community Bank & Trust, 36-month, $500 minimum). Five percent on $10k is $500/year before compounding.
Caveat: read the fine print. The 4.50% headline rates have conditions — GO2bank’s applies to balances up to $5,000, St. Mary’s up to $50,000. If you want zero hoops, Elevault pays 4.34% with no minimum and no requirements. Rates are variable and can change; a CD locks yours for the term.
This may not be over
The next FOMC meeting is October 27–28. Prediction markets (Kalshi) and Fed funds futures currently price roughly a 70% chance of another quarter-point hike — meaning savings yields could climb further. If your cash is sitting at 0.37% while the Fed is still hiking, you are subsidizing your bank’s profit margin.
What to actually do this week
- Log in and check your savings APY. If it starts with 0, it is costing you hundreds a year.
- Open a high-yield account at an FDIC-insured bank or NCUA-insured credit union. Prioritize: FDIC/NCUA insurance, no monthly fees, and terms you can actually meet (watch balance caps).
- Move your emergency fund / idle cash over. Keep your checking where it is — this is about the savings pile.
- If you won’t need the money for 6–36 months, compare CD terms. Laddering (splitting across terms) keeps some liquidity.
One honest caveat: inflation is running about 3.4% (August CPI), so even 4.50% is only modestly positive in real terms. This is not a wealth-building strategy — it is a “stop losing money to inertia” strategy. And savings interest is taxable income, so your after-tax yield is lower. Still beats $37.
New from Bull Lounge: Rate Watch, a weekly series tracking where America’s best savings yields are actually moving — which banks raised, which cut, and where the 5%+ CDs are hiding. Episode 2: “3 CDs to lock in now.”
Not financial advice — just verified numbers. Do your own due diligence on any account’s terms before moving money.
Sources
- Federal Reserve Sep 16 decision (3.75%–4.00%, 12-0, Chair Warsh): USA Today, Sep 16, 2026; Motley Fool, Sep 24, 2026
- “Serious about price stability” quote: WSJ Buyside savings rates, Sep 2026
- Most officials expect another hike in 2026: Summa Money, Sep 2026 (16 of 18); USA Today, Sep 16, 2026
- National average savings 0.37% (FDIC, Sep 21, 2026): WSJ Buyside, Sep 26, 2026; Motley Fool, Sep 2026
- Top HYSA 4.50% (GO2bank, St. Mary’s CU); Elevault 4.34% no-minimum: WSJ Buyside, Sep 29, 2026
- $362/yr gap (4.00% vs 0.37% on $10k): Motley Fool, Sep 22, 2026
- CD rates (top 5.00%, best 12-mo 4.50%, avg 1.71%): WSJ Buyside CD rates, Sep 29, 2026
- ~70% October hike odds: DeFi Rate (Kalshi 71%, Sep 29, 2026); Seeking Alpha (Fed funds futures 68%, Sep 29, 2026)
- FDIC insurance $250,000: Motley Fool, Sep 2026
- Apple Savings 3.5%: Crowdfund Insider, Sep 2026
- Headline CPI ~3.4% (August): TradingView/Benzinga, Sep 2026
