 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
October 14, 2026 at 8:47 pm #2380
Stock Picks · Meta Platforms (NASDAQ: META) · Data as of Oct 14, 2026 (intraday, ~2:50 PM ET) unless noted
TL;DR
- The ad engine is firing on all cylinders. Q2 2026 revenue was $60.80B (+28% YoY), on +14% ad impressions and +12% average price per ad. Family Daily Active People hit 3.60B.
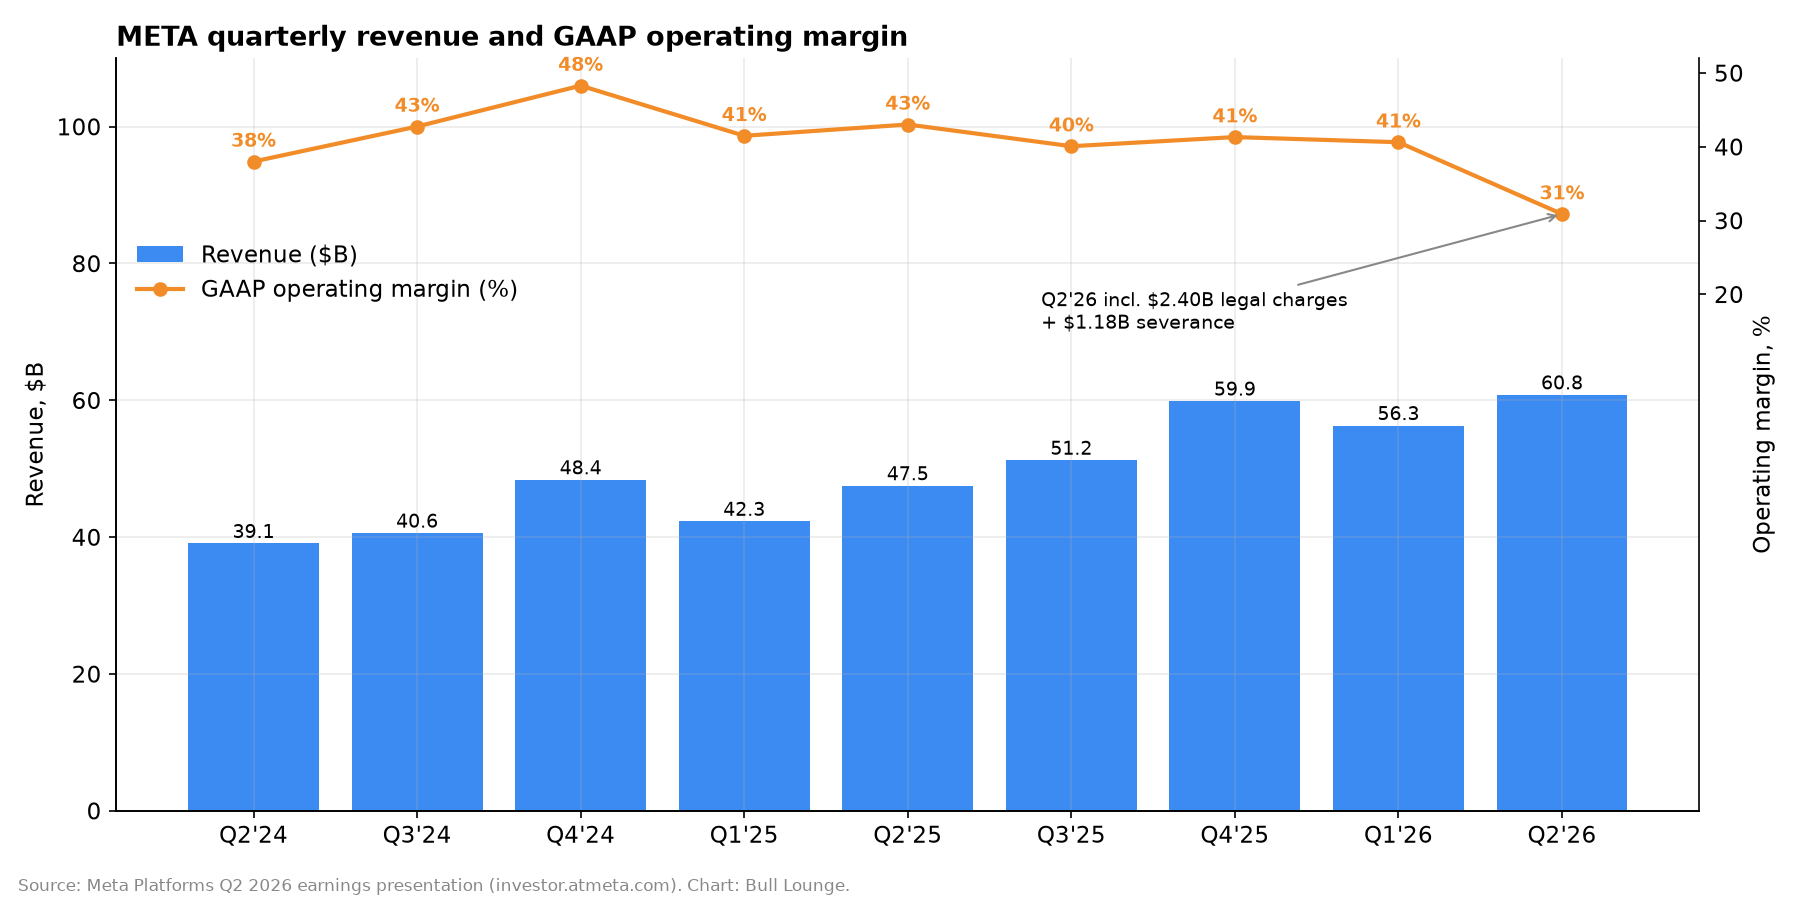
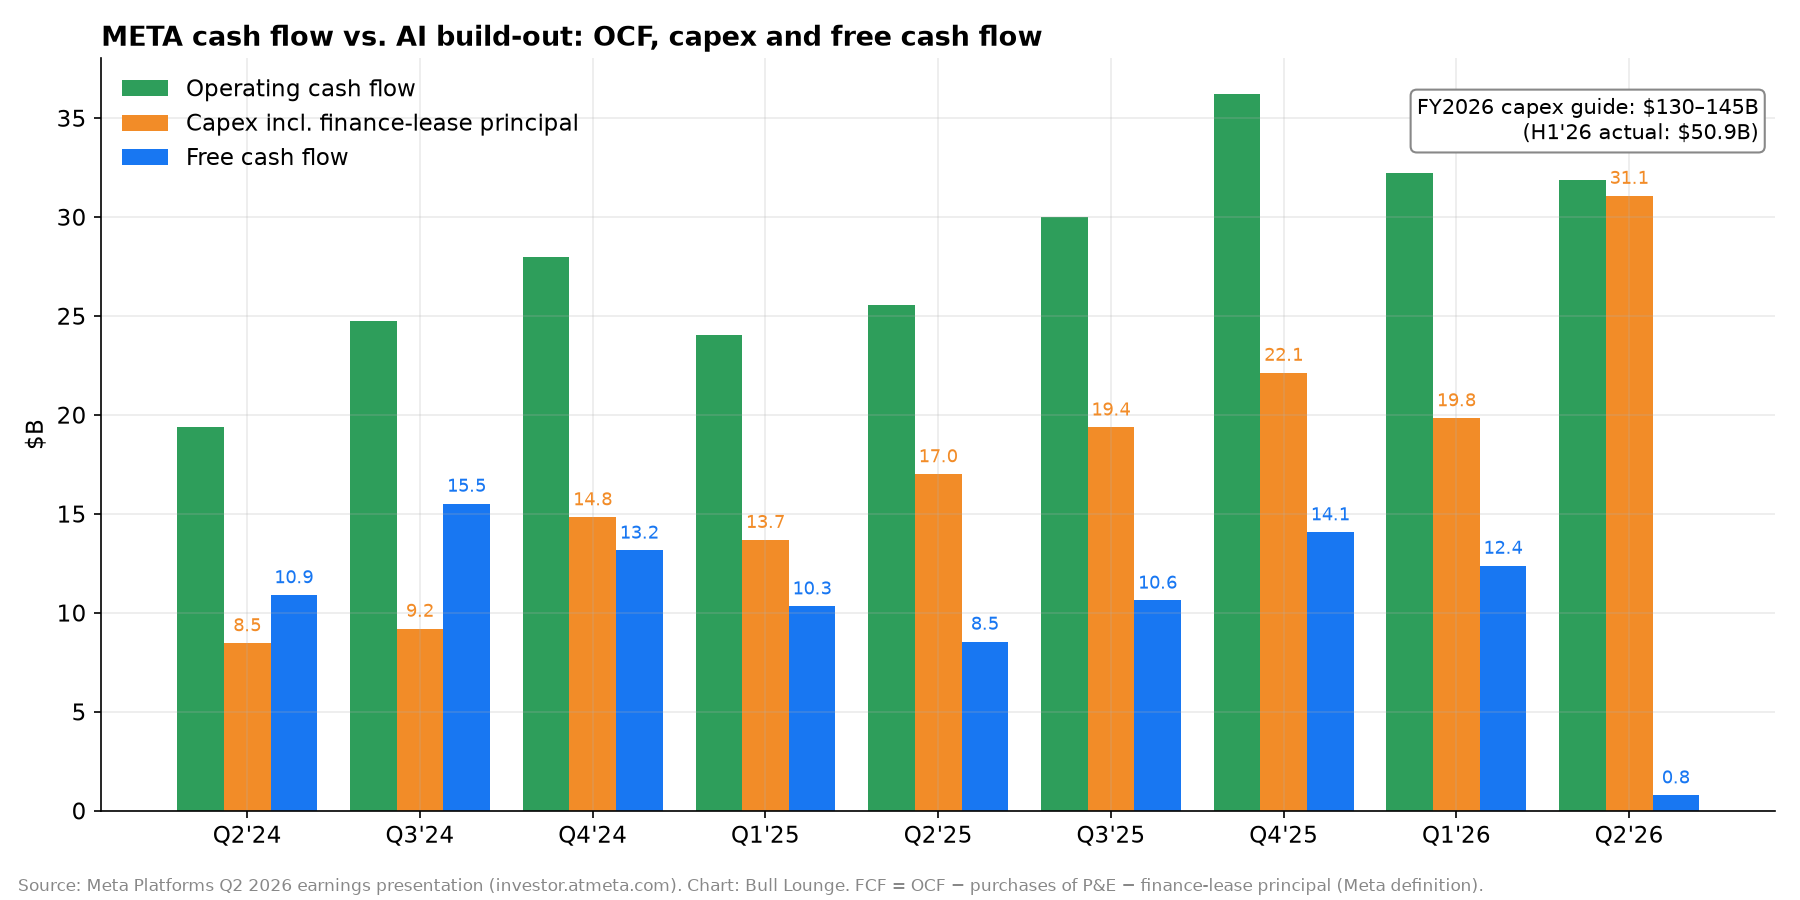
- Below the revenue line, things got messy. GAAP operating margin dropped to 31% (vs. 43%). That includes $2.40B of legal charges and $1.18B of severance. Free cash flow fell to $784M as capex hit $31.08B in a single quarter. The stock dropped ~8% the next day.
- The tape has fully reversed. Since that Jul 30 close (~$539), META has rallied ~37% on the Muse agent launch, Connect, and the Muse Wonder frontier models (Oct 12). The 50-day SMA crossed above the 200-day on Oct 6 (golden cross). The 52-week high is $779.82.
- Valuation is reasonable, not cheap. ~21x forward P/E and ~18x EV/EBITDA, with a TTM FCF yield of only ~2.0%. In 2026, Meta’s capex is eating most of its operating cash flow.
- Next catalyst: Q3 earnings on Wed, Oct 21 (after close). Guidance is $61–64B revenue. Meta has already said it will book a ~$10B legal accrual in Q3 tied to its state-AG youth settlement, and that charge is not in the $165–169B expense guide. The real swing factor is the first look at 2027 opex/capex.
- Our stance: constructive long-term, cautious into the print. The core business justifies a premium. But the trade from here depends on whether management frames 2027 spending in a way the market can underwrite. Base-case 12-month value sits roughly at the current price. Upside needs evidence of AI monetization beyond ads.
1. Business Overview: Two Segments, One Story
Meta reports two segments:
Segment What’s in it Q2 2026 revenue Q2 2026 operating income TTM revenue* TTM operating income* Family of Apps (FoA) Facebook, Instagram, Messenger, WhatsApp, Threads; advertising + “other” (WhatsApp paid messaging, subscriptions) $60.37B $23.39B (38.8% margin) $225.99B $106.03B (46.9% margin) Reality Labs (RL) VR/AR hardware, software & content (Quest headsets, Ray-Ban Meta & other AI glasses) $0.43B –$4.62B $2.26B –$19.10B Total $60.80B $18.78B (31%) $228.25B $86.93B (38.1%) TTM = Q3’25–Q2’26, summed from Meta’s quarterly segment disclosures.
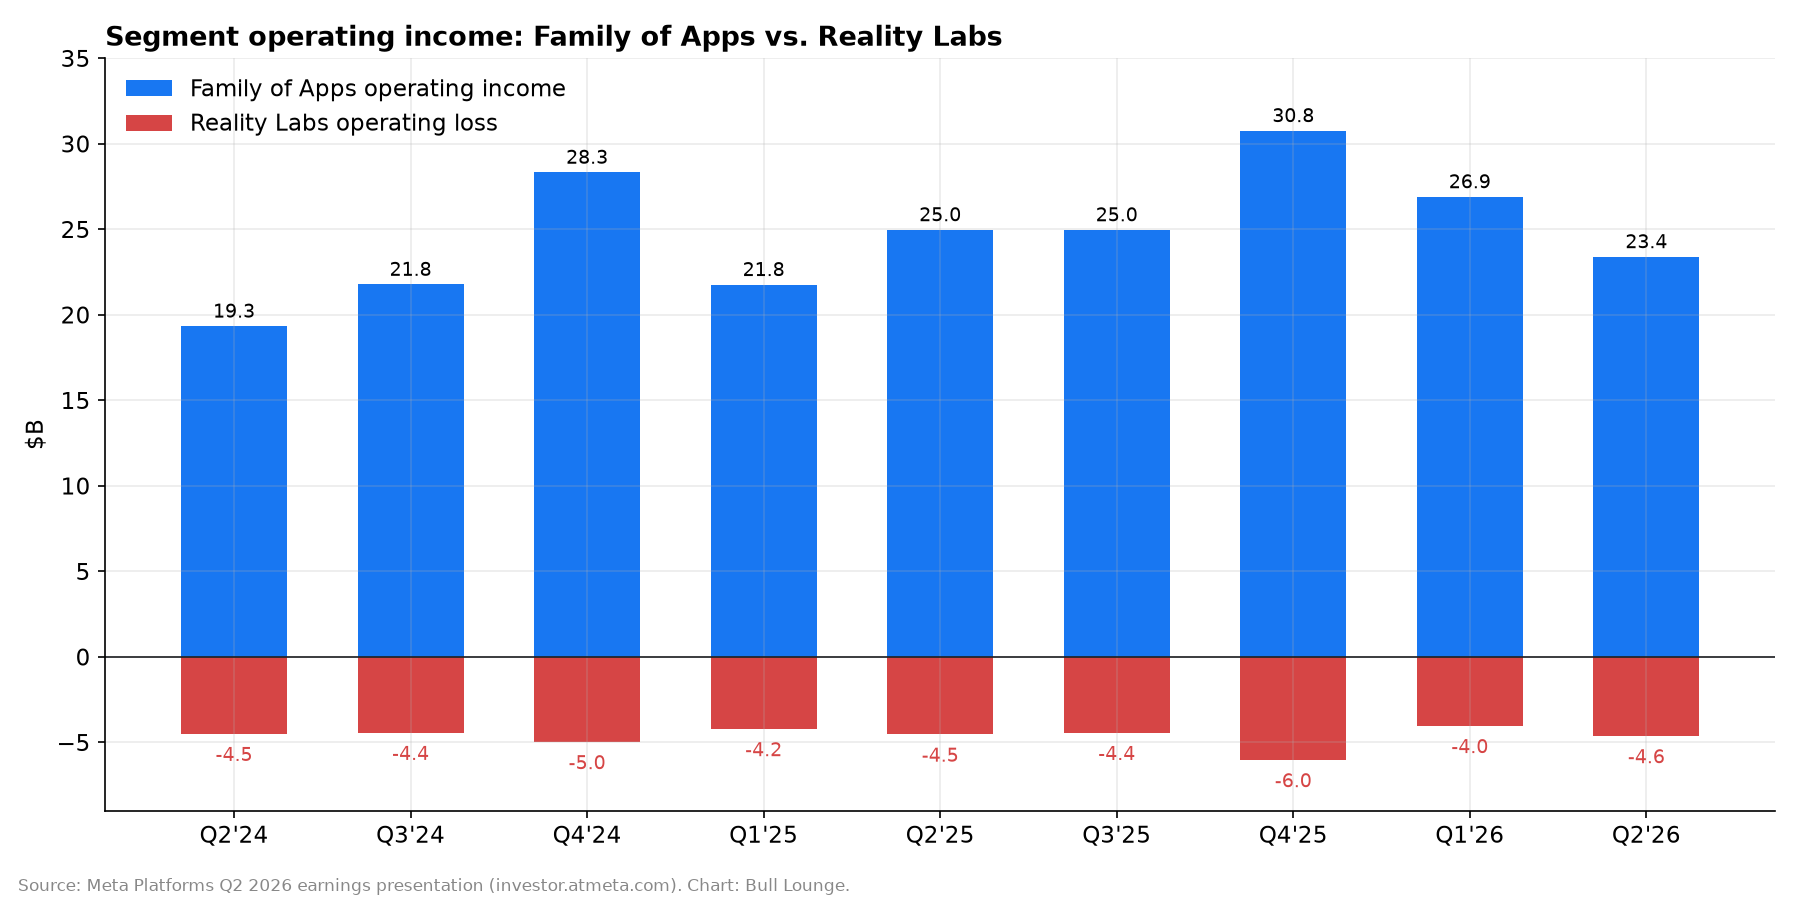
Family of Apps is the cash machine. It’s one of the most profitable businesses on the planet, and the AI investment is already showing up in its numbers:
- Ad performance: On the Q2 call, management said its GEM ads-ranking model, together with new user-understanding models, drove an 8.3% increase in ad clicks and a 15.7% uplift in conversions on Facebook. The new “Meta Generative Recommender” uses LLMs to reason about ad content and user preferences together.
- Advantage+ (Meta’s AI-automated campaign suite) has passed a $75B annual revenue run-rate.
- Engagement: Instagram time spent grew double digits YoY. Facebook video time grew 9% globally. Threads passed 500M monthly actives.
- New revenue lines: FoA “other revenue” topped $1B in a quarter for the first time (+73% YoY), driven mainly by WhatsApp paid messaging and subscriptions. Management is also building toward subscriptions (Meta One), a model API (Muse Spark on OpenRouter, Muse Wonder on the Meta Model API), business agents on WhatsApp, and potentially selling compute directly.
Reality Labs loses roughly $4–6B per quarter, about $19.1B over the last twelve months on just $2.26B of revenue. AI glasses are the bright spot: RL revenue rose 16% YoY in Q2 “due to strong growth in AI glasses revenue,” partly offset by lower Quest sales. At Connect (Sep 23), Meta said its Muse personal agent is coming to AI glasses and launched Ray-Ban Meta Audio (from $349). Strategically, RL is now Meta’s planned hardware endpoint for “personal superintelligence.” Financially, it’s still a drag.
Segment operating income: Family of Apps vs. Reality Labs
2. Recent Quarterly Results
2a. Headline P&L (in $ millions, except per share)
Metric Q2’25 Q3’25 Q4’25 Q1’26 Q2’26 Revenue 47,516 51,242 59,893 56,311 60,801 Revenue growth YoY 21.6% 26.2% 23.8% 33.1% 28.0% Income from operations 20,441 20,535 24,745 22,872 18,775 Operating margin 43% 40% 41% 41% 31% Net income 18,337 2,709 ¹ 22,768 26,773 ² 15,848 Diluted EPS (GAAP) $7.14 $1.05 ¹ $8.88 $10.44 ² $6.18 Diluted EPS ex one-time tax items $7.14 $7.25 ¹ $8.88 $7.31 ² $6.18 ³ Effective tax rate 11% 87% ¹ 10% (23%) ² 16% ¹ Q3’25 includes a one-time, non-cash $15.93B income-tax charge related to the One Big Beautiful Bill Act (Meta’s figure ex-charge: EPS $7.25).
² Q1’26 includes an $8.03B tax benefit from CAMT transitional relief (Treasury Notice 2026-7) (Meta’s figure ex-benefit: EPS $7.31).
³ Q2’26 is not adjusted for the $2.40B legal charges or $1.18B severance. Meta said operating income ex those items would have risen 9% YoY.TTM diluted EPS: $26.55 GAAP, or $29.62 excluding the two one-time tax items (our sum of Meta’s disclosed figures).
META quarterly revenue and GAAP operating margin 2b. Segment results ($ millions)
Segment Q2’25 Q3’25 Q4’25 Q1’26 Q2’26 FoA advertising revenue 46,563 50,082 58,137 55,024 59,363 FoA other revenue 583 690 801 885 1,007 FoA revenue 47,146 50,772 58,938 55,909 60,370 FoA operating income 24,971 24,967 30,766 26,900 23,394 FoA operating margin 53.0% 49.2% 52.2% 48.1% 38.8% RL revenue 370 470 955 402 431 RL operating loss (4,530) (4,432) (6,021) (4,028) (4,619) 2c. Engagement & ad metrics
Metric Q2’25 Q3’25 Q4’25 Q1’26 Q2’26 Family Daily Active People (B) 3.48 3.54 3.58 3.56 ⁴ 3.60 Ad impressions, YoY (worldwide) +11% +14% +18% +19% +14% Avg. price per ad, YoY (worldwide) +9% +10% +6% +12% +12% ⁴ Meta attributed the Q1’26 dip to internet disruptions in Iran and restricted WhatsApp access in Russia.
2d. Cash flow & capex ($ millions)
Metric Q2’25 Q3’25 Q4’25 Q1’26 Q2’26 Operating cash flow 25,561 29,999 36,214 32,226 31,862 Purchases of P&E 16,538 18,829 21,383 18,997 30,116 Finance-lease principal 474 545 754 843 962 Capex (Meta definition) 17,012 19,374 22,137 19,840 31,078 Free cash flow 8,549 10,625 14,077 12,386 784 Capex as % of revenue 35.8% 37.8% 37.0% 35.2% 51.1% - FY2025 capex: $72.2B (sum of quarters). H1 2026 capex: $50.9B.
- Implied H2 2026 capex from the $130–145B guide: ~$79–94B, or roughly $40–47B per quarter. Cash burn on infrastructure is about to step up again.
- Balance sheet (Jun 30, 2026): $90.26B cash & marketable securities vs. $83.66B long-term debt, up from $58.74B at year-end 2025 after $24.9B of net debt issuance in Q2. Meta made no share repurchases in H1 2026 (vs. $22.9B in H1 2025). It’s still paying a dividend (~$1.35B/quarter).
- On funding, CFO Susan Li pointed to “a greater mix of debt” and partnerships such as the BlackRock deal announced the day before the Q2 call.
META cash flow vs. AI build-out: OCF, capex and free cash flow 2e. Guidance (as given Jul 29, 2026, plus the Aug 26 update)
Item Guidance Comment Q3’26 revenue $61–64B ~1pt FX headwind. Implies +19% to +25% YoY vs. Q3’25’s $51.24B FY26 total expenses $165–169B Low end raised to absorb the Q2 legal charges Q3’26 legal accrual (Aug 26 update) ~$10B Tied to the multistate AG agreement. Meta says it was not contemplated in the expense range; other guidance unchanged FY26 operating income Above FY25 ($83.28B) Reiterated Jul 29. The Aug 26 release didn’t explicitly re-address this after the $10B accrual. Clarification is worth watching on Oct 21. FY26 capex (incl. finance leases) $130–145B Narrowed from $125–145B. Midpoint is ~1.9x FY25 Tax rate (rest of 2026) 15–17% Up from 13–16% 2027 capex Not provided “Infrastructure planning remains highly dynamic” (S. Li) Street setup for Q3 (MarketBeat consensus): EPS $6.76, revenue $63.30B. Note that Meta’s Q2 EPS of $6.18 missed the $7.19 consensus. When the Q3 numbers land, check whether a given consensus includes the ~$10B accrual before calling a “beat” or “miss.”
3. Valuation vs. Mega-Cap Peers
Snapshot Oct 14, 2026 intraday. Multiples from Yahoo Finance unless noted. FCF yield = TTM free cash flow ÷ market cap.
Metric META GOOGL AMZN MSFT Share price $736.42 $347.34 $253.50 $534.09 Market cap ~$1.88T ~$4.25T ~$2.73T ~$3.97T Trailing P/E (GAAP) 27.7x 17.4x † 20.4x † 30.1x Forward P/E 21.3x 22.7x 24.2x 22.6x EV / EBITDA (TTM) 17.9x 24.4x † 17.3x † 21.0x Latest-quarter revenue growth YoY 28.0% 24.2% 19.6% 17.7% TTM FCF yield ~2.0% ‡ ~1.3% § ~–0.3% ¶ ~1.7% § † For GOOGL and AMZN, trailing EPS sits above forward EPS estimates, and Yahoo’s reported EBITDA for GOOGL’s latest quarter far exceeds its “normalized” EBITDA. That points to large non-operating gains in their TTM results, so treat their trailing P/E and EV/EBITDA as not like-for-like.
‡ META: Meta-defined FCF of $37.87B (Q3’25–Q2’26) ÷ ~$1.88T.
§ GOOGL / MSFT: TTM operating cash flow minus purchases of property & equipment, from Yahoo Finance quarterly cash-flow data (last four reported quarters). Excludes finance leases, so these are approximate and somewhat flattering.
¶ AMZN: company-reported TTM FCF of –$7.6B (Q2 2026 release).How we read it:
– On forward earnings, META is the cheapest of the four (~21x vs. ~23–24x) while growing revenue the fastest. On TTM EPS ex the one-time tax items ($29.62), it trades at ~24.9x.
– On cash, the edge mostly disappears. Every hyperscaler is pouring OCF into AI capex, and META’s ~2% FCF yield is “least bad,” not “attractive.” Q2’26 FCF was just $784M.
– The discount to peers reflects two things the others don’t carry to the same degree: (1) no cloud business to rent out the capex (yet; management is openly exploring selling compute), and (2) a live youth-safety legal overhang.
– Sell-side: Yahoo shows 58 analysts with a mean target of $813 (median $830, range $580–$1,050). Recent moves reported by TheFly/Stocktwits and others: Truist $1,000 (from $763), Wells Fargo $1,000 (from $796), UBS $884, Guggenheim $850. Goldman cut to $762 (from $860), citing higher 2027 opex.
4. Price Action & Technicals
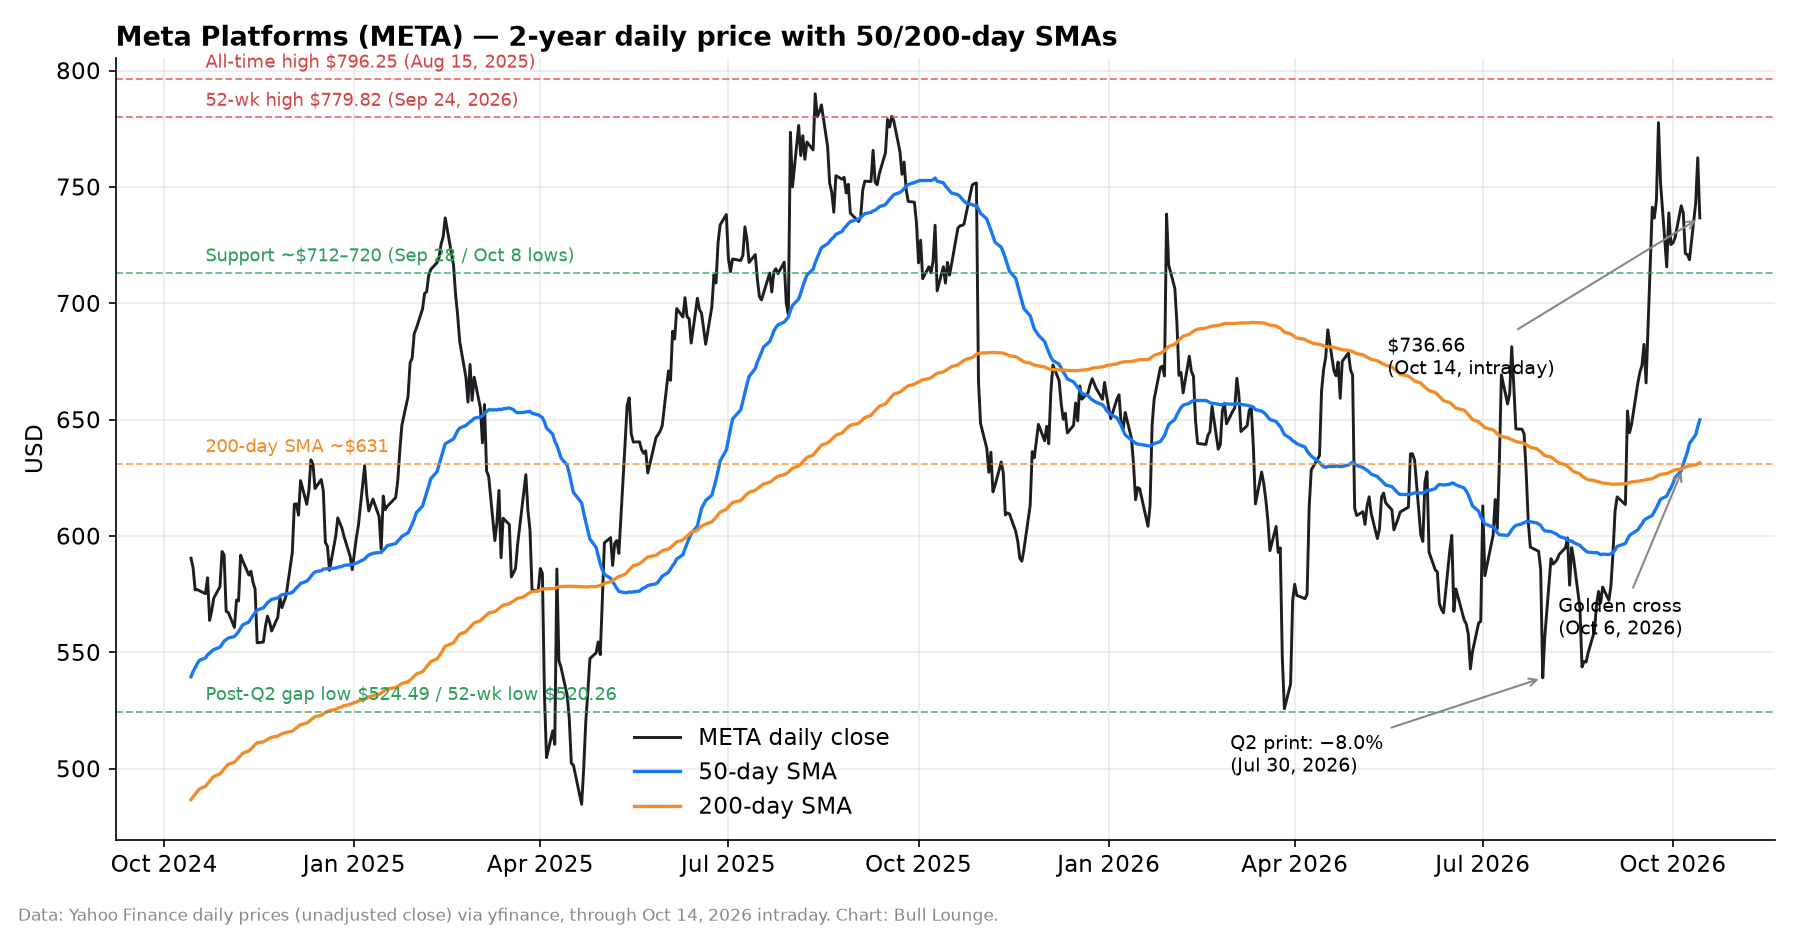
Meta Platforms (META) — 2-year daily price with 50/200-day SMAs Where we are (Yahoo Finance daily data):
Level Value Price vs. level Last (Oct 14, intraday) ~$736.66 — Prior close (Oct 13) $762.50 –3.4% 20-day SMA ~$730.8 +0.8% 50-day SMA ~$649.9 +13.4% 200-day SMA ~$631.4 +16.7% 52-week high (Sep 24, 2026) $779.82 –5.5% All-time high (Aug 15, 2025) $796.25 –7.5% 52-week low (Mar 27, 2026) $520.26 +41.6% 2025 year-end close $660.09 +11.6% YTD RSI(14) ~66 at Oct 13 close, ~58 intraday Cooling from overbought-adjacent The narrative on the chart:
1. Jul 30 earnings gap: –8.0% close-to-close (585.61 → 539.03), with an intraday low of $524.49, right on top of the March 52-week low ($520.26). That double-bottom zone is now the line in the sand for the bear case.
2. August base: closing low of $543.67 (Aug 18). A higher low versus July, followed by a reclaim of $600 in early September.
3. Sep 21 breakout: +11.3% in one session (665.75 → 741.25) after Wells Fargo’s Muse-driven target hike ahead of Connect, then a run to the $779.82 52-week high on Sep 24.
4. Golden cross: the 50-day SMA crossed back above the 200-day on Oct 6, 2026. It’s a lagging signal, but it confirms the trend change.
5. Muse Wonder pop & fade: +3.4% on Oct 12 and +2.6% on Oct 13 (high $771.27), then about –3.4% intraday today. The stock was rejected again just below the $770–780 supply zone.Key levels:
Type Level Why it matters Resistance R3 $790–796 2025 all-time closing high ($790.00, Aug 12) / intraday ATH ($796.25) Resistance R2 $777–780 Sep 24 52-week closing/intraday high. Double-top risk if rejected again Resistance R1 ~$762–771 Oct 13 close/high, today’s rejection zone Support S1 ~$712–720 Sep 28 low ($713.19), Oct 7–9 lows ($711.68–720.15). Base of the 3-week range Support S2 ~$665–690 Sep 18 range, the launch pad of the Sep 21 breakout Support S3 ~$631–650 Rising 50-day (~$650) and 200-day (~$631) SMAs. Trend-defining Support S4 ~$520–540 Mar 2026 low / Jul 30 post-earnings low / Aug base Technical take: The trend is up (price > 20 > 50 > 200, golden cross in place). But META is pinned in a ~$712–780 range going into a binary event. A weekly close above $780 opens a test of the ATH. A loss of $712 after earnings would put the $650–665 zone and the moving averages in play. Remember the last print moved the stock –8% in a day, so size positions with that in mind.
5. Catalysts
- Q3 earnings (Oct 21, after close; call 1:30 PM PT / 4:30 PM ET). Things to watch:
– Revenue vs. the $61–64B guide and $63.3B consensus. Impression growth vs. price per ad.
– Q4 revenue guide. Can growth stay above ~20%?
– Any first framing of 2027 opex and capex. Wells Fargo has flagged 2027 opex of $210–215B vs. a Street figure of ~$202B. This is the stock’s biggest swing factor.
– Whether the “FY26 operating income above FY25” commitment survives the ~$10B accrual. - Muse monetization. Meta launched Muse (its personal agent) in September with a free tier plus $20 and $100/month paid tiers (per Motley Fool), and the Muse Wonder / Muse Wonder Full frontier models on Oct 12. Hard data on subscribers, API revenue, or compute-rental deals would validate the “enterprise” leg management keeps pitching. Third-party usage estimates (e.g., Apptopia via Guggenheim: ~1.3M daily average Muse users over five weeks) are early and small relative to 3.6B DAP.
- WhatsApp monetization: Status ads rolling out globally, business agents, and the Business Agent Platform for enterprises. FoA “other revenue” growth (+73% YoY) is the scoreboard.
- Opex leverage from the May 2026 restructuring: ~8,000 roles (~10% of the workforce, per Fortune/Reuters reporting). Most should roll off headcount by end of Q3.
- AI glasses: Muse on glasses, Ray-Ban Meta Audio, and holiday sell-through via EssilorLuxottica.
- Capital return: buybacks have been paused through H1 2026. Any restart would be a strong signal of confidence in FCF.
6. Risks
- Capex/opex arms race with no ceiling. FY26 capex guidance of $130–145B is roughly 1.9x FY25. Management has declined to guide 2027, and Q2 FCF was close to zero. If 2027 spending lands well above Street numbers without a matching new revenue line, the multiple can compress fast (see Jul 30).
- Legal & regulatory. Meta agreed in August to a multistate settlement with ~$18B in payments over 10 years, per Meta (~$12.7B fixed, ~$5.3B contingent on YouTube/TikTok). The agreement is subject to court approval. Meta also flagged “a number of youth-related trials” that “may ultimately result in a material loss.” EU DMA/privacy regimes remain a recurring risk to ad targeting.
- Teen-usage restrictions. The settlement adds a default 2-hour daily limit, a midnight–6 AM block, and school-hours notification muting for under-18s in participating US jurisdictions, with stricter limits if peers sign on. The revenue impact isn’t disclosed and is likely modest near term, but it’s a structural change to engagement.
- AI execution & competition. Meta’s frontier claims for Muse Wonder are company-reported, and a full safety report is still “coming soon.” OpenAI, Google, Anthropic and others compete for the same users, developers, and talent. Talent costs are a major opex driver.
- Reality Labs. ~$19B of TTM operating losses with no stated breakeven timeline.
- Balance-sheet drift. Long-term debt rose ~$25B in one quarter and buybacks have stopped. Meta is still roughly net-cash on its securities vs. long-term debt (excluding leases), but the trend is toward leverage.
- Macro/ad-cycle sensitivity. About 98% of revenue is advertising. An ad recession would hit while fixed infrastructure costs (depreciation) are surging. Q2 D&A was $6.36B vs. $4.34B a year ago.
- Event/technical risk. The stock is about 37% off its August lows going into the print, with sentiment heavily tied to a still-unproven product (Muse).
7. Scenarios (12-month view)
These are illustrative scenarios built on our own assumptions. They are not forecasts. For reference, MarketBeat shows a consensus FY2027 EPS of ~$34.39, and Wells Fargo’s published view is $31–32.
Scenario FY2027 EPS assumption Target multiple Implied value vs. ~$737 Key assumptions Bull $38 26x ~$990 +34% Ad revenue grows mid-20s% on GEM/Generative Recommender gains. Muse subscriptions, API and/or compute rental become a visible new line in 2027. Opex growth contained by the 2026 restructuring. Market re-rates META toward a MSFT-style AI-platform multiple Base $33 23x ~$760 +3% ~20% revenue growth in 2027. Opex close to the Street/Wells range. Capex rises again, but FCF stays positive. No further material legal charges beyond those disclosed. Multiple stays near today’s ~21–23x forward Bear $28 18x ~$505 –31% 2027 opex at or above $215B with capex up sharply. Ad growth slows to low/mid-teens (macro and teen-usage limits). Muse monetization disappoints. More youth-litigation losses. Stock revisits the $520–540 double-bottom zone A simple 25/50/25 probability weighting gives a blended value of ~$754, about +2% from here. In other words, today’s price already discounts a “base case with some optimism.” Further upside needs the bull-case evidence on Oct 21 and beyond.
8. Conclusion
Meta has two investment theses rolled into one ticker:
- Thesis #1, the ad compounder. 3.6B daily users, ~28% revenue growth at $60B/quarter scale, and AI-driven ad-performance gains that are measurable today. That business alone arguably supports today’s ~21x forward multiple.
- Thesis #2, the AI-platform option. Muse, Muse Wonder, business agents, a model API, and possibly selling compute. This is what the recent ~37% rally is paying for. It’s what’s consuming ~$130–145B of capex this year and an unknown (probably larger) amount in 2027.
At ~$737, the stock sits in the upper half of a $712–780 range with a fresh golden cross. On our math, it’s priced close to base-case fair value. We like META as a core long-term holding on pullbacks toward the $650–690 zone (50-day SMA / breakout base). We’d be more cautious about chasing into the Oct 21 print, where the 2027 spending conversation could easily overshadow another strong ad quarter. A clean break above $780 after earnings, backed by 2027 framing that the market accepts, would flip us to outright bullish with the ATH (~$796) and then the $850–1,000 sell-side targets in view.
What would change our mind:
– To the upside: hard Muse/API/compute revenue numbers, a buyback restart, or a 2027 capex framing with explicit return targets.
– To the downside: 2027 opex guidance above ~$215B with no new revenue line, or a weekly close below ~$650.What’s your read? Are you buying the Muse story here, or waiting for the 2027 capex number? Drop your levels below. 👇
Disclaimer — Not financial advice. This post is for informational and educational purposes only and reflects the author’s opinions as of the date written. It is not a recommendation to buy, sell, or hold any security. All figures are from the public sources cited below and may contain errors or change without notice. Scenario values are hypothetical illustrations, not price targets or forecasts. Equities, especially around earnings, can move sharply. Do your own research and/or consult a licensed financial adviser before making investment decisions. The author and Bull Lounge may hold positions in the securities mentioned.
Sources (accessed Oct 14, 2026)
- Meta Platforms — Meta Reports Second Quarter 2026 Results (press release, Jul 29, 2026): https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Second-Quarter-2026-Results/ · PDF: https://s21.q4cdn.com/399680738/files/doc_news/Meta-Reports-Second-Quarter-2026-Results-2026.pdf
- Meta Platforms — Earnings Presentation Q2 2026 (9-quarter segment, FCF, DAP, ad-metric history): https://s21.q4cdn.com/399680738/files/doc_financials/2026/q2/Earnings-Presentation-Q2-2026.pdf
- Meta Platforms — Q2 2026 Earnings Call Transcript (Jul 29, 2026): https://s21.q4cdn.com/399680738/files/doc_financials/2026/q2/META-Q2-2026-Earnings-Call-Transcript.pdf
- Meta Platforms — Form 10-Q for the quarter ended Jun 30, 2026 (SEC): https://www.sec.gov/Archives/edgar/data/1326801/000162828026050705/meta-20260630.htm
- Meta Platforms — Meta to Announce Third Quarter 2026 Results (Oct 12, 2026): https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-to-Announce-Third-Quarter-2026-Results/default.aspx
- Meta Platforms — Meta’s Agreement With Bipartisan Attorneys General… (Aug 26, 2026; ~$18B payment, ~$10B Q3 accrual): https://www.prnewswire.com/news-releases/metas-agreement-with-bipartisan-attorneys-general-calling-on-tiktok-and-youtube-to-join-us-in-supporting-teens-302860652.html
- California Attorney General — $17 Billion Settlement with Meta (Aug 26, 2026; settlement subject to court approval): https://oag.ca.gov/news/press-releases/ATTORNEY-general-bonta-secures-transformative-17-billion-settlement-meta
- Meta AI — Muse Wonder: A Frontier Model for Personal & Professional AI Agents (Oct 12, 2026): https://research.meta.ai/blog/muse-wonder
- Meta — Everything We Announced at Meta Connect 2026: https://www.meta.com/blog/meta-connect-2026-everything-we-announced/
- Amazon — Q2 2026 results (TTM free cash flow –$7.6B): https://www.aboutamazon.com/news/company-news/amazon-earnings-q2-2026-report
- Yahoo Finance via
yfinance— META/GOOGL/AMZN/MSFT quotes, P/E, forward P/E, EV/EBITDA, analyst targets, quarterly cash flows, and META daily OHLC (pulled Oct 14, 2026 intraday): https://finance.yahoo.com/quote/META/ - MarketBeat — META Q3 2026 earnings preview (consensus EPS $6.76, revenue $63.30B; FY26/FY27 EPS consensus): https://www.marketbeat.com/earnings/reports/2026-10-21-facebook-inc-stock/ and https://www.marketbeat.com/instant-alerts/upcoming-meta-platforms-meta-projected-to-announce-quarterly-earnings-on-wednesday-2026-10-14/
- Stocktwits (citing TheFly) — Goldman $762, UBS $884, Guggenheim $850; Apptopia Muse usage: https://stocktwits.com/news-articles/markets/equity/meta-s-ai-push-draws-fresh-street-calls-goldman-flags-higher-costs-ubs-sees-monetization-potential/cZxfYOeRBqR
- Invezz — Wells Fargo $1,000 target; 2027 opex $210–215B and EPS $31–32 view (Oct 6, 2026): https://invezz.com/news/2026/10/06/why-this-analyst-expects-meta-stock-to-hit-1000/
- Pomegra — Truist target raised to $1,000 from $763 (Oct 13, 2026): https://pomegra.io/news/nasdaq-meta-stock-rises-again-on-muse-wonder-ai-launch
- The Motley Fool — Why Meta Platforms Stock Skyrocketed Today (Sep 21, 2026; Wells Fargo $796, Muse pricing): https://www.fool.com/investing/2026/09/21/why-meta-platforms-stock-skyrocketed-today/
- Fortune — Meta cuts ~10% of workforce (May 21, 2026): https://fortune.com/2026/05/21/meta-10-percent-workforce-layoffs-ai-tech-success-is-not-a-given-8-thousand-employees-mark-zuckerberg/
Charts: Bull Lounge, built from sources 2 and 11. Technical levels and moving averages are calculated from Yahoo Finance daily closes. Derived figures (TTM sums, margins, capex %, implied H2 capex, FCF yields, scenario values) are our own calculations from the cited data.
Attachments:
Log in to vote -
AuthorPosts
