 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
November 10, 2026 at 7:08 am #3428
Wall Street roared back on Monday. The S&P 500 posted its best day since April as buyers swept back into the chip stocks they had dumped last week.
One giant was left behind: Nvidia fell again on its deepening CEO crisis. Today, October CPI lands at 8:30 a.m. ET — the print that decides December.
Index Snapshot — Monday, November 9 Close
Index Close Change S&P 500 7,549.94 +173.08 (+2.35%) Dow Jones Industrial Average 52,389.75 +1,104.02 (+2.15%) Nasdaq Composite 25,253.14 +673.71 (+2.74%) Nasdaq-100 27,907.63 +3.40% Russell 2000 2,840.81 +3.15% The Philadelphia Semiconductor Index surged 6.85%. SOX is back above 10,000.
Market Heatmap
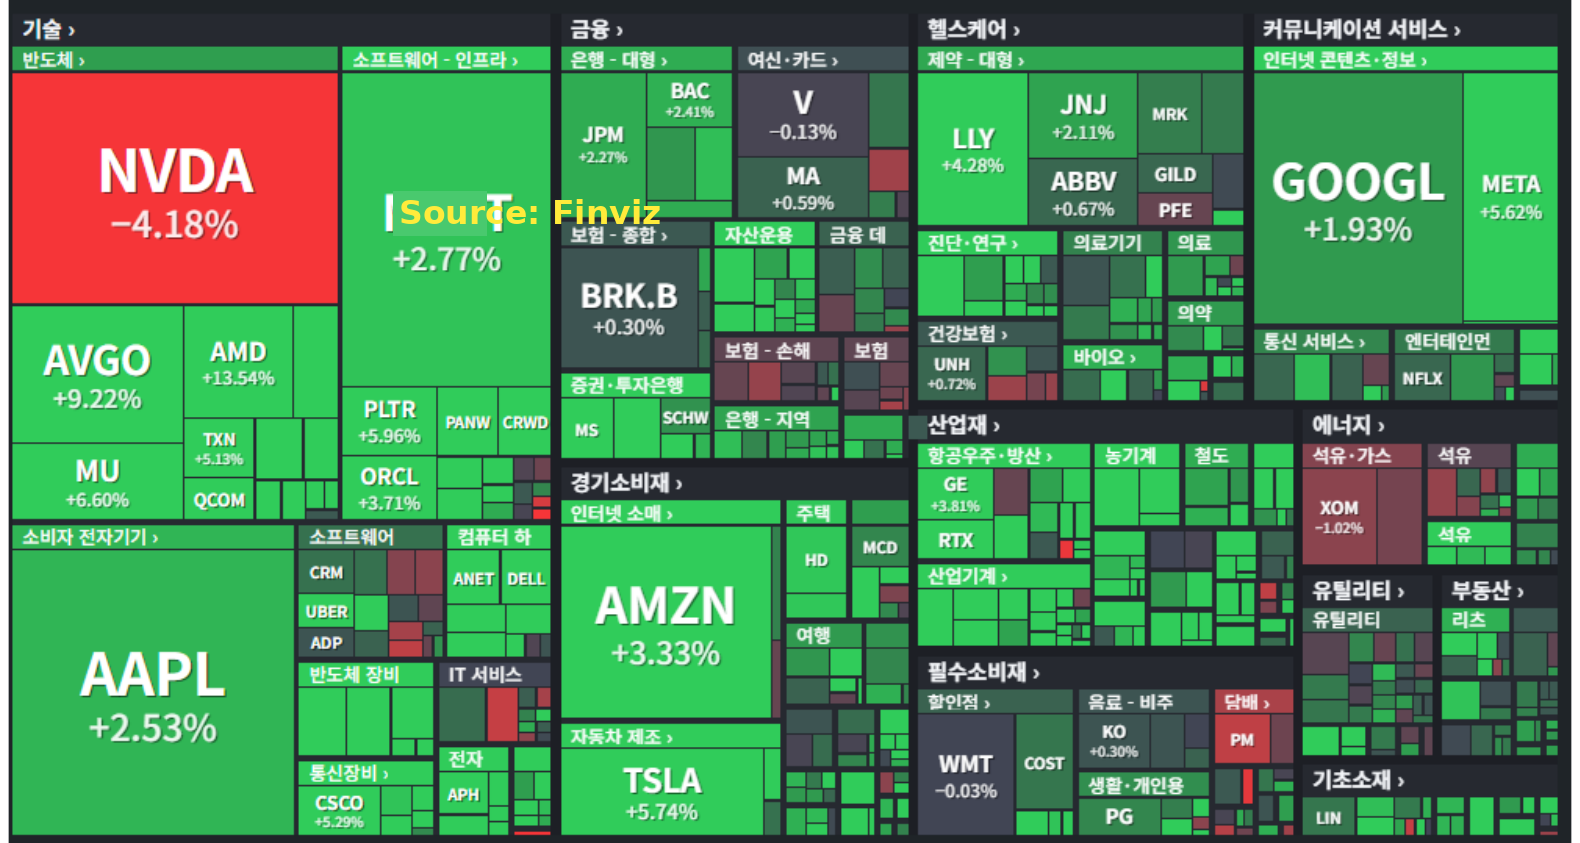
A sea of green with one big red tile. AMD jumped 13.54% and Broadcom 9.22%, while Nvidia dropped 4.18% on more than three times its normal volume.
Sector Performance
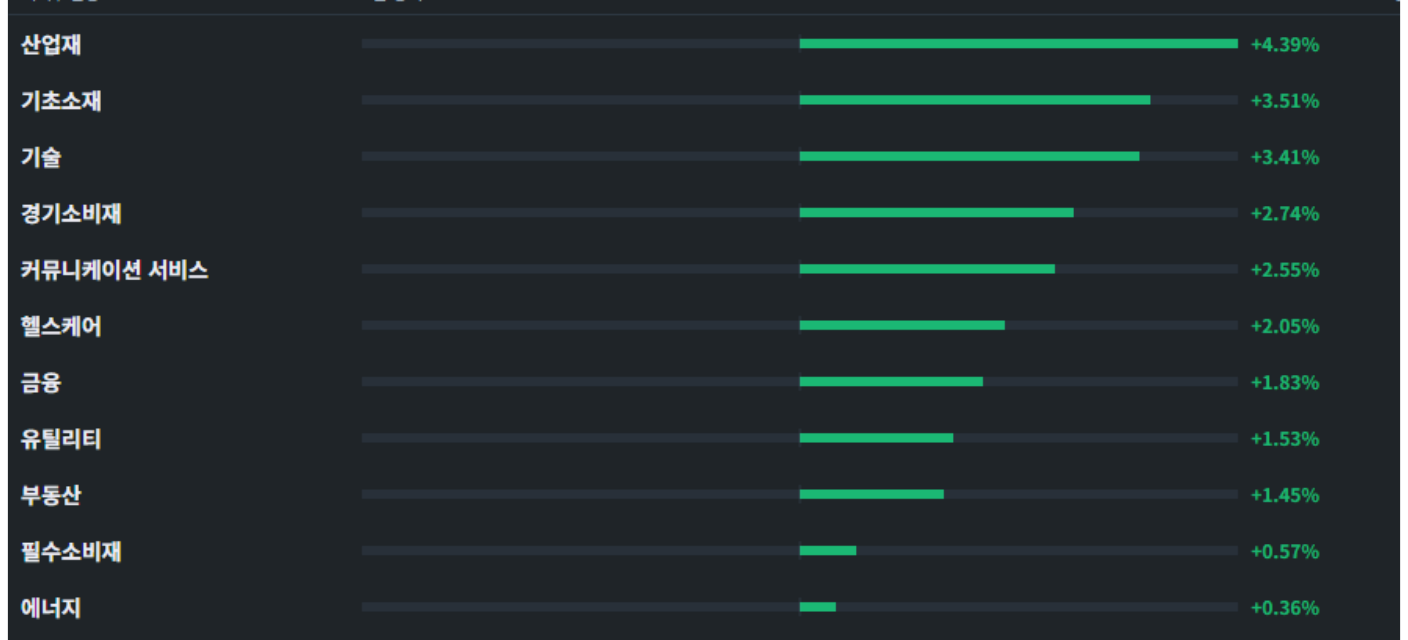
- Industrials: +4.39%
- Basic Materials: +3.51%
- Technology: +3.41%
- Consumer Cyclical: +2.74%
- Communication Services: +2.55%
- Healthcare: +2.05%
- Financials: +1.83%
- Utilities: +1.53%
- Real Estate: +1.45%
- Consumer Defensive: +0.57%
- Energy: +0.36%
Last week’s losers led the rebound — industrials and materials on top. Energy lagged as crude kept sliding.
Yields, Dollar & Commodities
- 2-year Treasury yield: 4.566%
- 10-year Treasury yield: 4.884%
- Dollar index (DXY): 101.681, down from 102.279
- Gold: $4,149.5, up from $4,079.5
- WTI crude: $86.38, down from $90.34 — Brent fell nearly 6% on Iran war-end hopes
- Natural gas: $3.205
- U.S. gasoline: national average $3.98 a gallon — below $4 for the first time since mid-July
Falling oil is doing the Fed’s work for it. Pump prices are still about 19% above seasonal norms, and diesel remains above $6.
Economic Data
- Wholesale inventories (September): +0.7% vs. +0.6% expected
- NY Fed 1-year inflation expectations (October): 3.91% vs. 3.79% expected
- 3-year Treasury auction: 4.627% vs. 4.622% when-issued — a small tail
- Fed speakers Monday: Bowman, Goolsbee and Barkin
- Today: October CPI at 8:30 a.m. ET — the last inflation reading before the December 8–9 FOMC
Households’ inflation expectations ticked up, not down. That makes today’s CPI even harder for the Fed to look past.
Market Sentiment
- CNN Fear & Greed Index: 33 (Fear), up from 24 last week
- VIX: 19.92, down sharply from Friday’s 25.64
Volatility broke back below 20 for the first time since the rout began. Sentiment is healing, but it is not yet greedy — there is room for this rally to run if CPI cooperates.
Top Stories
Anthropic’s $69 Billion Filing Went to Banks by Mistake — and It Leaked the Whole Deal
Anthropic’s roadshow starts today, but the details arrived early. A draft prospectus was briefly circulated to banks late Monday and then retracted, according to emails reviewed by Reuters.
The retracted filing showed a sale of 866.7 million Class A shares at $70–80, raising up to $69.3 billion. It also revealed a separate $26 billion private placement at the IPO price to Google, Nvidia, AMD, Broadcom, Micron, Microsoft and TSMC.
Anthropic said only that the pricing information contained an error and would be corrected. Valuation talk has come down to roughly $1.1–1.5 trillion, from $2 trillion at the peak, and the filing showed Q3 revenue of about $17 billion with growth slowing sharply — two facts investors will press on the roadshow.
Nvidia Shareholders Sue Jensen Huang as the Stock Slides Again
The Nvidia crisis moved to the courts. Shareholders filed a class action minutes after Monday’s close, alleging Huang and the company concealed his relationship with former Megaspeed executive Alice Huang and the national-security risks it created.
NVDA fell 4.3% on Monday to $178.67 — its lowest close since April — erasing about $190 billion of market value while the chip index soared. Nvidia had no immediate comment on the suit.
The calendar is unforgiving: the House committees want Nvidia’s response by Wednesday, and earnings land November 17. The stock is now a headline trade, not a fundamentals trade.
Moonshot AI Rented Nvidia’s Best Chips Inside China, Documents Show
Bloomberg reviewed documents showing China’s Moonshot AI contracted in August to lease 32 Supermicro servers carrying Nvidia’s top-end B300 GPUs — inside China, despite U.S. export controls.
The servers were valued at about $64.8 million, priced roughly 350% above U.S. levels — a black-market premium. The purchasing firm borrowed against both the hardware and the service contract; after Bloomberg asked questions, Moonshot’s name disappeared from the contract record in a central-bank database.
Moonshot denied involvement, and both Nvidia and Supermicro said Moonshot is not their customer. Whether an export license existed is unconfirmed.
Fed’s Waller Backs a December Hike — and Floats 50 Basis Points
Fed Governor Christopher Waller said he supports a December rate hike. If today’s core CPI prints near +0.3% for a third straight month, he argued the Fed should consider 50 basis points, not 25.
Markets now price a December hike at roughly 85%. The rates debate is splitting: Goldman Sachs sees the 10-year settling into a 4.75–5.0% range as volatility fades, while T. Rowe Price’s Arif Hussain warns yields will not truly peak until a recession — and that October’s rally was short-covering, not safe-haven demand.
The Machines Are Still Selling: CTA and Futures Positioning
Monday’s rally ran into a mechanical headwind. Goldman Sachs’ desk estimates trend-following CTAs would sell about $31.2 billion of S&P 500 futures in a flat week — and about $23.1 billion even in a strong rally.
Citi’s positioning data agrees: Nasdaq-100 futures saw $11.1 billion of net outflows last week, and S&P 500 futures flipped to a net short. Europe is the exception — EuroStoxx futures took in $3.9 billion, led by bank short-covering.
Translation: rallies must be bought by humans, because the systematic flows are not coming back until the trend turns.
SoftBank Books a $7.1 Billion Loss on Its U.S. Data-Center Bet
SoftBank posted its first quarterly loss in about two years: a net loss of ¥1.12 trillion ($7.1 billion) versus an expected ¥129 billion profit. A $3.7 billion impairment on its Ohio data-center project — equipment and non-refundable prepayments — did the damage.
The Vision Fund lost money too, and marks on Arm, Intel and Coupang fell. SoftBank shares are down more than 50% from their June record, and its credit default swaps trade at multi-year highs — leverage is now the story.
TSMC’s October Sales Jump 60%: AI Demand Is Not Slowing
TSMC’s October revenue rose 60% year over year to NT$586.9 billion (about $17.9 billion) — faster than Q3’s 51% growth. Fourth-quarter sales are expected to rise about 63%.
The company is building or expanding roughly 20 fabs and confirmed its record capex outlook of up to $64 billion this year. It is also weighing a new Texas facility and discussing cooperation with Elon Musk’s ‘Terafab’ chip project.
FDA Orders a Vision-Loss Warning on All GLP-1 Drugs
The FDA is requiring every GLP-1 drug — including Wegovy and Zepbound — to carry a warning for NAION, a rare eye condition that can cause sudden, permanent vision loss. Causality is not proven; cases have been reported across all drugs in the class.
Across 126 trials and 134,000 patients, incidence was 6.4 per 100,000 person-years versus 3.8 for comparators. Citi analysts expect limited commercial impact given the condition’s rarity and the drugs’ proven benefits — but Novo Nordisk and Eli Lilly now share a class-wide headline risk.
Rare-Earth Price Gaps Widen Ahead of the Trump–Xi Summit
China’s export controls are biting harder. Yttrium oxide trades in Europe at 125 times its China price — about $1.15 million a ton — with dysprosium at 20×, terbium at 8× and gallium at 12×.
Chinese yttrium exports are running at about 40% of their 2023–24 average, and shipments to the U.S. are down roughly 70% from pre-2025 levels. Washington wants Beijing’s supply pledges honored when Trump and Xi meet at APEC in Shenzhen next week — but analysts see the gap lasting about two more years.
Crypto Desk
- Bitcoin spot ETFs (Monday): -$201M
- Ethereum spot ETFs (Monday): -$184M
- Bitcoin stayed near two-month lows after Monday’s $1B-plus liquidation flush
- A coalition including Coinbase and Jump filed comments backing CFTC jurisdiction over perpetual stock futures
- Google revised its registration standards for crypto exchange and wallet apps, adding a licensing exception
The equity rally did not spill into crypto. Seven straight days of ETF outflows for Bitcoin funds is a positioning problem, not a news problem.
Single-Stock News
- Nvidia (NVDA) — Class action filed over the Huang disclosures (Top Stories); separately, Bloomberg’s Moonshot documents raise fresh export-control questions around B300 servers in China.
- Novo Nordisk (NVO) / Eli Lilly (LLY) — Both face the FDA’s class-wide GLP-1 vision-loss warning (Top Stories). LLY still rose 4.28% Monday as healthcare rallied.
- Amazon (AMZN) — Won approval to expand drone delivery in the United Kingdom.
- TSMC (TSM) — October revenue +60% year over year (Top Stories); U.S.-listed shares joined the chip rally.
Single-Stock Movers — Monday
Gainers:
- AMD +13.54%
- AVGO +9.22%
- MU +6.60%
- PLTR +5.96%
- TSLA +5.74%
- META +5.62%
- CSCO +5.29%
Losers:
- NVDA -4.18% — the only major chip name in the red
- XOM -1.02%
One stock fell while its entire sector ripped. That is what a governance discount looks like in real time.
Calendar — What to Watch
- Tue Nov 10: October CPI at 8:30 a.m. ET — the week’s main event. Anthropic’s IPO roadshow begins. Earnings: CoreWeave (after close), Rigetti.
- Wed Nov 11: Veterans Day — bond market closed, stock market open. Deadline for Nvidia’s response to the House committees.
- Thu Nov 12: Earnings: Cisco, Applied Materials, Cerebras, Nebius.
- Fri Nov 13: October PPI and existing home sales.
- Ahead: Anthropic pricing expected next week (Nasdaq listing targeted for the week of Nov 16); Nvidia earnings Nov 17; Trump–Xi at APEC in Shenzhen; House closed-door briefing on Nvidia sought for Nov 18.
Sources
Associated Press and CNN (closing figures); Reuters (Anthropic filing, Nvidia lawsuit, futures positioning); Bloomberg (Moonshot documents, SoftBank results); Finviz (heatmap and sector data); BLS release calendar (CPI); company releases (TSMC monthly revenue).
Not financial advice.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — November 9, 2026 [0] | Master | 11-09 | 0 |
| Morning Briefing — November 6, 2026 [0] | Master | 11-06 | 0 |
| Morning Briefing — November 5, 2026 [0] | Master | 11-05 | 0 |
| Morning Briefing — November 2, 2026 [0] | Master | 11-02 | 0 |
| Morning Briefing — October 29, 2026 [0] | Master | 10-29 | 0 |
| Morning Briefing — October 28, 2026 [0] | Master | 10-28 | 0 |
| Morning Briefing — October 27, 2026 [0] | Master | 10-27 | 0 |
| Morning Briefing — October 23, 2026 [0] | Master | 10-23 | 0 |
| Morning Briefing — October 22, 2026 [0] | Master | 10-22 | 0 |
| Morning Briefing: October 21, 2026 [0] | Master | 10-21 | 0 |
| Morning Briefing: October 20, 2026 [0] | Master | 10-20 | 0 |
| Morning Briefing: October 19, 2026 [0] | Master | 10-19 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.