 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
November 6, 2026 at 7:11 am #3290
The post-election rally lasted exactly one day. On Thursday the AI trade unwound violently, and every major index posted its worst session since April 2025.
The Nasdaq Composite fell 5.52% into a correction. Chip stocks suffered one of their worst days on record, and the VIX exploded to 28.18.
Index Snapshot — Thursday, November 5 Close
Index Close Change S&P 500 7,353.73 -334.89 (-4.36%) Dow Jones Industrial Average 51,523.06 -1,833.06 (-3.44%) Nasdaq Composite 24,315.00 -1,421.52 (-5.52%) Nasdaq-100 26,629.81 -6.36% Russell 2000 2,729.89 -4.45% The Nasdaq closed 11.9% below its October 6 record, officially in correction territory. The Russell 2000 crossed the same line, and the Dow gave back all of Wednesday’s 1,569-point gain and more.
Market Heatmap
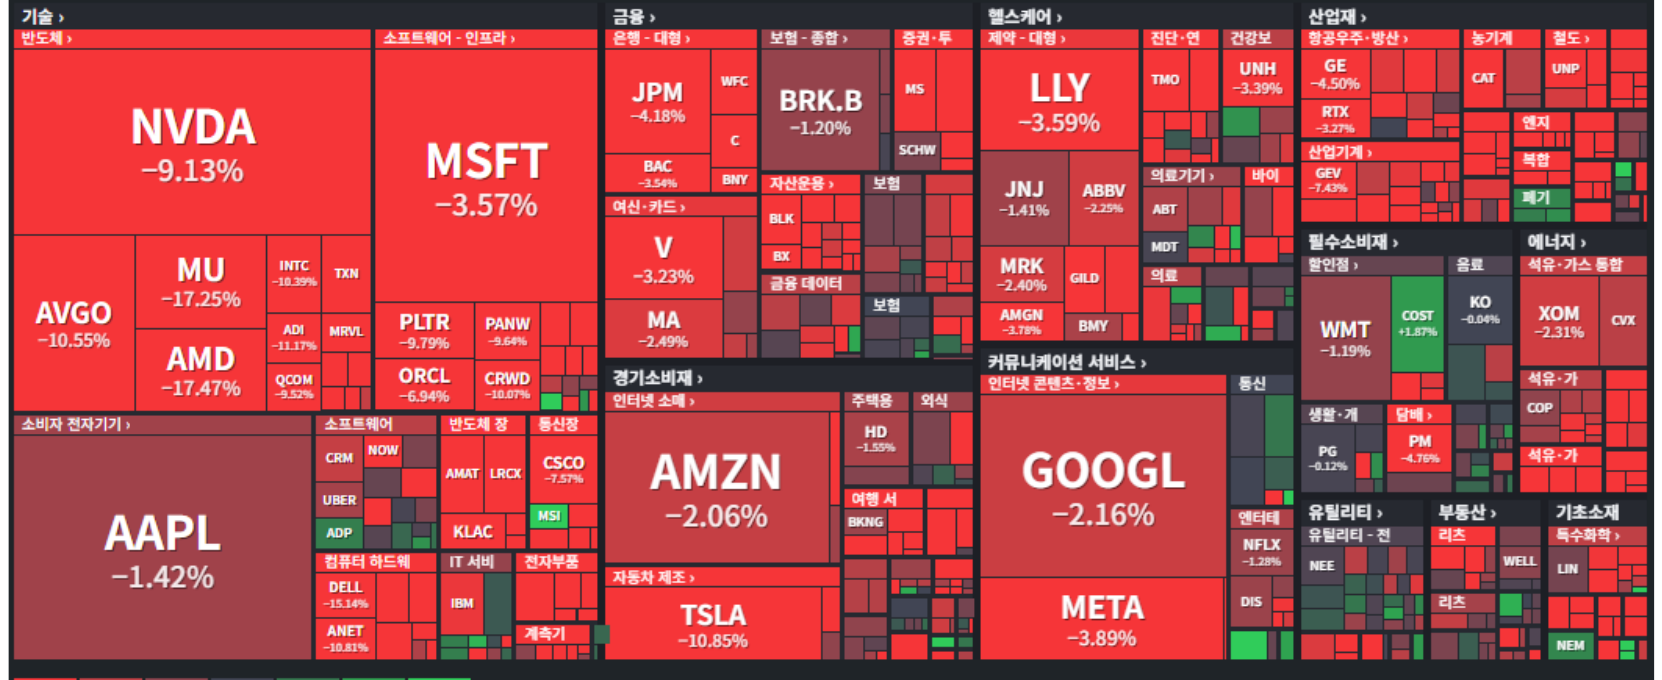
There was nowhere to hide in chips. AMD fell 17.47% and Micron 17.25%, while the Philadelphia Semiconductor Index plunged 12.25% to 9,011.14 — its second-biggest drop on record (Reuters).
Sector Performance
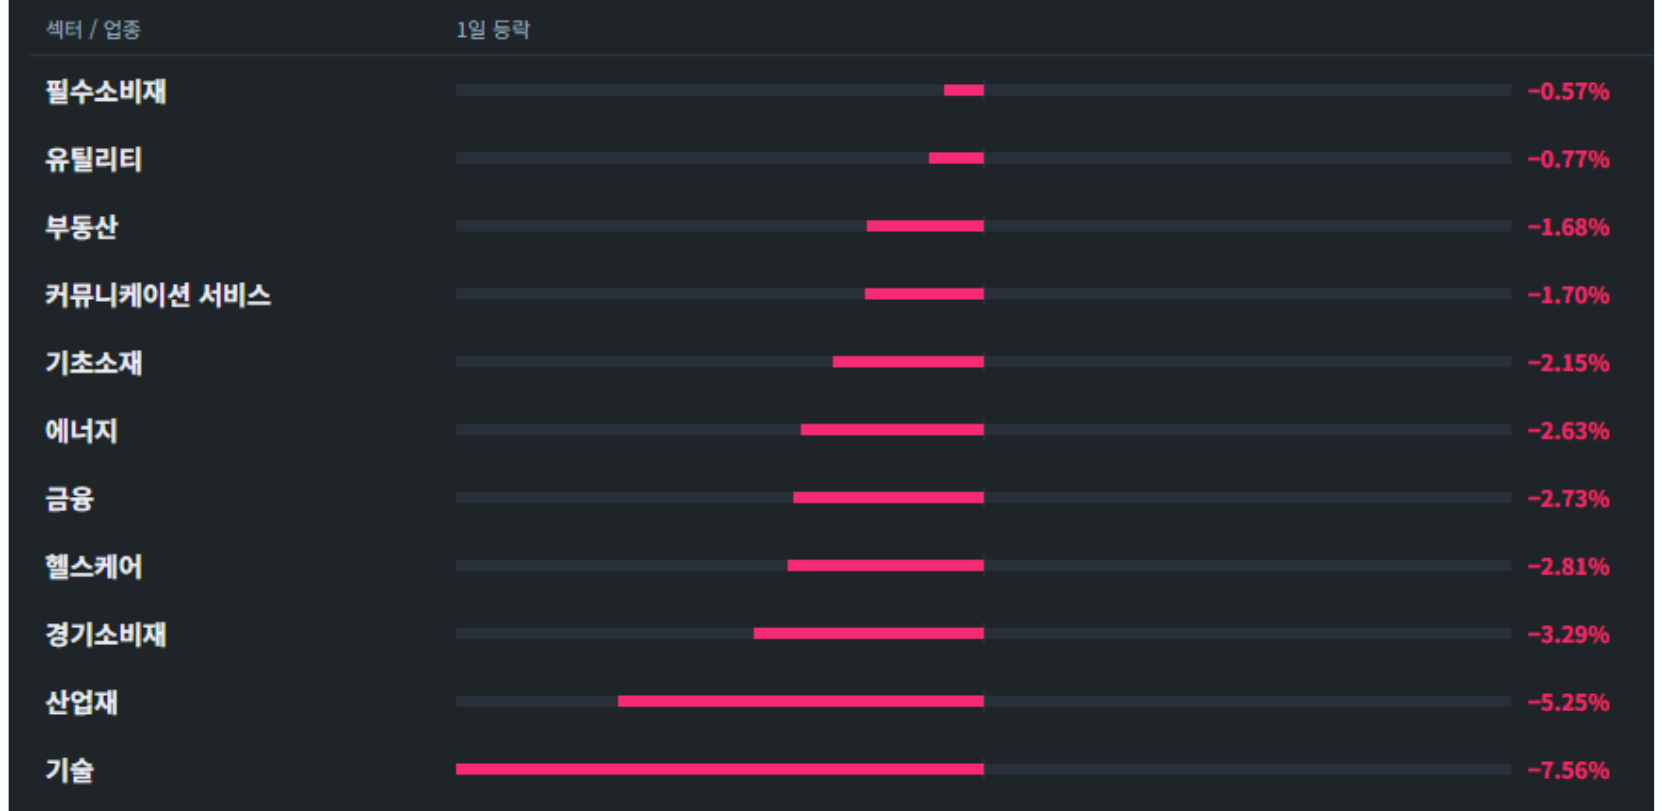
- Consumer Defensive: -0.57%
- Utilities: -0.77%
- Real Estate: -1.68%
- Communication Services: -1.70%
- Basic Materials: -2.15%
- Energy: -2.63%
- Financials: -2.73%
- Healthcare: -2.81%
- Consumer Cyclical: -3.29%
- Industrials: -5.25%
- Technology: -7.56%
All eleven sectors fell. Only staples and utilities held their losses under 1%.
Yields, Dollar & Commodities
- 2-year Treasury yield: 4.471%, down from 4.583%
- 10-year Treasury yield: 4.843%, down from 4.890%
- Dollar index (DXY): 101.600, up slightly from 101.523
- Gold: $4,097.9, up from $4,072.2
- WTI crude: $91.20, up from $88.04 (see the oil story below — the session was choppy)
- Natural gas: $2.952
Bonds caught a safety bid as stocks cratered. Gold added to Wednesday’s rebound.
Economic Data
- Productivity, Q3: +3.6% vs. 2.7% expected (prior 1.4%)
- Unit labor costs, Q3: -0.7% vs. +0.4% expected (prior 1.2%)
- Initial jobless claims: 189,000 vs. 196,000 expected (prior 194,000)
- EIA natural gas storage: +77 Bcf vs. about 79 expected
- Fed speakers Thursday included Cleveland’s Hammack (hawkish) and Richmond’s Barkin
On any normal day, surging productivity with falling labor costs would be celebrated. In a liquidation, nobody cared — today’s jobs report is the next real test.
Market Sentiment
- CNN Fear & Greed Index: 20 (Extreme Fear)
- VIX: 28.18, up 11.6 points in one day from 16.61
That VIX jump is the third-largest ever from a starting level below 20. The two bigger cases — February 2018 and December 2024 — both faded back below 20 within seven sessions.
The difference this time: those were positioning accidents. Thursday’s spike rode on real fundamental worries about chip earnings and data-center regulation.
Top Stories
Wall Street Was Wrong-Footed, and Forced Selling Took Over
Trading desks at JPMorgan, Citadel Securities and UBS had all expected a post-election relief rally. Instead, roughly $2.3 trillion of market value vanished from the Nasdaq-100 in a single session (Bloomberg).
Goldman Sachs said long-only funds stepped back to the sidelines while hedge funds sold the hyperscalers they had bought on Wednesday. Barclays’ model warns volatility-control funds may cut equity exposure by about 30 percentage points and sell some $135 billion of index futures within 24–48 hours.
Leveraged-ETF rebalancing added record selling pressure. Retail investors’ single-stock selling was tracking toward its largest since the pandemic.
Hedge Funds Are Cutting Positions and Staff
The pain is concentrated in stock-picking funds. Morgan Stanley says long/short funds de-grossed in October at the fastest pace in more than a decade, and more than 40% of them were flat or down for the year through October (WSJ).
Tech-heavy TMT funds lost more than 4% on Thursday alone, surrendering year-to-date gains that had reached 24%. Lone Pine went from up over 40% in the first half to -7.5% for the year, and Samlyn, Engineers Gate and Walleye are all cutting staff or strategies.
AI-focused VARA lost 33% in October alone (Bloomberg). The fund told investors it remains solvent with ample margin, but the episode shows how crowded and leveraged the AI trade had become.
Anthropic’s IPO Timing Is Now in Doubt
Anthropic had planned to start its IPO roadshow in the week of November 9 and price the deal the week after. Potential investors are now pushing back on the roughly $1.5 trillion valuation under discussion, calling it the top of the range (Reuters).
Investors want a lower price given continued quarterly losses and huge infrastructure commitments, and they are focused on October revenue figures due in an amended S-1. With a raise that could reach $100 billion, the deal may simply be delayed until markets can absorb it.
The AI Backlash Is Now a Political Force
Tech donors poured more than $600 million into Republican campaigns expecting lighter AI regulation. The midterms turned that bet upside down, as voter anger over data centers became a live election issue (FT).
Democrats plan January hearings on tech executives and federal contracts, and some lawmakers want legislation to slow AI development. In Texas, Governor-elect Gina Hinojosa told CNN the state will pass laws shielding residents from data centers and pause projects until protections exist — a direct headache for Elon Musk’s Texas-based AI buildout.
Cash Is King: Money Funds Took In $140 Billion in a Week
Money market funds absorbed $140.4 billion in the week to November 4, the seventh-largest inflow on record (BofA, citing EPFR). Equity funds still took in $89.2 billion, while crypto funds lost $1.8 billion.
BofA’s Michael Hartnett says a durable risk-on turn needs three things: central bank hikes finished, the 10-year yield below 4.5%, and oil under $80. None of the three is in place today.
China’s YMTC Pushes Homegrown Chip Tools to 70%
China’s top NAND maker, Yangtze Memory, plans to source 60–70% of equipment from domestic suppliers at its fourth Wuhan fab, up from just over 50% at Fab 3 (Reuters). The new plant will make 300-plus-layer NAND for AI data centers.
YMTC’s share of China’s NAND market hit 38.5% in the second quarter, overtaking Samsung. If Fabs 3 through 5 all ramp, its capacity more than doubles — a structural challenge to Samsung and SK hynix, whose China plants are capped by U.S. export rules.
Advanced Packaging Is the Next Chip Bottleneck
TSMC’s CoWoS packaging capacity cannot keep up with AI chip demand, and the scramble for alternatives is on. Nvidia is reportedly funding billions to expand CoWoS capacity at ASE’s SPIL, and AMD has committed over $10 billion to Taiwan including packaging.
Panel-level packaging is the industry’s next bet, with TSMC developing its own CoPoS process. Yole Group expects advanced packaging revenue to pass conventional packaging this year, on roughly $28 billion of capex.
Oil Reversed Lower on Gulf De-Escalation Talks
Brent gave back an early 2.6% gain to trade below $98 after Qatar’s Emir Sheikh Tamim bin Hamad Al Thani discussed de-escalation diplomacy with President Trump. WTI churned around $90–91.
The gap between the sides remains wide. Iran wants the U.S. naval blockade lifted, sanctions eased and frozen assets released before it fully reopens the Strait of Hormuz.
Crypto Desk
- Bitcoin spot ETFs: -$430.2M net outflow on Thursday, reversing Wednesday’s +$74.6M inflow
- Ethereum spot ETFs: -$99.9M net outflow
- Bitcoin: about $75,766 late Thursday, down roughly 5.8% and testing the $75,000 level
- About $2.6B of Bitcoin options expired
- Hyperliquid Strategies applied to the CFTC for futures broker registration
Crypto sold off with the rest of the risk complex. ETF flows flipped back to heavy redemptions after a single green day.
Single-Stock News
- Lam Research (LRCX) — Approved a $25 billion share repurchase program and declared a $0.33 per-share dividend, a show of balance-sheet confidence in the middle of the chip rout.
- Tesla (TSLA) — Plans to scale back Cybertruck production by mid-next year while expanding Cybercab output. The stock fell 10.85% on Thursday with the rest of the AI complex.
- Nvidia (NVDA) — Fell about 9% to $181.60, erasing roughly $450 billion of market value in one session.
Single-Stock Movers
Gainers were rare — and earnings-driven:
- APP +31.04% (AppLovin, post-earnings)
- DNUT +30.68% (Krispy Kreme, post-earnings)
- COST +1.87%
Losers:
- AMD -17.47%
- MU -17.25%
- DELL -15.14%
- TSLA -10.85%
- ANET -10.81%
- AVGO -10.55%
- INTC -10.39%
- CRWD -10.07%
- PLTR -9.79%
- QCOM -9.52%
- NVDA -9.13%
- ORCL -6.94%
Double-digit losses across the entire chip and AI-infrastructure complex. The only green of size came from individual earnings beats.
Calendar — What to Watch
- Fri Nov 6 (today): October jobs report — nonfarm payrolls and the unemployment rate, released this morning. Earnings: Moderna, Humana, Charter, Oklo, TeraWulf, Elanco, Under Armour, Bloomin’ Brands.
- Week of Nov 9: Anthropic’s IPO roadshow had been expected to begin — whether it proceeds is now a live sentiment test for AI names.
- Tue Nov 10: October CPI.
- Watch whether volatility-control and leveraged-ETF selling continues into Friday’s session, per the Barclays model flagged above.
Sources
Associated Press closing figures; Reuters (market wrap, Anthropic, YMTC, semiconductor index); Bloomberg (trading desks, VARA, VIX); Wall Street Journal (hedge funds); Financial Times (AI backlash); CNN (Texas governor-elect, Fear & Greed); BofA Global Research / EPFR (fund flows); Finviz (heatmap and sector data); Earnings Whispers (earnings calendar).
Not financial advice.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — November 10, 2026 [0] | Master | 11-10 | 0 |
| Morning Briefing — November 9, 2026 [0] | Master | 11-09 | 0 |
| Morning Briefing — November 5, 2026 [0] | Master | 11-05 | 0 |
| Morning Briefing — November 2, 2026 [0] | Master | 11-02 | 0 |
| Morning Briefing — October 29, 2026 [0] | Master | 10-29 | 0 |
| Morning Briefing — October 28, 2026 [0] | Master | 10-28 | 0 |
| Morning Briefing — October 27, 2026 [0] | Master | 10-27 | 0 |
| Morning Briefing — October 23, 2026 [0] | Master | 10-23 | 0 |
| Morning Briefing — October 22, 2026 [0] | Master | 10-22 | 0 |
| Morning Briefing: October 21, 2026 [0] | Master | 10-21 | 0 |
| Morning Briefing: October 20, 2026 [0] | Master | 10-20 | 0 |
| Morning Briefing: October 19, 2026 [0] | Master | 10-19 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.