 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
October 27, 2026 at 6:22 am #2884
Anthropic’s IPO Filing Revives the AI Trade: Chips Rally Into Fed Week
Monday brought the AI trade back to life. The S&P 500 rose 0.70% and the Nasdaq-100 gained 1.09%, as Anthropic’s public IPO filing gave investors a fresh reason to buy the chip stocks that had been sliding for weeks.
The rally was narrow, not broad. Semiconductors surged while communication services lagged, and the median S&P 500 stock rose just 0.21%. The real tests still lie ahead: the Fed decision Wednesday, plus Microsoft and Alphabet earnings that evening.
Index Snapshot — Monday, October 26 Close
Index Close Day Change S&P 500 7,676.77 +0.70% Dow Jones 52,361.58 +0.28% Nasdaq Composite 26,169.38 +0.82% Nasdaq-100 29,273.40 +1.09% Russell 2000 2,786.42 +0.38% The S&P 500 added 53 points and the Dow added 146 points. Small caps trailed badly, rising just 0.38% against the PHLX Semiconductor Index’s 2.82% surge.
For context, both the S&P 500 and the Nasdaq entered the week off back-to-back weekly losses. Chip stocks remain in a bear market, with the SOXX semiconductor ETF down roughly 25% from its high and 13% this month alone.
Heatmap — Monday’s Market Map
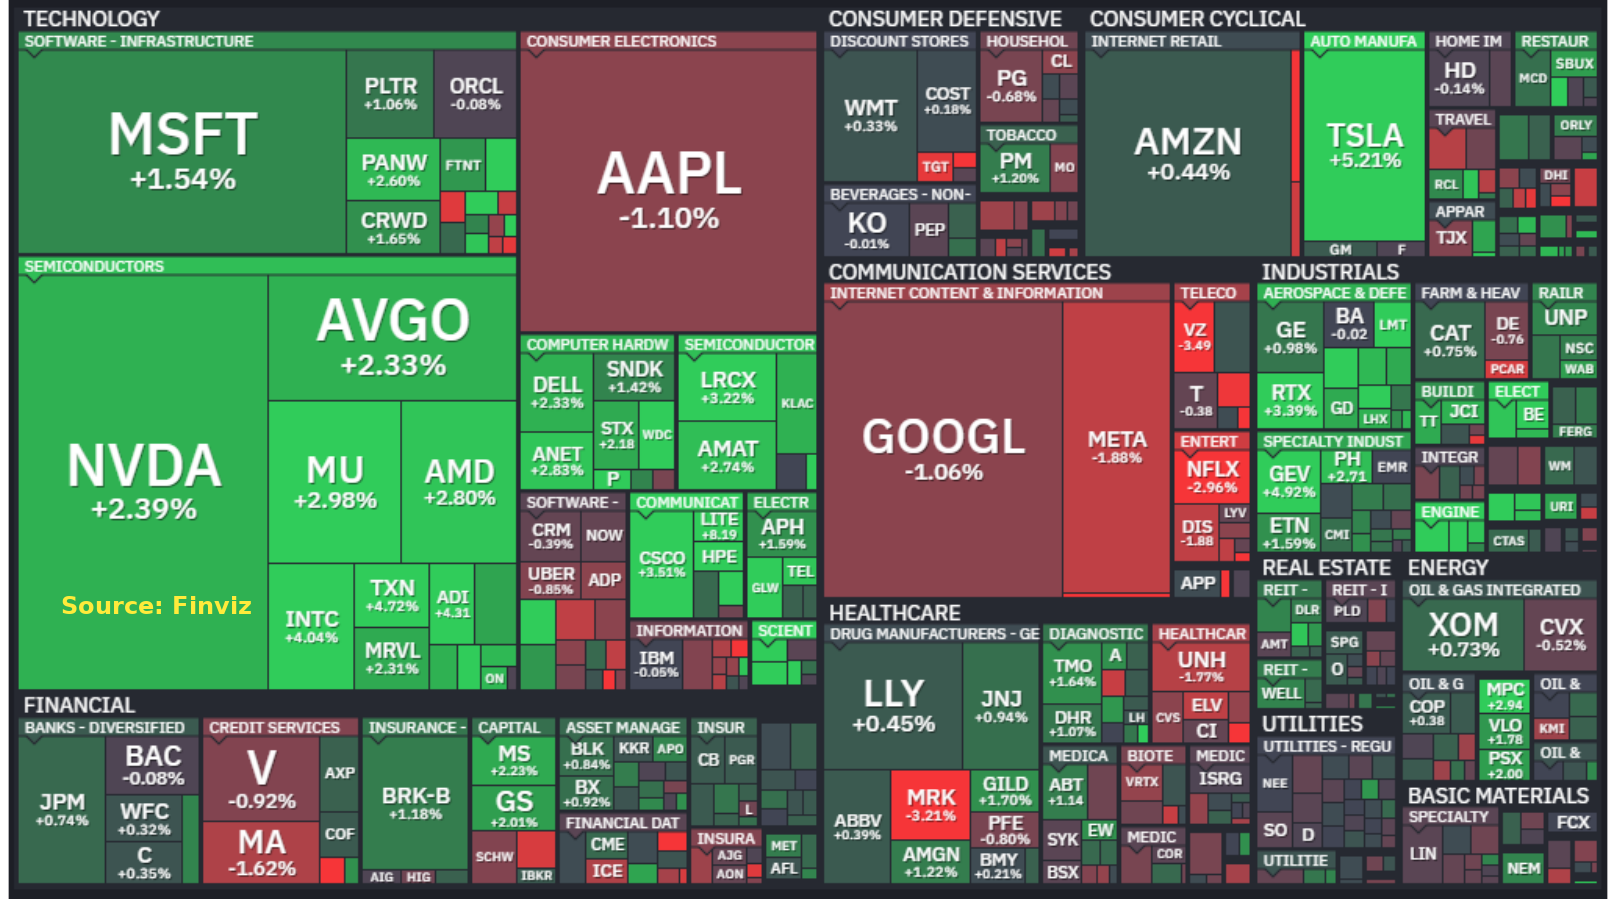
Monday’s map is a split screen: semiconductors glowing green on the left, communication services in red on the right. Tesla’s 5.21% jump stands out in consumer discretionary, while Apple, Alphabet, and Meta all finished lower.
Sector Performance — Monday
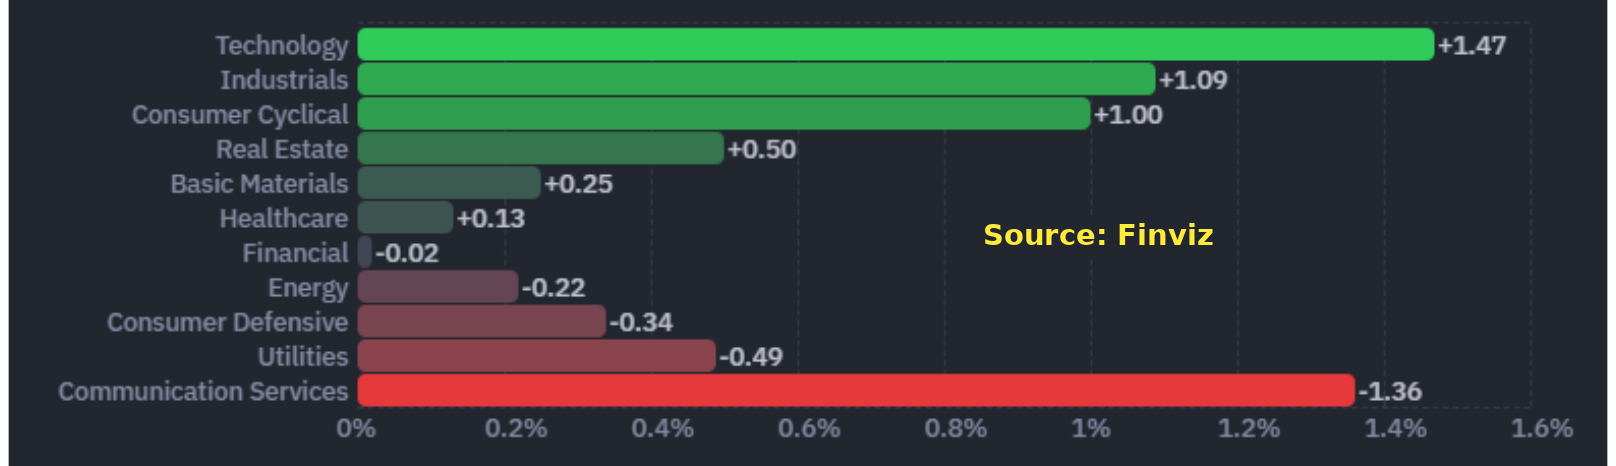
Sector Day Change Technology +1.47% Industrials +1.09% Consumer Cyclical +1.00% Real Estate +0.50% Basic Materials +0.25% Healthcare +0.13% Financials -0.02% Energy -0.22% Consumer Defensive -0.34% Utilities -0.49% Communication Services -1.36% Technology’s 1.47% gain led the market, while communication services fell 1.36% as Meta, Alphabet, and Netflix all declined. Energy eased 0.22% as oil pulled back from Friday’s war-driven spike.
Yields, Dollar, and Commodities
- U.S. 2-year Treasury yield: 4.720% (prior 4.686%)
- U.S. 10-year Treasury yield: 4.988% (prior 4.999%), holding just below 5%
- Dollar Index: about 102.0, little changed on the day
- Gold: $4,031.0 (prior $4,010.0)
- WTI crude: $101.34 (prior $103.44), down about 1.9%
- Natural gas: 3.039 (prior 3.047)
Oil gave back much of Friday’s premium as officials from Saudi Arabia, Pakistan, and Turkey headed to Tehran for talks. Brent crude eased to about $110.27 from near six-month highs.
Economic Data — Monday’s Releases
- September Chicago Fed National Activity Index: 0.07 (expected -0.10, prior -0.04)
- October Dallas Fed manufacturing index: 13.4 (expected 8.8, prior 9.8)
- U.S. 2-year Treasury auction: 4.708% (when-issued 4.705%)
Both regional readings beat expectations. The Dallas manufacturing gauge’s jump to 13.4 points to factory activity holding up better than feared, even as the Fed meets this week.
Market Sentiment
- CNN Fear & Greed Index: 28 (Fear), up from 27 at the prior close
- VIX: 18.39, down 5.45% from 19.45
Fear eased but did not lift. A reading of 28 still sits firmly in Fear territory, and it is below the 29 of a week ago and the 36 of a month ago. The VIX’s drop to 18.39 shows calmer trading, yet the level remains elevated for a market heading into a Fed decision and mega-cap earnings.
Top Stories
Anthropic files for what could be the largest IPO ever. The maker of the Claude AI models publicly filed Monday to list on Nasdaq under the ticker ANT. Its valuation jumped from $183 billion a year ago to $965 billion at its latest funding round, and it could approach $2 trillion after listing, which would pass Berkshire Hathaway.
The filing’s numbers explain both the excitement and the worry. First-half revenue hit $16.29 billion, up 1,304% from a year earlier, but growth slowed from about 140% in the second quarter to 45% in the third. Anthropic lost about $81 billion in the first half alone, and it has committed $417 billion to AI computing and infrastructure over the next 1 to 20 years.
Nearly half of first-half customer revenue, 48%, came through just three tech companies’ cloud marketplaces. With AI debt issuance surging and profitability questions mounting, how ANT trades after listing will be read as a verdict on the entire AI build-out, and on the IPO pipeline behind it, including OpenAI.
Anthropic lines up $63 billion to rent Broadcom chips. Bank of America, Blackstone, Citigroup, and Morgan Stanley unveiled a $63 billion financing tied to Broadcom’s strategic computing supply deal with Anthropic, with equipment deliveries starting in 2027. A special-purpose vehicle borrows the money, buys Broadcom’s XPU accelerators and networking gear, and leases it to Anthropic.
The deal nearly fell apart. Banks balked as rates rose and AI risk worries grew, until Broadcom CEO Hock Tan stepped into weekend negotiations, accepting higher loan pricing and easing lender concerns about Broadcom’s guarantees. Broadcom backstops losses if Anthropic misses lease payments, except for $18 billion of higher-risk debt, half of which Blackstone funds.
This is the largest AI infrastructure financing on record. It shows how the AI build-out is increasingly funded with debt rather than equity, which is exactly the fragility bears have been warning about.
Meta upsizes its stock sale to $97.5 billion. Meta raised its planned equity offering from $95 billion to $97.5 billion, one of the largest stock sales ever. Common stock of $25 billion priced at $625 a share, mandatory convertible preferred depositary shares of $12.5 billion at $50, plus an at-the-market program for up to about $60 billion of new non-voting Class C shares.
Nvidia agreed to buy $3 billion of the offering, and Nvidia, AMD, and Broadcom together committed up to $5 billion. Meta will use the proceeds for AI infrastructure and personal superintelligence development. Meta shares still fell 1.88% on Monday, a reminder that even AI leaders are being judged on dilution and cash burn.
Chips lead, Tesla jumps on an upgrade. The PHLX Semiconductor Index rose 2.82% to 11,083.47, with all 30 members gaining. Nvidia climbed 2.4%, Micron rose 3%, Broadcom added 2.3%, and AMD jumped 2.8%.
Tesla surged 5.21% to $391.62 after Barclays upgraded the stock to Overweight from Neutral, with a $450 price target. Tesla was the day’s most-traded stock at $20.7 billion of volume.
iPhone 18 Pro starts strong in China, soft in the U.S. and Japan. Counterpoint Research reports first-three-weeks global sales of the iPhone 18 Pro series up 3.1% versus the iPhone 17 Pro series. China surged 29%, the strongest of any market, helped by larger launch supply and price hikes from Chinese Android rivals.
The U.S. fell 4% and Japan dropped 27%, with higher prices and modest design changes blamed in the U.S. and currency-driven price pressure in Japan. The Pro Max model took 56% of series sales, slightly below last year’s 57%.
U.S. and Canada reopen steel and auto tariff talks. Reuters reports the two countries are negotiating relief from Section 232 tariffs of up to 50% on Canadian steel and 25% on autos, after talks broke down in August. A Canadian source raised the possibility of a deal before the November 3 midterm elections.
The politics are pressing. Tariffs have become a burden even for Republican candidates in border states. But Washington is demanding further concessions, and Canadian industry expects any deal to be limited rather than comprehensive. President Trump has said tariffs on Canadian steel and autos will rise to 50% from January 1, 2027.
Saudi oil hub attacked, fire contained, oil eases anyway. Bloomberg reports Saudi Arabia contained a fire near Ras Tanura, its largest oil export terminal, after an attack early Tuesday, with damage still unconfirmed. Saudi defenses also intercepted three Houthi ballistic missiles aimed at the east.
Houthi rebels have attacked Aramco facilities across Saudi Arabia in recent weeks. Oil still fell Monday, as the Tehran talks track outweighed the attack headlines for now.
Bank of Japan expected to hold; Bank of Korea warns on chips. A CNBC survey of 16 economists and analysts found unanimous expectations that the Bank of Japan holds its rate at 1.25% this week, with all expecting another hike in December or January. Thirteen see the terminal rate reaching 1.75% to 2% by mid-2027.
The Bank of Korea warned that if U.S. Big Tech AI spending slows next year, Korean chip exports could fall $50 billion to $100 billion below forecast, cutting 2027 growth by about 0.4 percentage points. It is a blunt reminder that the AI trade’s second-order effects reach far beyond U.S. mega-caps.
Also in the headlines. Intel agreed to acquire Israeli quantum software startup Classiq, combining its hardware with software and AI development tools. BlackRock bond chief Rick Rieder called the AI debt rush the best bond opportunity in years, favoring secured bonds of solid companies and short single-A portfolios yielding about 7%. JPMorgan’s Bob Michele sees U.S. bonds returning 7% to 8% over 12 months. The U.S. Trade Representative moved to extend the pause on China-related port fees to January 9, 2027.
Crypto Desk
- Bitcoin spot ETF (Monday): about $110 million net inflow
- Ethereum spot ETF (Monday): about $88.58 million net outflow
- Bitcoin: slipped back below $80,000 late Monday, after dipping near $79,330 over the weekend
Ripple won final approval from the Office of the Comptroller of the Currency to establish Ripple National Trust Bank. The bank will manage reserves backing the RLUSD stablecoin, whose market value has more than doubled this year to $2.6 billion, and offer trust-based digital asset custody.
BlackRock is also pushing ahead with a tokenized money-market fund linked to a yen stablecoin. The approvals landed just after the OCC published final rules implementing the GENIUS Act stablecoin law.
Single-Stock News
- Bloom Energy (BE): the FCC conditionally approved Bloom Energy and Hitachi Energy power inverters.
- Instacart (CART): reports say Instacart is reviewing a potential sale and has contacted Uber and DoorDash; treat as rumor, not confirmed.
- SK hynix (SKHY): reports say a 50 trillion to 60 trillion won additional shareholder return plan will be announced October 28; unconfirmed.
- Microsoft (MSFT): offered voluntary separation to 6,000 employees as part of cost cutting.
- IBM and Nvidia (NVDA): expanded cooperation on AI agent security.
- U.S. corporate bonds: investment-grade issuance is headed for a record $1.76 trillion this year.
Single-Stock Movers — Monday
Winners: Tesla +5.21%, GE Vernova +4.92%, Texas Instruments +4.72%, Analog Devices +4.31%, Intel +4.04%, Lam Research +3.22%, Micron +2.98%, AMD +2.80%.
Losers: Verizon -3.49%, Merck -3.21%, Netflix -2.96%, Meta -1.88%, UnitedHealth -1.77%, Mastercard -1.62%.
Verizon fell after a quarterly revenue miss, while Merck and UnitedHealth extended their healthcare slide. Monday’s breadth was weak: only 289 S&P 500 stocks rose against 211 decliners.
Earnings Whispers — Monday’s Reports
- Verizon (VZ), before the open.
- Cadence Design (CDNS), after the close: EPS and revenue beat, fourth-quarter EPS guidance raised, full-year EPS and revenue guidance raised.
- Amkor (AMKR), after the close: EPS and revenue missed, fourth-quarter revenue guidance cut.
- Rambus (RMBS), after the close: EPS beat, fourth-quarter EPS and revenue guidance raised.
- Welltower (WELL), after the close: funds from operations and revenue beat.
- Dorman (DORM), after the close: EPS beat, revenue missed, full-year EPS guidance cut.
- Celestica (CLS), after the close: EPS and revenue beat.
Calendar — What to Watch
- Tuesday, October 27: durable goods orders, new-home sales; Fed meeting begins.
- Wednesday, October 28: FOMC decision at 2:00 p.m. ET; Microsoft and Alphabet earnings after the close.
- Thursday, October 29: third-quarter GDP and PCE inflation; Amazon and Intel earnings; European Central Bank decision.
- Friday, October 30: Bank of Japan decision; Exxon Mobil and Chevron earnings.
Wednesday is the week’s hinge. A Fed decision that disappoints rate-cut hopes, or mega-cap earnings that question AI spending, could quickly reverse Monday’s relief rally.
Sources
- Reuters market coverage of Monday’s close, via Metapress
- Market Briefer: The Global Close, October 26, 2026
- HDFC Sky: Nasdaq Jumps 0.82% as Anthropic IPO Filing Revives AI Trade
- Wall Street Journal: Broadcom CEO intervened to seal the $63 billion Anthropic debt deal
- Bloomberg: Saudi Arabia contains fire near Ras Tanura oil hub after attack; Bank of Korea chip export warning
- CNBC survey: Bank of Japan expected to hold rates this week
- Counterpoint Research: iPhone 18 Pro initial global sales
- Reuters: U.S., Canada working on deal to ease steel, auto tariffs
- U.S. Office of the Comptroller of the Currency: Ripple National Trust Bank approval
- Finviz: sector performance and market heatmap
- CNN: Fear & Greed Index
What do you think: does Anthropic’s IPO filing mark a real revival of the AI trade, or just a relief bounce before the Fed and Big Tech earnings? Share your view in the comments.
Auto-posted by the Bull Lounge news desk.
Not financial advice.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — November 10, 2026 [0] | Master | 11-10 | 0 |
| Morning Briefing — November 9, 2026 [0] | Master | 11-09 | 0 |
| Morning Briefing — November 6, 2026 [0] | Master | 11-06 | 0 |
| Morning Briefing — November 5, 2026 [0] | Master | 11-05 | 0 |
| Morning Briefing — November 2, 2026 [0] | Master | 11-02 | 0 |
| Morning Briefing — October 29, 2026 [0] | Master | 10-29 | 0 |
| Morning Briefing — October 28, 2026 [0] | Master | 10-28 | 0 |
| Morning Briefing — October 23, 2026 [0] | Master | 10-23 | 0 |
| Morning Briefing — October 22, 2026 [0] | Master | 10-22 | 0 |
| Morning Briefing: October 21, 2026 [0] | Master | 10-21 | 0 |
| Morning Briefing: October 20, 2026 [0] | Master | 10-20 | 0 |
| Morning Briefing: October 19, 2026 [0] | Master | 10-19 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.