 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
November 9, 2026 at 7:16 am #3385
Stocks ended a brutal week with a split decision. Chip shares bounced on Friday after Thursday’s rout, but a blowout jobs report kept a December rate hike firmly in play.
The week still closed deep in the red — the S&P 500 lost 2.7%. And over the weekend, the Nvidia story took a stunning turn that will dominate Monday’s trade.
Index Snapshot — Friday, November 6 Close
Index Close Change S&P 500 7,376.86 +23.13 (+0.31%) Dow Jones Industrial Average 51,285.73 -237.33 (-0.46%) Nasdaq Composite 24,579.42 +264.43 (+1.09%) Nasdaq-100 26,989.99 +1.35% Russell 2000 2,754.11 +0.89% Technology led the bounce while the Dow sagged under higher yields. The Nasdaq remains in a correction despite Friday’s gain.
Market Heatmap
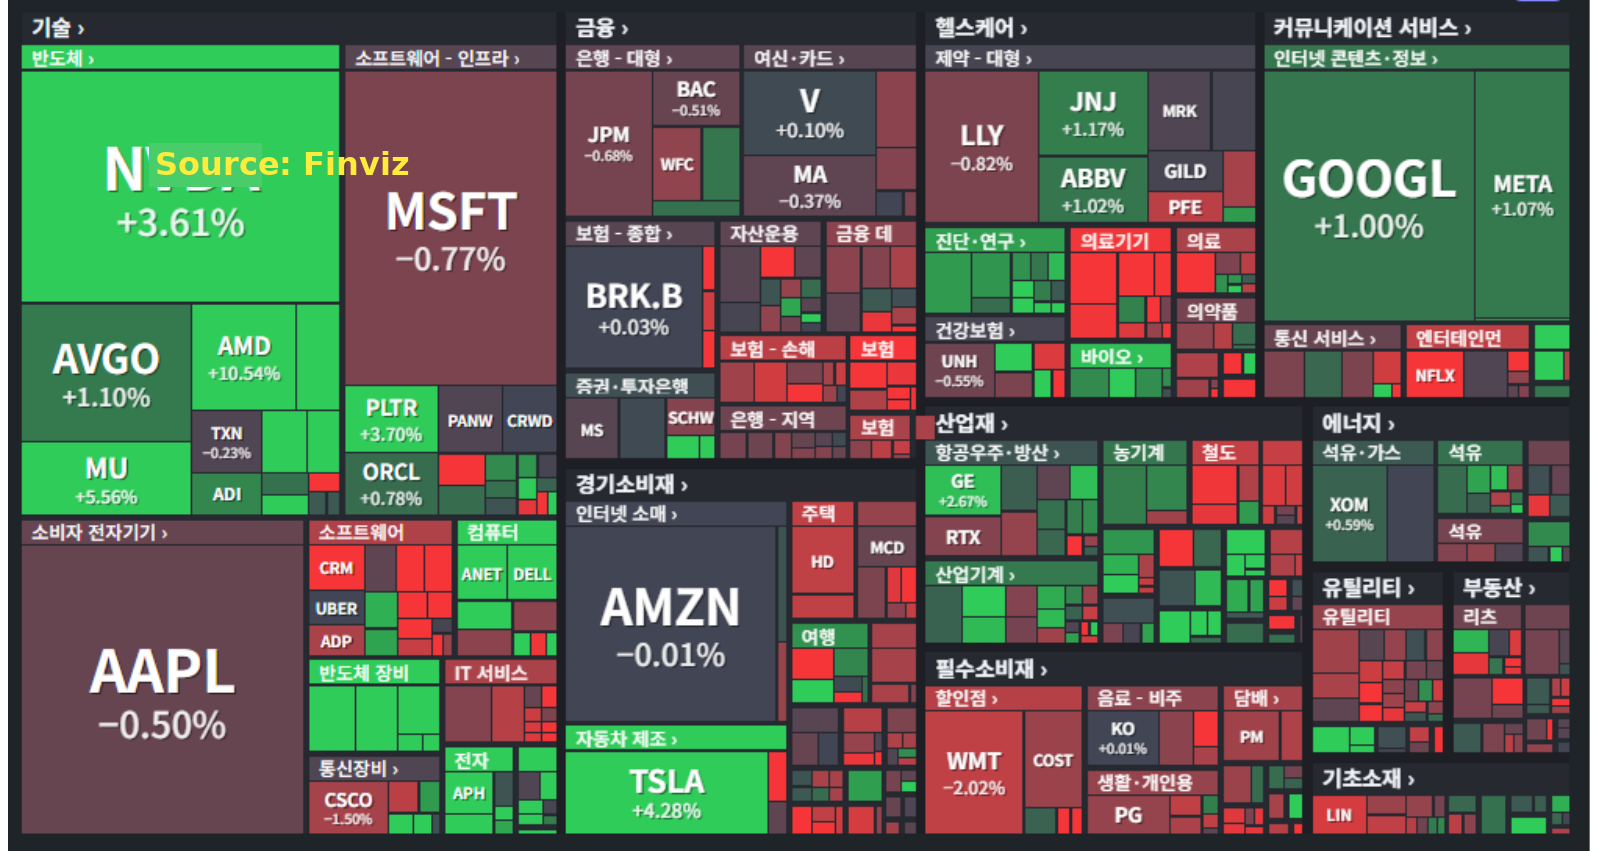
The same chips that led Thursday’s plunge led Friday’s recovery. AMD surged 10.54%, Micron gained 5.56% and Nvidia rose 3.61%.
Sector Performance
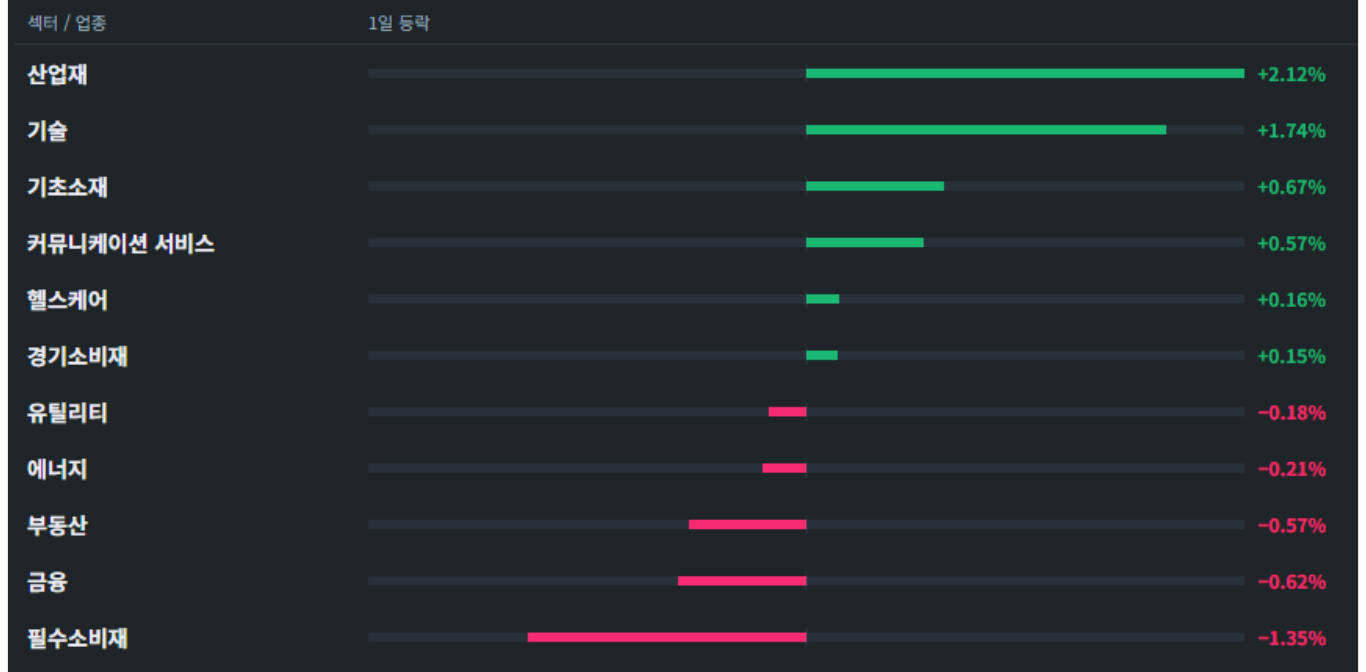
- Industrials: +2.12%
- Technology: +1.74%
- Basic Materials: +0.67%
- Communication Services: +0.57%
- Healthcare: +0.16%
- Consumer Cyclical: +0.15%
- Utilities: -0.18%
- Energy: -0.21%
- Real Estate: -0.57%
- Financials: -0.62%
- Consumer Defensive: -1.35%
A classic risk-on rotation: cyclicals and tech up, defensives down. Walmart’s 2.02% drop dragged staples to the bottom.
Yields, Dollar & Commodities
- 2-year Treasury yield: 4.512%, down on the week despite Friday’s hot jobs print
- 10-year Treasury yield: 4.859%
- Dollar index (DXY): 102.279, up from 101.600
- Gold: $4,079.5, down slightly from $4,097.9
- WTI crude: $90.34, down from $91.20 (see the oil story below)
- Natural gas: $3.003
- December Fed hike odds: about 78% after the jobs report, up from roughly 67–70% before it (Reuters)
The jobs report pushed hike expectations higher and lifted the dollar. Yields stayed contained, which let the equity bounce hold.
Economic Data
- Nonfarm payrolls, October: +165,000 vs. about 65,000 expected
- Unemployment rate: 4.1% vs. 4.2% expected
- Revisions: September raised to 60,000 from 29,000; August to 186,000 — a combined +84,000
- Average hourly earnings: +0.4% on the month to $38.00, +3.1% year over year
- Michigan consumer sentiment (prelim. November): 51.0 vs. 48.0 expected
- Michigan inflation expectations: 4.3% vs. 4.6% expected
- Baker Hughes rig count: 603, unchanged
The labor market is not cracking — it is re-accelerating. That is good news for earnings and bad news for anyone hoping the Fed is done hiking.
Market Sentiment
- CNN Fear & Greed Index: 24 (Extreme Fear)
- VIX: 25.64, down about 9% from Thursday’s 28.18 spike
Volatility cooled but stayed elevated. Positioning data (see Top Stories) shows investors are still heavily underweight equities — fuel for a squeeze if the news flow improves.
Top Stories
Nvidia’s Board Is Investigating Its CEO — and Jensen Huang Has Admitted an Affair
This is the weekend’s biggest story, and it is important to separate what is confirmed from what is alleged. On Sunday, Huang told Nvidia staff in a memo that he had been “unfaithful” to his wife, took full responsibility, and pledged to cooperate with an investigation (CNN).
Nvidia’s board the same day announced that a committee of independent directors, assisted by outside counsel, will investigate reports that Huang was the target of a foreign intelligence effort. The board said it “has no reason to believe that either national security or NVIDIA secrets were compromised,” and Huang remains CEO.
What is alleged, not proven: the New York Times has reported that the relationship was with Alice Huang (no relation), a former executive at Singapore-based Megaspeed International, and that U.S. intelligence officials concluded she passed information to Beijing. Megaspeed bought more than $4.8 billion of Nvidia chips over two years and is under a Singapore police investigation; China’s foreign ministry on Monday called the spying allegation “purely groundless speculation.”
The political pressure is real. The Republican chairs of three House committees — Foreign Affairs, the Select Committee on the CCP, and Intelligence — have requested Huang’s testimony, with a response due by November 11 and a closed-door briefing sought for November 18. President Trump has defended Huang, but Bernstein notes the episode spotlights Nvidia’s key-man risk: there is no clear successor. Nvidia shares rose 3.61% on Friday, before the Sunday admission — Monday is the first real market test.
Wall Street Is Split: Buy the Dip, or Stay Defensive?
The bulls: Morgan Stanley’s Mike Wilson says the correction is in its final phase, with the S&P 500 nearing his 7,100–7,300 target zone. He advises adding quality cyclicals whose valuations fell while earnings held up. JPMorgan’s Mislav Matejka also says buy the dip and stay overweight into year-end, calling semiconductors his favorite way to play AI.
The bears: Citi cut U.S. equities and global tech to neutral, citing crowded positioning, peak valuations and slowing EPS growth, and upgraded Europe ex-UK. Deutsche Bank says overall equity positioning has plunged to a big underweight — the largest weekly drop since April 2025 — with mega-cap tech positioning at a 3.5-year low.
RBC’s Lori Calvasina splits the difference: sentiment gauges look washed out and U.S. valuations have de-rated more than in a typical correction, but a true bottom needs earnings and growth to hold. Tuesday’s CPI will arbitrate.
Anthropic Will Proceed With Its IPO Roadshow This Week
Anthropic is going ahead with its official IPO roadshow this week despite the AI selloff, according to The Information. The listing is targeted for the week of November 16, before Thanksgiving.
The deal was expected to raise more than $80 billion at a $1.5 trillion valuation. After the last two weeks, that price tag may have to come down — making this offering the market’s verdict on AI valuations.
Trump Floats an Immigration Deal: “I Was Too Tough”
In a CBS “60 Minutes” interview, President Trump said his deportation campaign may have been “too tough” and signaled he could negotiate with Democrats to let some long-term undocumented residents stay legally. He drew the line at violent criminals and drug traffickers, and named Texas Senator-elect James Talarico as a potential partner.
Trump also conceded a rare political failure: he said the GOP’s midterm drubbing partly reflected a “messaging failure” on the economy. And he said he would not oppose AI safety regulation if it does not cost the U.S. its technology lead.
China Extends the Tariff Truce — and Fights the Yuan’s Rally
Beijing formalized the trade truce on Friday, extending the pause on its 24% additional U.S. tariffs to January 10 while keeping the 10% blanket rate. Port fees on U.S. ships stay paused too, and Presidents Trump and Xi are expected to meet for a third time this year at the APEC summit in Shenzhen later this month.
Separately, Chinese banks have raised dollar deposit rates to as much as 4–4.5% — the highest since at least 2023 (Reuters). The goal is to slow the yuan, which has gained about 10% against the dollar since early 2025 and hit a four-year high of 6.6449 last week.
CoreWeave Asks Texas’s Governor-Elect to Keep Data Centers Welcome
CoreWeave CEO Michael Intrator wrote to Texas Governor-elect Gina Hinojosa asking to work with her transition team on “clear, sustainable standards” for data-center development. Hinojosa campaigned on a statewide construction pause; since winning, she has promised to keep Texas business-friendly with stronger guardrails.
The stakes are spreading: Democrats now hold 29 governorships, and many are echoing voter demands for data-center moratoriums. How Texas — home to Tesla, SpaceX and a huge AI buildout — lands will set the tone nationally.
Alphabet Eyes First Hong Kong and Singapore Dollar Bonds
Alphabet is weighing its first-ever Hong Kong dollar and Singapore dollar bond sales — roughly $1–1.5 billion equivalent in HKD and about $1.5 billion in SGD — possibly as soon as this month (Bloomberg). It follows debut Australian dollar, Swiss franc, sterling, Canadian dollar and yen deals this year.
The funding tour has a cost: last week’s €6 billion euro deal priced at noticeably wider spreads than Alphabet’s first euro sale in May. Investors are charging the AI builders more as their borrowing piles up.
Oil Slips as Trump Signals Restraint on Iran
Crude eased after President Trump said he is “very unlikely” to order further strikes on Iran while negotiations progress. Shipping attacks near Hormuz continue, so the geopolitical premium has not vanished.
Over the weekend, Houthi rebels claimed an attack on Saudi Aramco’s Riyadh office, and a Ukrainian drone strike set a fire at Russia’s Kirishi refinery. Energy infrastructure remains a live front in two wars.
Crypto Desk
- Bitcoin spot ETFs (Friday): -$411.9M — a sixth straight day of outflows
- Ethereum spot ETFs (Friday): -$93.19M
- Bitcoin: around $75,700 over the weekend, on a fifth straight weekly loss
- Democrats in Congress signaled tougher regulation of prediction markets — Kalshi and Polymarket in focus
- ARK Invest filed to launch 14 thematic ETFs, including AI and tokenization themes
The ETF outflow streak is now the story: six straight red days for Bitcoin funds. Until that flips, rallies have no institutional bid behind them.
Single-Stock News
- Nvidia (NVDA) — Beyond the board investigation (Top Stories): Nvidia announced investments in four Korean AI startups including Upstage and Motif, and a separate AI chip and data-center cooperation with SK Telecom and Rebellions.
- Alphabet (GOOGL) — Senator Ed Markey urged Google to let schools disable AI features in Search while keeping the search engine itself; Google says AI Overviews are too deeply integrated to separate. Google also warned Australia’s proposed Digital Duty of Care law — fines up to A$109M — could force it to cut off under-18s from Gmail.
- IBM (IBM) — The EU is suing IBM and two other companies over failures in a border-management system development project.
Single-Stock Movers — Friday
Gainers:
- AMD +10.54%
- MU +5.56%
- TSLA +4.28%
- PLTR +3.70%
- NVDA +3.61%
- GE +2.67%
Losers:
- DKNG -21% (DraftKings, on the cost of its prediction-markets push)
- WMT -2.02%
- CSCO -1.50%
- LLY -0.82%
- MSFT -0.77%
The bounce was narrow and violent in both directions. Thursday’s chip losers became Friday’s winners, almost tick for tick.
Calendar — What to Watch
- Mon Nov 9: Market digests Berkshire Hathaway’s Q3 results (released Saturday). Earnings after the close: Rocket Lab, AST SpaceMobile.
- Tue Nov 10: October CPI at 8:30 a.m. ET — the last inflation print before the Fed’s December 8–9 meeting. TSMC October sales. Earnings: Rigetti; CoreWeave after the close.
- Wed Nov 11: Veterans Day — bond market closed, stock market open. Deadline for Nvidia’s response to the House committees’ letter.
- Thu Nov 12: Earnings: Cisco, Applied Materials, Cerebras, Nebius. Anthropic’s IPO roadshow runs this week.
- Fri Nov 13: October PPI and existing home sales.
- Ahead: Anthropic pricing expected the week of Nov 16; Nvidia earnings Nov 17; Trump–Xi meeting at APEC in Shenzhen later this month; closed-door House briefing on Nvidia sought for Nov 18.
Sources
Associated Press and BLS (closing figures, jobs report); Reuters (hike odds, China deposit rates, fund positioning context); Bloomberg (Nvidia board probe, Alphabet bonds); CNN (Huang staff memo, Fear & Greed); Wall Street Journal and New York Times (Megaspeed reporting); The Information (Anthropic roadshow); CBS “60 Minutes” (Trump interview); Finviz (heatmap and sector data); Earnings Whispers (earnings calendar).
Not financial advice.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — November 10, 2026 [0] | Master | 11-10 | 0 |
| Morning Briefing — November 6, 2026 [0] | Master | 11-06 | 0 |
| Morning Briefing — November 5, 2026 [0] | Master | 11-05 | 0 |
| Morning Briefing — November 2, 2026 [0] | Master | 11-02 | 0 |
| Morning Briefing — October 29, 2026 [0] | Master | 10-29 | 0 |
| Morning Briefing — October 28, 2026 [0] | Master | 10-28 | 0 |
| Morning Briefing — October 27, 2026 [0] | Master | 10-27 | 0 |
| Morning Briefing — October 23, 2026 [0] | Master | 10-23 | 0 |
| Morning Briefing — October 22, 2026 [0] | Master | 10-22 | 0 |
| Morning Briefing: October 21, 2026 [0] | Master | 10-21 | 0 |
| Morning Briefing: October 20, 2026 [0] | Master | 10-20 | 0 |
| Morning Briefing: October 19, 2026 [0] | Master | 10-19 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.