 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic has 0 replies, 1 voice, and was last updated 2 weeks, 1 day ago by
Master 👑 Lv.100 Master.
-
AuthorPosts
-
October 1, 2026 at 6:13 am #2053
U.S. stocks ended September on a soft note as cooler-than-expected inflation failed to stop the bond selloff — the S&P 500 fell 0.25% to 7,651.54 while the Dow dropped 0.86% to 50,906.05. The Nasdaq 100 edged up 0.23% to 30,408.50. August core PCE came in at 3.0% versus 3.3% expected and Q2 GDP was revised up to 2.2%, but the 10-year yield still climbed to 5.29% — and overnight it spiked to 5.34%, the highest since 2002, as Middle East oil gains fanned a global bond selloff. Gold slipped to $4,189.80 while WTI crude rose to $90.33. Today brings jobless claims and the ISM manufacturing PMI, with Accenture reporting before the open and Nike after the close.
Market Snapshot — Wednesday, September 30
S&P 500 · Wed close
7,651.54 ▼ -0.25%
Prev close 7,670.84
52-wk high 7,816.70
52-wk low 6,316.91Nasdaq Composite · Wed close
26,861.06 ▲ +0.24%
Prev close 26,797.54
52-wk high 27,288.79
52-wk low 20,690.25Dow Jones · Wed close
50,906.05 ▼ -0.86%
Prev close 51,349.92
52-wk high 54,744.33
52-wk low 45,057.28The Nasdaq 100 rose 0.23% to 30,408.50 while the Russell 2000 slipped 0.39% to 2,796.86. Closes verified against Naver Pay Securities and market data.
S&P 500 Sectors
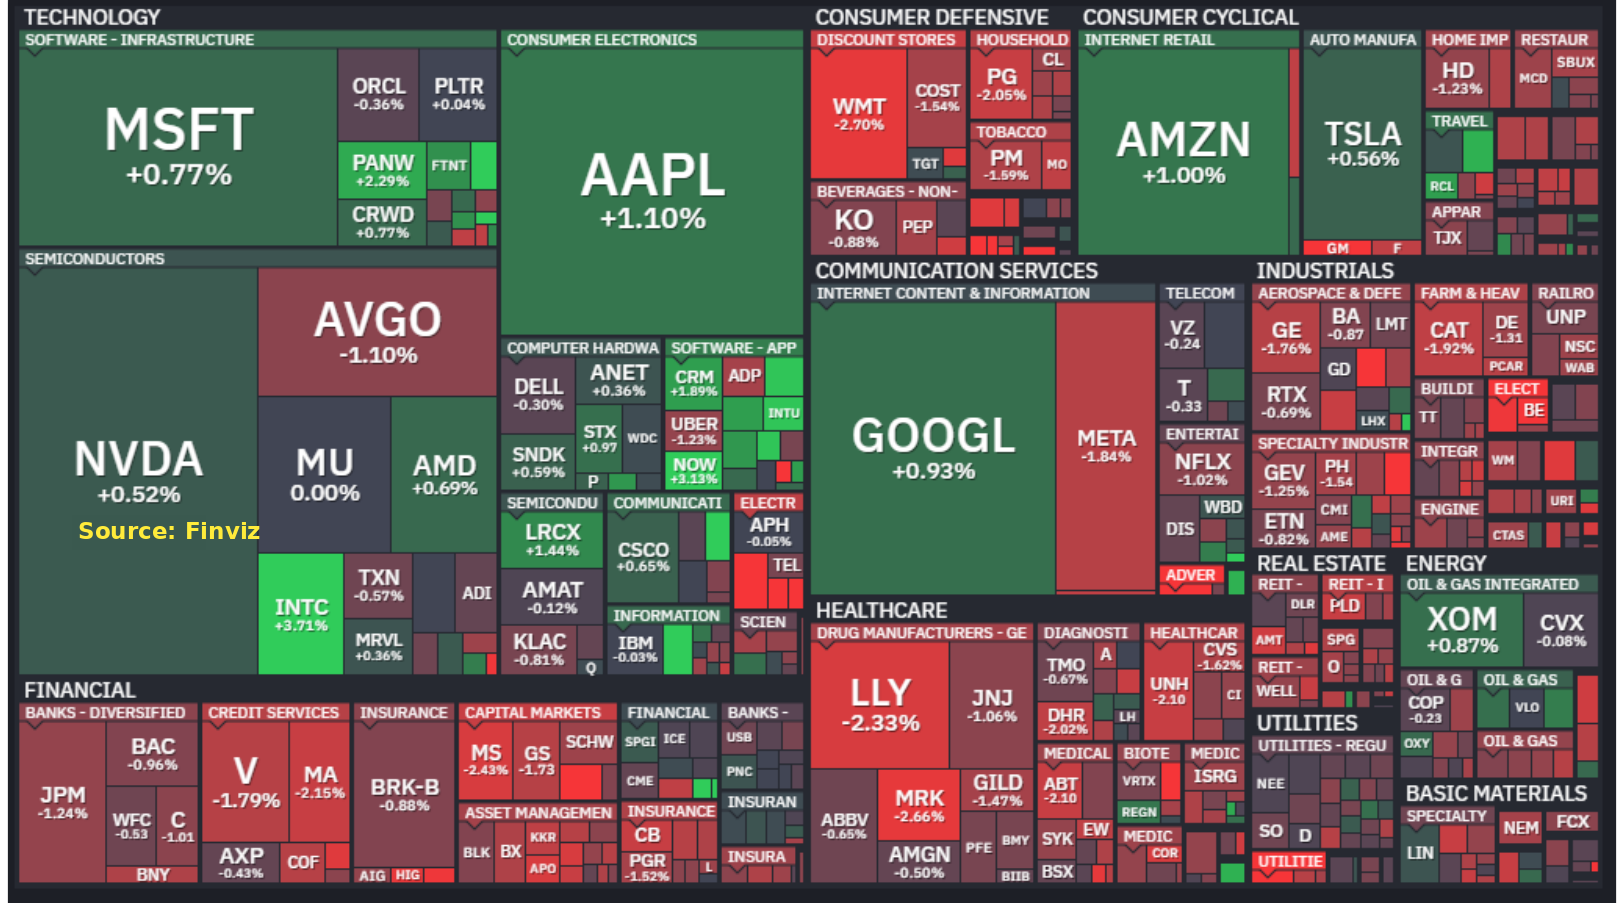

Technology (+0.34%) was the only sector in the green as yields kept climbing, led by Apple (+1.10%), Alphabet (+0.93%) and Microsoft (+0.77%). Consumer defensive (-1.56%) was the biggest drag, followed by real estate (-1.36%), healthcare (-1.18%), financials (-1.14%), industrials (-0.89%), basic materials (-0.74%) and utilities (-0.54%). Energy (-0.08%), communication services (-0.07%) and consumer cyclical (-0.03%) finished roughly flat. Source: Finviz.
Yields, Dollar & Commodities
2-YEAR TREASURY
4.893%
▲ +1.4bp from 4.879%10-YEAR TREASURY
5.289%
▲ +5.5bp from 5.234%DOLLAR INDEX (DXY)
101.461
▲ from 101.379GOLD
$4,189.8
▼ -0.6% from $4,215.0WTI CRUDE
$90.33
▲ +1.6% from $88.94NATURAL GAS
$3.012
▼ -0.1% from $3.014The bond selloff resumed with force: the 10-year climbed 5.5bp on the day and spiked to 5.34% overnight — the highest since 2002 — as rising Middle East oil prices fueled bets that central banks will keep hiking, on top of massive government borrowing and AI infrastructure capital demand. Gold slipped 0.6% to $4,189.80 while WTI jumped 1.6% to $90.33. Goldman Sachs pushed its Fed hike forecast from October to December after the cool PCE print, and now sees a decent chance the Fed concludes no further hike is needed at all. Markets price only a 38% chance of an October hike.
Economic Data
Indicator Actual Expected Previous ADP Employment Change (Sep) 90K 75K 38K PCE Price Index (Aug) 3.4% 3.7% 3.7% Core PCE Price Index (Aug) 3.0% 3.3% 3.3% Q2 GDP Growth (final) 2.2% 1.5% 1.5% Q2 Core PCE (final) 3.3% 3.6% 3.6% Chicago PMI (Sep) 58.8 51.0 47.1 EIA Crude Inventories +922K -455K +2,969K A clean sweep of cool inflation and solid growth: private payrolls rebounded to 90K after three soft months, core PCE cooled to 3.0% versus 3.3% expected, and Q2 GDP was revised up to 2.2%. The Chicago PMI surged to 58.8, its strongest in years. Fed officials Barkin and Cook both spoke, and the President held a commerce-related announcement with the Commerce Secretary.
Market Sentiment
CNN FEAR & GREED
31 — Fear
Updated Oct 1, 5:17 AM ET. Ticked up from 30 at the previous close as the cool inflation print landed, but still firmly in Fear territory (35 a week ago, 44 a month ago).VIX
16.32
Wednesday close (prev 16.04, +1.7%). Volatility crept higher into the close as the bond selloff resumed; intraday high 16.61, low 15.62.Top Stories
1. 10-year hits 5.34% — highest since 2002. The 10-year Treasury yield spiked to 5.34% intraday as Middle East oil gains drove a global bond selloff, the highest since 2002. High oil is fueling bets that central banks will hike more, on top of massive government borrowing and AI infrastructure capital demand. Markets now look to Friday’s September jobs report for the Fed’s next move. (market data)
2. Global bond selloff spreads to Asia. Japan’s 10-year yield climbed to 3.1%, near a 30-year high, while Australia’s hit 5.4%, the highest since 2011. September was the worst month for U.S. Treasuries in four years. Japan’s Tankan survey showed large-manufacturer sentiment at its strongest in over eight years, and the yen slid to 158.16 per dollar. (market data)
3. Why yields keep rising — ten reasons. Inflation, the oil surge, government borrowing, AI capex demand, tariff-driven price pressure and a shrinking private buyer base are all pushing yields higher at once. More than half of surveyed investors now expect the U.S. 30-year yield to reach 6% by year-end. (investor survey)
4. WSJ: the 60/40 portfolio is back. With bond yields at 20-year highs, money managers are pitching clients on bonds again — and for the first time since 2021, stocks and bonds are moving in opposite directions. Advisors favor short-to-intermediate bonds and bond ladders. The caveat: with the S&P 500’s top 10 at 40% concentration and 49% of new issuance AI-linked, stocks and bonds could start moving together again on AI news. (WSJ)
5. Micron’s bullish guide, thinner margins. Micron’s fiscal Q1 revenue outlook came in well above consensus on AI data-center and HBM demand — but broad-based employee bonuses will push adjusted gross margin down to 86.3% from last quarter’s 87% and below the 86.7% consensus. The stock slipped about 1% after hours. (company announcement)
6. Google unveils Gemini 4 Argon. Google’s next frontier model targets real-world software engineering, enterprise knowledge work and cybersecurity defense, with context jumping from 64,000 to 1 million tokens. It hit 77.9% on DeepSWE v1.1 (state of the art) and joint-first 68% on CWE-bench v1 — though internally, employees are reportedly skeptical of the launch. (Google)
7. Tencent leases 100,000 AI chips from Oracle — $7B. The five-year deal gives Tencent advanced AI chips it cannot obtain in mainland China, underscoring how far Chinese tech will go to secure computing power. (FT)
8. Citi: start buying memory stocks in October. Citi’s Peter Lee says fears of a demand slowdown are overdone and recommends accumulating memory names from October, keeping a Buy on SK Hynix with a ₩3 million target. He sees 2027 HBM bit-supply growth of 62% on severe AI-driven shortages. (Citi)
9. Japan plans a $140B AI data-center push with Dell and JERA. Japan wants the largest AI infrastructure hub outside the U.S. and China: Apollo-backed funding for a 400MW facility in Chiba by 2028, scaling to 3–4GW over five years. (market data)
10. KKR warns on AI credit risk. With tech on track to invest $8 trillion in AI infrastructure by 2030, AI-related debt has hit $600B — 6.3% of U.S. investment-grade bonds, more than double its 29-year average share. Off-balance-sheet vehicles mean the true AI exposure is far larger, and a growth scare could hit credit much harder than equities. (KKR)
11. Goldman pushes its Fed hike call to December. After the cool PCE print, Goldman moved its next-hike forecast from October to December — and now sees a decent chance the Fed concludes no further hike is needed at all. Markets price only a 38% chance of an October move. (Goldman Sachs)
12. U.S. presses France and Germany on diesel reserves. Reuters reports the Trump administration demanded emergency diesel stockpile releases to lower global fuel prices — or face a U.S. diesel export ban. The EU is coordinating a joint response, while China canceled some October fuel shipments to protect domestic supply. (Reuters; Bloomberg)
13. Tesla’s European rebound extends. September registrations rose 61.9% in France, 38.4% in Sweden and 2.2% in Norway, extending the recovery from a two-year slump — though January–August EU registrations are still down 43.3% while the overall BEV market grew 38.8%. (market data)
14. Amazon’s secret plan for life without the USPS. A leaked internal document reveals “Project Aurelian”: Amazon aims to cover 99.9% of U.S. demand with its own delivery network by 2029, expanding to 95% of ZIP codes (39,400). The current USPS contract runs through September 2029. (Business Insider)
Crypto Desk
BITCOIN
~$83.7K
steady near $83–84KETHEREUM
~$2,690
firmed from $2,670BTC SPOT ETF (SEP 30)
-$148M
net outflowETH SPOT ETF (SEP 30)
-$59.6M
net outflowCrypto held its ground near $83.7K for Bitcoin and $2,690 for Ether despite 5.3%+ Treasury yields, but spot ETFs bled on the final day of September: -$148M for BTC and -$59.6M for ETH (September as a whole still saw +$2.65B of net BTC inflows). Citi raised its 12-month targets to $113K for Bitcoin (from $82K) and $3,028 for Ether (from $2,240), citing stronger crypto activity, a friendlier macro backdrop and resuming ETF inflows. a16z called the GENIUS Act the institutional foundation for the onchain transition, and Florida’s payment-stablecoin oversight rules take effect today. (prices via CoinGecko; flows via Farside)
Single-Stock News — Earnings Whispers
MU — bullish guide, margin dip. Fiscal Q1 revenue outlook well above consensus on AI/HBM demand; adjusted gross margin dips to 86.3% on broad bonuses; slipped ~1% after hours.
GOOGL — Gemini 4 Argon. Next frontier model for coding, enterprise work and cybersecurity; 1M-token context; DeepSWE v1.1 at 77.9%.
ORCL — Tencent’s $7B chip lease. Five-year deal for ~100,000 advanced AI chips unavailable in mainland China. (FT)
DELL — Japan’s $140B AI push. Data-center and power buildout with JERA; Apollo funding; 400MW in Chiba by 2028.
AMZN — Project Aurelian. Leaked plan targets 99.9% self-delivery by 2029. Separately, a multi-year Synopsys IP deal for custom chips.
TSLA — Europe rebound. September registrations up 61.9% in France, 38.4% in Sweden, 2.2% in Norway.
META — tax-credit scrutiny. The Guardian reports AI data centers were classified as potentially-failable “experiments” for R&D tax credits.
MRNA — Citi cuts to Sell. Downgraded from Neutral with an $80 price target.
BA — $20B Navy fighter win. F/A-XX carrier-based stealth fighter award over Northrop Grumman.
HOOD — weekend trading. Routing through Bruce Markets for weekend equities plus up to 10x crypto perpetuals.
AAPL — foldable iPhone outlook. Counterpoint sees ~6 million iPhone Duo foldables ($1,999) selling in 2026; Apple hit 33% China smartphone share. Smart-home event set for October 13.
BABA — Elite membership. AliExpress piloting a VIP membership for $800+/year shoppers, launching in Korea next month.
PSKY — $52B financing overhang. Warner Bros. deal financing faces surging interest costs as rates climb.
SKHY — Citi stays Buy. ₩3 million target kept; “a good time to buy memory” from October.
Earnings to watch: Accenture (BMO today), Nike (AMC today). Source: Earnings Whispers.
Single-Stock Movers
1-day winners and losers in the S&P 500. Data as of Wednesday, September 30, 2026. Source: Finviz. (Trefis has not published a September 30 update.)
Top Winners 1-Day Top Losers 1-Day HPE Hewlett Packard Enterprise +3.9% MRNA Moderna -5.3% INTC Intel +3.71% WMT Walmart -2.70% NOW ServiceNow +3.13% MRK Merck -2.66% PANW Palo Alto Networks +2.29% MS Morgan Stanley -2.43% CRM Salesforce +1.89% LLY Eli Lilly -2.33% LRCX Lam Research +1.44% MA Mastercard -2.15% AAPL Apple +1.10% ABT Abbott Laboratories -2.10% AMZN Amazon +1.00% UNH UnitedHealth -2.10% GOOGL Alphabet +0.93% PG Procter & Gamble -2.05% XOM Exxon Mobil +0.87% DHR Danaher -2.02% HPE’s 3.9% networking-driven rally led the winners, with Intel rebounding 3.71%. Moderna’s 5.3% plunge on Citi’s downgrade to Sell was in a league of its own among losers.
Calendar
Thursday, Oct 1 — Initial jobless claims (8:30 ET); ISM Manufacturing PMI (10:00 ET); S&P Global manufacturing PMI; construction spending; EIA natural gas inventories; Fed speakers Barkin, Schmid, Collins, Jefferson, Bowman and Cook. Earnings: Accenture (BMO), Nike (AMC).
Friday, Oct 2 — September jobs report: nonfarm payrolls, unemployment rate, and average hourly earnings (8:30 ET); factory orders. No major earnings — payrolls own the day.
Tuesday — OpenAI DevDay 2026.
Sources
Index closes, yields, commodities, sentiment: Naver Pay Securities, SKN Finance, TradingView and market data. Sector maps and single-stock movers: Finviz. Single-stock news and earnings calendar: Earnings Whispers. Crypto prices and flows: CoinGecko, Farside. Fear & Greed: CNN. Economic calendar: WSJ, Schwab Network. Data as of Thursday morning, October 1, 2026 (ET) unless noted.
Not financial advice. This briefing is for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any security.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — Oct 16: Warsh Cools Hike Bets, Dow Jumps, Tesla Roadster Flies [0] | Master | 10-16 | 0 |
| Morning Briefing — Oct 15: CPI Aftershock, Anthropic’s $16.8B Quarter, TSMC Record [0] | Master | 10-15 | 0 |
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.