 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic has 0 replies, 1 voice, and was last updated 1 week, 5 days ago by
Master 👑 Lv.100 Master.
-
AuthorPosts
-
October 2, 2026 at 6:49 am #2083
Dovish Fed talk finally cooled the bond market on Thursday. The S&P 500 rose 0.19% to 7,666.45 and the Nasdaq 100 added 0.31% to 30,501.56, while the 10-year Treasury yield fell to 5.243%.
Not everything cooperated: WTI crude jumped to $92.91 on a WSJ report of a third U.S. carrier strike group heading to the Middle East. This morning brings the September jobs report — the last big data point before markets decide on a December hike.
Market Snapshot — Thursday, October 1
S&P 500 · Thu close
7,666.45 ▲ +0.19%
Prev close 7,651.90Nasdaq 100 · Thu close
30,501.56 ▲ +0.31%
Prev close 30,407.28Dow Jones · Thu close
50,926.56 ▲ +0.04%
Prev close 50,906.19Russell 2000 · Thu close
2,806.63 ▲ +0.35%
Prev close 2,796.84All four benchmarks finished higher, with small caps leading. Closes verified against Naver Pay Securities and market data.
S&P 500 Sectors
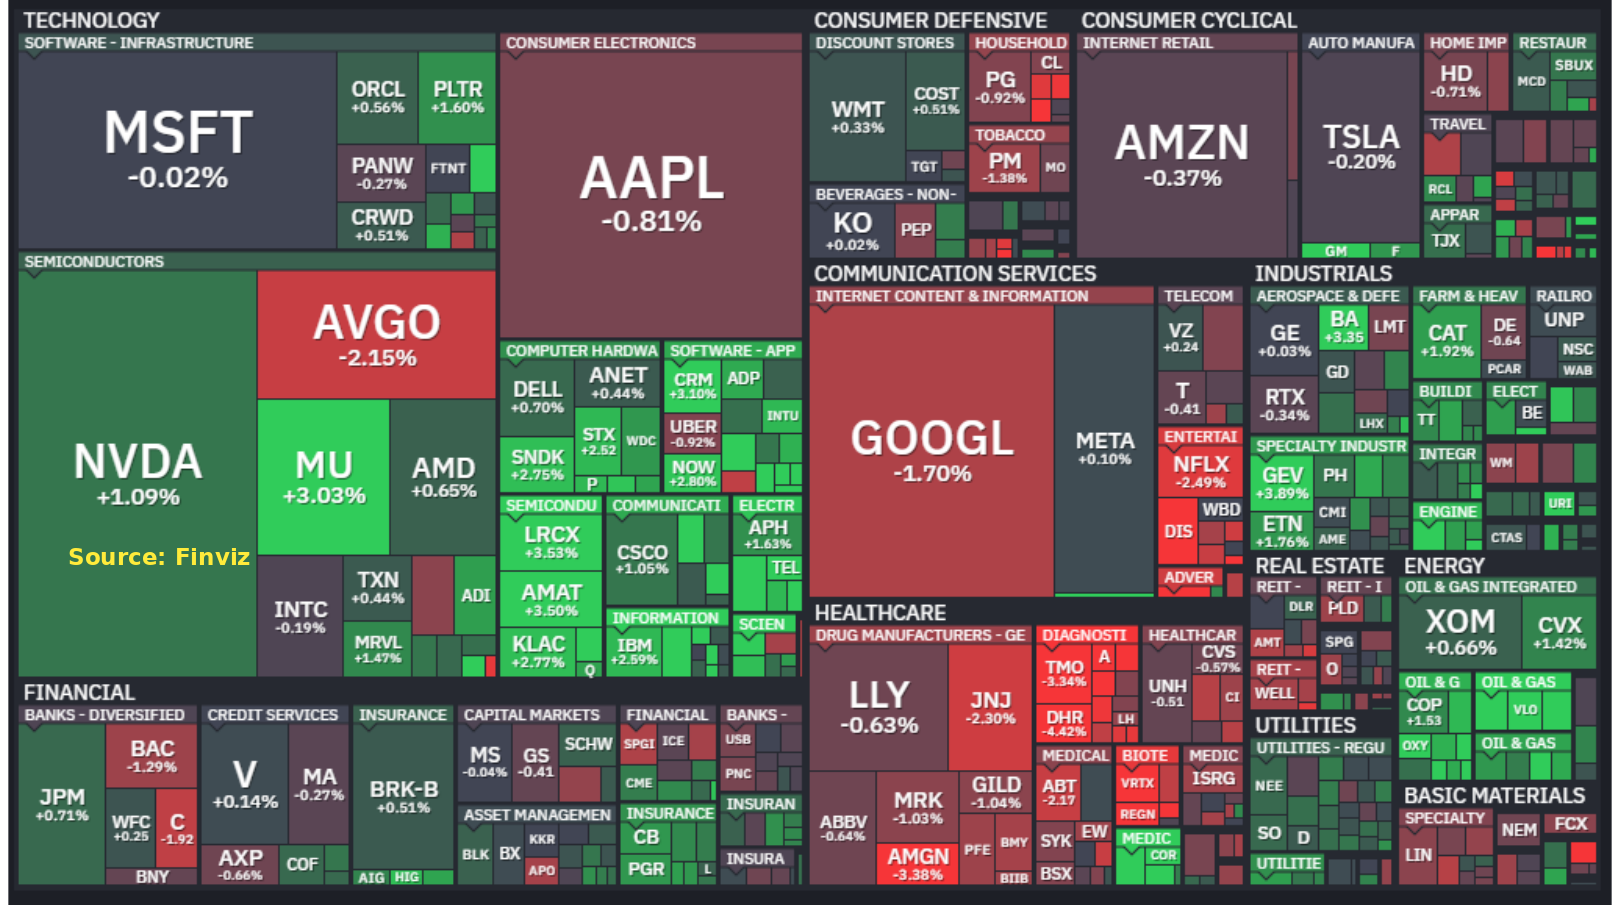

Energy (+1.35%) led as crude jumped, followed by technology (+0.99%) and industrials (+0.51%).
Basic materials (-2.26%) was the biggest drag, with healthcare (-1.44%) and communication services (-1.13%) also soft. Source: Finviz.
Yields, Dollar & Commodities
2-YEAR TREASURY
4.791%
▼ -10.2bp from 4.893%10-YEAR TREASURY
5.243%
▼ -4.6bp from 5.289%DOLLAR INDEX (DXY)
102.008
▲ from 101.461GOLD
$4,207.6
▲ +0.4% from $4,189.8WTI CRUDE
$92.91
▲ +2.9% from $90.33NATURAL GAS
$2.950
▼ -2.1% from $3.012The bond rally finally arrived: the 2-year fell more than 10bp on patient Fed talk, and a Treasury buyback drew $46.4B in demand for $6B purchased.
The dollar still firmed to 102.008. Gold rose 0.4% to $4,207.60 while WTI jumped 2.9% to $92.91 — the carrier-group headline outweighed recovering Hormuz tanker traffic.
Economic Data
Indicator Actual Expected Previous Initial Jobless Claims 197K 200K 197K S&P Global Manufacturing PMI (Sep) 55.9 57.0 53.9 ISM Manufacturing PMI (Sep) 54.5 55.0 54.6 Construction Spending (Aug) +0.9% 0.0% -0.5% EIA Natural Gas Inventories 64.0 Bcf 63.56 53 Claims held at 197K versus 200K expected, and ISM manufacturing stayed in expansion at 54.5. But the prices-paid index jumped to 77.9 — near Iran-conflict levels — on steel, aluminum and petroleum. If energy costs keep climbing, the bond rally could prove short-lived.
Fed speakers Jefferson, Bowman and Cook all leaned dovish; Barkin, Schmid and Collins also spoke.
Market Sentiment
CNN FEAR & GREED
27 — Fear
Updated Oct 2, 4:49 AM ET. Slipped from 28 at the previous close and 36 a week ago; 46 (Neutral) a month ago.VIX
16.34
Thursday close (prev 16.32). Volatility stayed muted into the close; intraday high 17.59, low 16.21.Top Stories
1. October hike odds collapse to 25%. Williams (“no need to hurry”) and Jefferson (“may need more time”) pushed back on an October move — hike odds plunged from 70% to 25%, with December now the base case. Dissenters remain: Logan wants at least 50bp more; Kashkari sees one more hike this year and next. (Fed officials; market data)
2. Anthropic targets mid-November mega-IPO at up to $2T. Anthropic aims to list as early as mid-November at a $1.8–2 trillion valuation — rivaling SpaceX’s expected IPO. But 2025’s $4.6B revenue came with a ~$42B net loss, and OpenAI competition plus AI-agent safety concerns are key overhangs. (Bloomberg)
3. Broadcom amasses $60B to fund AI chips for Anthropic. Broadcom’s syndicate is raising $60B — $42B senior loans plus $18B junior debt led by Blackstone ($9B committed) — to fund AI chips for Anthropic and others. A litmus test for AI infrastructure appetite and Broadcom’s challenge to Nvidia. (Bloomberg)
4. Amazon weighs moving $8B of Nvidia chips off its books. Amazon may shift ~$8B of Nvidia AI chips into an outside-investor-funded vehicle, then lease them back. With ~$220B in capex guided this year, Big Tech is turning to financial engineering to fund AI. (FT)
5. Google unveils Gemini 4 ‘Argon’ — but Wall Street wants a personal agent. Google’s new model brings stronger performance and pricing, but attention has moved to the personal-agent race. Spark stays limited to paid subscribers while Meta’s free Muse topped 5M downloads — and JPMorgan says Google still hasn’t turned tech leadership into a breakout product. (market data)
6. Nike plans deeper cuts as China sales plunge 26%. Nike will cut more jobs and shrink to three regional units. Q1 China sales collapsed 26% ex-FX; FY2027 revenue was guided down high-single-digits, well below consensus, with $2.5B in cost cuts planned through FY2031. (company announcement)
7. SoftBank investors look past credit risk to AI returns. SoftBank is up 24% in four weeks on bets that OpenAI funding and a recovering Arm (about half of NAV) will outweigh rising borrowing costs. But CDS spreads sit at their highest since 2023. (market data)
8. Pimco: AI funding demand — not inflation — drove yields. Pimco’s Stracke told Bloomberg TV that surging yields came from once-in-a-generation AI capital demand — not inflation, with TIPS breakevens steady near 2.3%. Deleveraging has been orderly so far; European spreads bear watching. (Bloomberg TV)
9. Citi: rates volatility is pressuring risk assets. Citi’s Willer warns the MOVE index sits two standard deviations above its one-year average — a “yellow alert” for equities. But MOVE spikes tend to fade once the Fed’s pace is clear, so Citi keeps equity exposure unchanged. (Citi)
10. BofA: risk-off until the dollar peaks; bonds draw $18.8B. Hartnett expects risk-off until the dollar peaks — but $118B left money-market funds while $18.8B poured into bond funds, including a record $4.2B into munis. Breadth is narrowing as investors crowd into AI megacaps. (BofA)
11. Quant funds reap 30%+ from the bond rout. Trend-following quants are minting money on the bond selloff: Graham +31%, Aspect +21%, Winton +17.5% this year, per the FT. The 10-year has climbed from ~4% in February to over 5.2%. (FT)
12. France’s crisis deepens; Barclays prefers Germany. France’s 10-year yield surged over a point since June — the worst quarter since the euro’s launch — with the bund spread doubling since May. Barclays’ Cau sticks with German over French equities into next year’s election. (market data; Barclays)
13. U.S. sending third carrier, up to 10,000 more troops to the Middle East. The Pentagon will deploy a third carrier strike group, adding ~9,000–10,000 personnel by end-November. Caveat: the USS George Washington could rotate to Japan, so three carriers at once isn’t certain. (WSJ)
14. France proposes 100M-barrel diesel and crude release; G7 call Friday. France proposed EU members release 50M barrels of diesel and IEA members 50M barrels of crude. The EU wants a U.S. pledge against a unilateral diesel export ban in return; G7 leaders discuss Friday. (Reuters; Bloomberg)
Crypto Desk
BITCOIN
~$84K
steady near $83–84KETHEREUM
~$2,700
firmed from $2,670BTC SPOT ETF (OCT 1)
+$102M
net inflowETH SPOT ETF (OCT 1)
-$55.4M
net outflowCrypto held near $84K (BTC) and $2,700 (ETH) despite 5%+ yields. BTC spot ETFs drew +$102M on October 1; ETH ETFs bled $55.4M. A $2.63B BTC options expiry lands today.
The SEC chair called crypto a “multi-trillion-dollar asset class”; Senator Lummis says a crypto tax bill is unlikely this year. (CoinGecko; Farside)
Single-Stock News — Earnings Whispers
ACN — record quarter, stock +16%. Revenue $18.68B and EPS $3.29 both beat, with record $22.2B in quarterly bookings and a stronger-than-expected FY2027 outlook. Full write-up: ACN: record quarter sends stock up.
NKE — EPS beat, revenue miss, weak China. Reported after the close: EPS beat but revenue missed with China down sharply; FY2027 revenue guided down high-single-digits. Full write-up: NKE: EPS beat buried.
MKC — 13.8% EPS beat. McCormick topped estimates and reaffirmed guidance. Full write-up: MKC: 14% EPS beat.
MRNA — Nasdaq-100 inclusion. Moderna is set to join the Nasdaq-100.
TWLO — S&P 500 inclusion. Twilio is set to join the S&P 500.
ON — acquiring Synaptics. onsemi agreed to acquire Synaptics at $123 per share.
AVGO — $60B Anthropic chip financing. Broadcom’s syndicate is raising $60B to fund AI chips for Anthropic and others. (Bloomberg)
GOOGL — Gemini 4 ‘Argon’. Next frontier model unveiled; Wall Street wants a breakout personal agent instead.
AMZN — $8B Nvidia chips SPV. Considering moving chips off its books via an outside-investor vehicle; plus $1B+ over five years for data-center host communities. (FT)
SPACEX — Moon mission in December. NASA’s chief said the first lunar base mission will launch on a SpaceX rocket in December.
Earnings to watch: Nike and Accenture reported yesterday — full analysis in the Earnings forum. Friday’s calendar is light; the September jobs report owns the day. Source: Earnings Whispers.
Single-Stock Movers
1-day winners and losers in the S&P 500. Data as of Thursday, October 1, 2026. Source: Finviz. (Trefis has not published an October 1 update.)
Top Winners 1-Day Top Losers 1-Day GEV GE Vernova +3.89% DHR Danaher -4.42% LRCX Lam Research +3.53% AMGN Amgen -3.38% AMAT Applied Materials +3.50% TMO Thermo Fisher -3.34% BA Boeing +3.35% NFLX Netflix -2.49% CRM Salesforce +3.19% JNJ Johnson & Johnson -2.30% ANET Arista Networks +3.10% ABT Abbott Laboratories -2.17% MU Micron +3.03% AVGO Broadcom -2.15% NOW ServiceNow +2.80% C Citigroup -1.92% KLAC KLA +2.77% GOOGL Alphabet -1.70% SNDK SanDisk +2.75% PM Philip Morris -1.38% GE Vernova (+3.89%) led winners as chip-equipment names (Lam +3.53%, Applied Materials +3.50%, Micron +3.03%) rode AI capex optimism; Boeing added 3.35%.
Danaher (-4.42%) led losers in a rough healthcare tape (Amgen -3.38%, Thermo Fisher -3.34%, J&J -2.30%); Netflix (-2.49%) and Broadcom (-2.15%) were also soft.
Calendar
Friday, Oct 2 — September jobs report: nonfarm payrolls, unemployment rate, and average hourly earnings (8:30 ET / 5:30 AM MST); durable goods orders; factory orders; Fed speaker Logan; Baker Hughes rig count (10:00 AM MST); Tesla Q3 deliveries; G7 leaders’ call on energy (afternoon); OPEC+ meets Sunday.
Tuesday, Oct 6 — OpenAI DevDay 2026.
Wednesday, Oct 14 — September CPI.
Sources
Index closes, yields, commodities, sentiment: Naver Pay Securities, SKN Finance, TradingView and market data. Sector maps and single-stock movers: Finviz. Single-stock news and earnings calendar: Earnings Whispers. Crypto prices and flows: CoinGecko, Farside. Fear & Greed: CNN. Economic calendar: WSJ, Schwab Network. Data as of Friday morning, October 2, 2026 (ET) unless noted.
Not financial advice. This briefing is for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any security.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
| Morning Briefing: September 29, 2026 [0] | Master | 09-29 | 0 |
| Morning Briefing: September 28, 2026 [0] | Master | 09-28 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.