 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
October 13, 2026 at 6:16 am #2296
China’s memory makers just crashed the chip party. CXMT claims a DRAM breakthrough that leapfrogs Samsung and SK Hynix — Seoul’s market is down 5% this morning, and US chip stocks are bleeding into the open.
Today is the week’s first real test: JPMorgan, Goldman Sachs, Citigroup, Wells Fargo, UnitedHealth, and J&J all report before the bell. Then CPI lands tomorrow.
Index Snapshot
Index Close Change S&P 500 7,807.24 -0.06% Dow Jones 51,850.55 +0.38% Nasdaq 100 30,664.70 -0.71% Russell 2000 2,794.48 -0.45% Monday was rotation, not panic: energy (+1.31%) and defensive sectors rose while technology (-1.17%) sank on the memory selloff. Bond markets were closed for Columbus Day.
Market Heatmap & Sector Bars
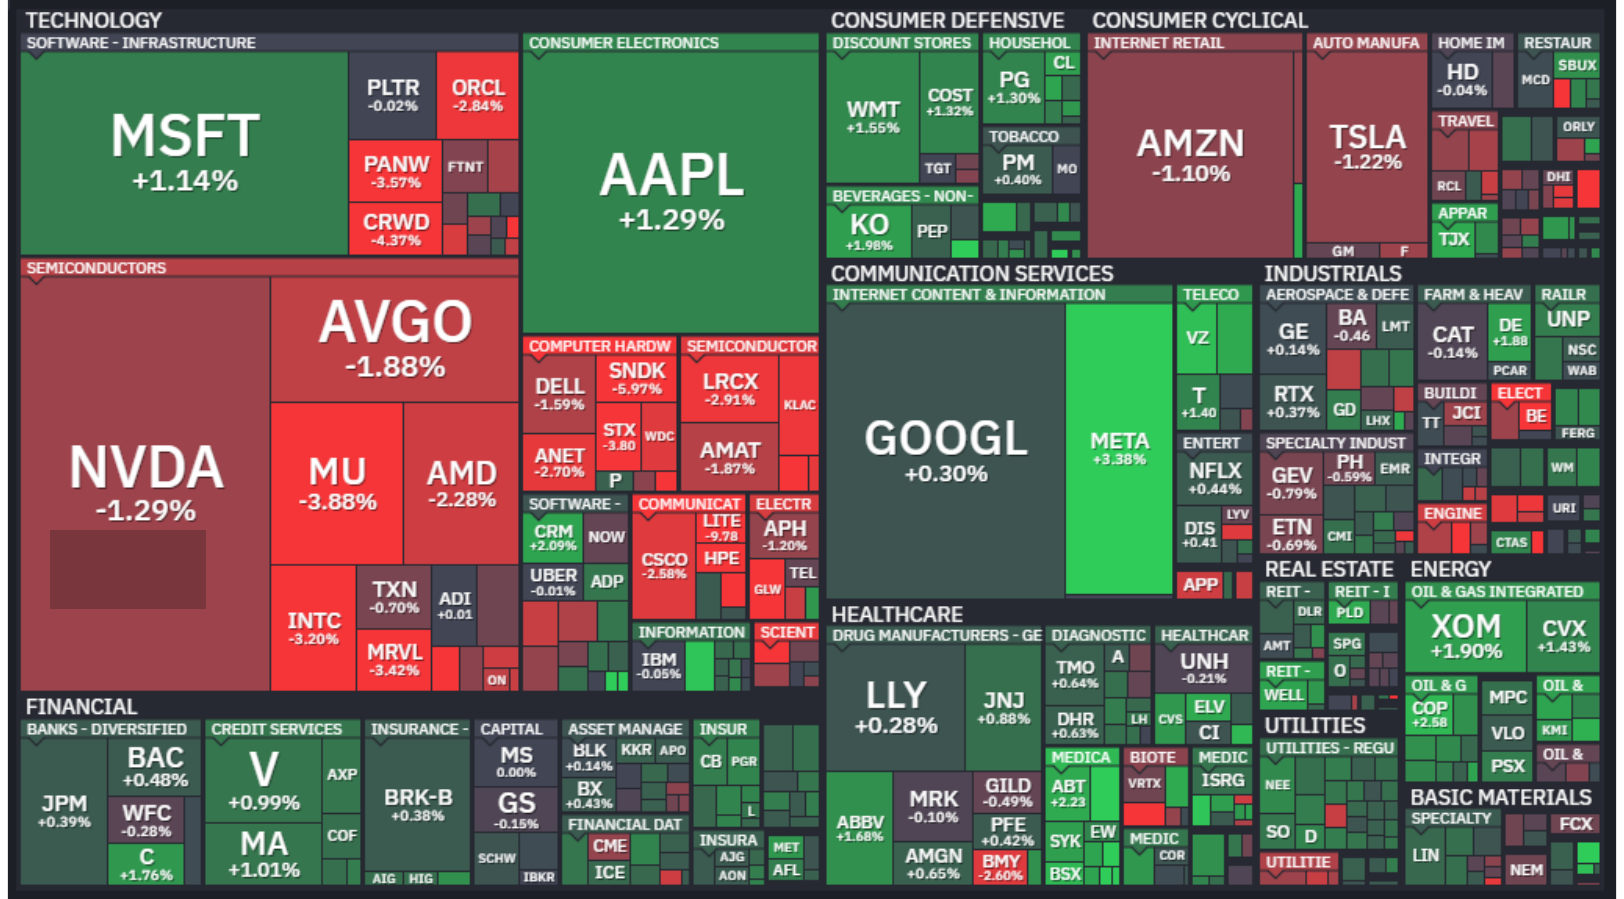

Memory was the epicenter: SanDisk (-6.0%), Micron (-3.9%), Marvell (-3.4%), Intel (-3.2%). Meta (+3.4%) and Apple (+1.3%) bucked the tech selloff; Exxon (+1.9%) and Chevron (+1.4%) rode crude higher.
Yields, Dollar & Commodities
Asset Level Move 10-year Treasury 5.242% Unchanged (market closed) 2-year Treasury 4.791% Unchanged (market closed) Dollar index 102.577 +0.35 Gold $4,195.9/oz -0.6% WTI crude $93.16 +1.6% Natural gas $3.176 -0.9% Bitcoin ~$84,000 Steady Bond markets reopen today after the holiday — the 10-year ended Friday at 5.242%, and IMF warnings of a “disorderly” yield spike will be ringing in traders’ ears. WTI pushed further above $93 overnight on the Houthi escalation.
Economic Data
Release Actual Expected Fed’s Hammack (hawk, voter) Spoke Monday — inflation “still too high,” more hikes on the table Light on data, heavy on earnings. The macro calendar ignites tomorrow with September CPI, then PPI Thursday.
Market Sentiment
Fund managers are bullish but fully invested — a dangerous combination. BofA’s October survey shows cash at just 3.9%, tech overweight at the highest since August 2020, and “long semiconductors” the most crowded trade on earth. The top tail risk: a disorderly spike in bond yields (31%), ahead of an AI bubble (23%). When everyone’s in the same trade, the exit gets narrow.
Top Stories
CXMT’s 4F² claim rattles the memory trade (Bloomberg). China’s ChangXin Memory says it cracked the 4F² DRAM cell design — packing more memory per chip via vertical transistors — and will ship a DDR5 server product before year-end. Samsung and SK Hynix have chased the same design for years; Samsung isn’t targeting mass production until 2028. Bloomberg calls the claim “unsubstantiated,” and Morningstar warns of a long gap between unveiling and viable yields. The market isn’t waiting: Samsung -7.7%, SK Hynix -8.8%, Kospi -5% this morning. Micron fell 4% Monday; SanDisk lost 6%.
Bank earnings day. JPMorgan, Goldman Sachs, Citigroup, and Wells Fargo report before the open — the first read on credit quality, trading revenue, and loan growth in a 5.24% world. UnitedHealth and J&J also report. With financials up Monday ahead of the numbers, expectations are elevated.
BofA: everyone’s bullish, nobody has cash (MarketWatch, Reuters). The October fund manager survey found cash at 3.9%, the biggest tech overweight since August 2020, and long-semiconductor as the #1 crowded trade. Investors cut banks by the most since March 2023 while piling into bonds and utilities. Contrarian takeaway: positioning is stretched long into this week’s CPI.
IMF warns of “disorderly” bond spike. The Fund’s financial stability report flags surging government debt, inflation pressure, massive AI-company borrowing, and leveraged hedge-fund bond bets as a combustible mix for yields.
Musk becomes the midterms’ biggest donor. Elon Musk has given $276 million to Republican groups since July — already more than his 2024 presidential-cycle total — with $158M to the Senate Leadership Fund.
Waller: yields are doing the Fed’s job. Governor Christopher Waller said surging long-term rates are cooling housing and autos on their own — an “unintended” substitute for Fed tightening. December hike odds sit near 88%.
Options frenzy nears 2021 mania levels. Single-stock options now trade ~$700 billion in daily notional — close to the meme-stock peak — with half in contracts expiring within two weeks. Retail risk appetite is fully back.
Citi: small-cap shorts near 3-year extremes. Russell 2000 futures positioning keeps deteriorating even as Nasdaq futures stay positive — a setup that has preceded violent short squeezes before.
Zuckerberg: Meta has reached the AI “frontier” (FT). The CEO told the FT that Meta’s new Muse Wonder model matches OpenAI and Anthropic on some benchmarks, and that Meta is now a paid AI contender — shares rose 3.4% Monday.
Nvidia’s China share collapses to 34% (IDC). US export controls and Beijing’s buy-local push cut Nvidia’s China AI-chip shipments 44% year-over-year to 678,000 units in H1; Huawei shipped 572,000 for a 28% share. The FT reports Chinese tech giants bought 1M+ unrestricted Nvidia gaming/workstation chips to fill the gap.
Visa wins China payments approval. After applying in 2017, Visa got PBOC preliminary approval to prepare a domestic bank-card clearing business — a market-opening win tied to Trump–Xi trade talks.
Lithium drops 10% on EU–China hybrid deal. Guangzhou lithium futures fell to ¥104,740 as the 350,000-unit annual cap on Chinese hybrid exports to Europe clouded demand; Pilbara fell 11%.
ASML earnings this week — guidance is everything. With the chip trade fragile, investors want EUV capacity-expansion plans: Low-NA output rising from 65 to 85 units annually, toward 110 by 2028. TSMC reports Thursday.
Anthropic warns AI could soon self-replicate. The lab says small models may soon spread via IoT vulnerabilities without human help or data centers — while US and EU banking regulators ramp up AI scrutiny over stability fears (Reuters).
BOJ leans against October hike. Bloomberg sources say the Bank of Japan won’t hike back-to-back but keeps December open.
Crypto Desk
Quiet tape: Bitcoin near $84,000, ether under its 50-day average. Spot ETFs saw outflows Monday — $85.4M from ETH funds, $65.4M from BTC funds. TD Cowen says CFTC crypto rules could slip to early 2028.
Single-Stock Movers
Stock Move Driver Meta (META) +3.38% “Frontier” AI claim Apple (AAPL) +1.29% Defensive tech bid Microsoft (MSFT) +1.14% Software resilience Exxon (XOM) +1.90% Crude above $93 SanDisk (SNDK) -5.97% CXMT fears CrowdStrike (CRWD) -4.37% Software selloff Micron (MU) -3.88% CXMT fears Palo Alto (PANW) -3.57% Software selloff Marvell (MRVL) -3.42% Chip weakness Intel (INTC) -3.20% Chip weakness Lam Research (LRCX) -2.91% Equipment fears Oracle (ORCL) -2.84% AI valuation reset Calendar — Tuesday, October 13
- Pre-market earnings: JPMorgan, Goldman Sachs, Citigroup, Wells Fargo, UnitedHealth, Johnson & Johnson
- Wednesday: September CPI — the week’s main event
- Thursday: September PPI; TSMC earnings
- This week: ASML earnings — EUV guidance in focus
Sources
- Bloomberg (via Moneyweb) — China’s CXMT claims memory breakthrough ahead of Samsung, Hynix: moneyweb.co.za
- MarketWatch — Fund managers retain surprising optimism: marketwatch.com
- Reuters (via BOE Report) — 10-year yield at 5.9% would spark shift to bonds: boereport.com
- Investopedia — Markets news, Oct. 12, 2026: investopedia.com
- Finviz — S&P 500 heatmap and sector performance, October 12, 2026: finviz.com
Not financial advice. Do your own research.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — Oct 16: Warsh Cools Hike Bets, Dow Jumps, Tesla Roadster Flies [0] | Master | 10-16 | 0 |
| Morning Briefing — Oct 15: CPI Aftershock, Anthropic’s $16.8B Quarter, TSMC Record [0] | Master | 10-15 | 0 |
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.