 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic has 0 replies, 1 voice, and was last updated 1 week ago by
Master 👑 Lv.100 Master.
-
AuthorPosts
-
October 8, 2026 at 6:09 am #2174
Good morning. Futures are sliding as oil surges and bond yields climb back toward multi-decade highs. Yesterday’s session was quiet on the surface — the S&P 500 slipped 0.22% — but the drivers building this morning are anything but quiet.
The White House has asked the Pentagon for Iran strike options ahead of the midterms. Brent crude is near $105. And Samsung just posted the largest quarterly profit in tech history — and its stock fell anyway.
Market Snapshot
Index Oct 7 Close Change Futures (premarket) S&P 500 7,801.77 -0.22% -0.4% to -0.6% Dow Jones 51,179.87 -0.66% -0.8% to -1.0% Nasdaq 100 31,160.08 -0.21% -0.7% Russell 2000 2,793.20 -1.31% — Futures data as of ~6:00 a.m. ET, October 8, 2026 (Reuters, Barron’s).
Heat Map & Sector Performance
Wednesday’s tape told a clear story: defensives held up, rate-sensitive sectors got hit, and healthcare quietly led.
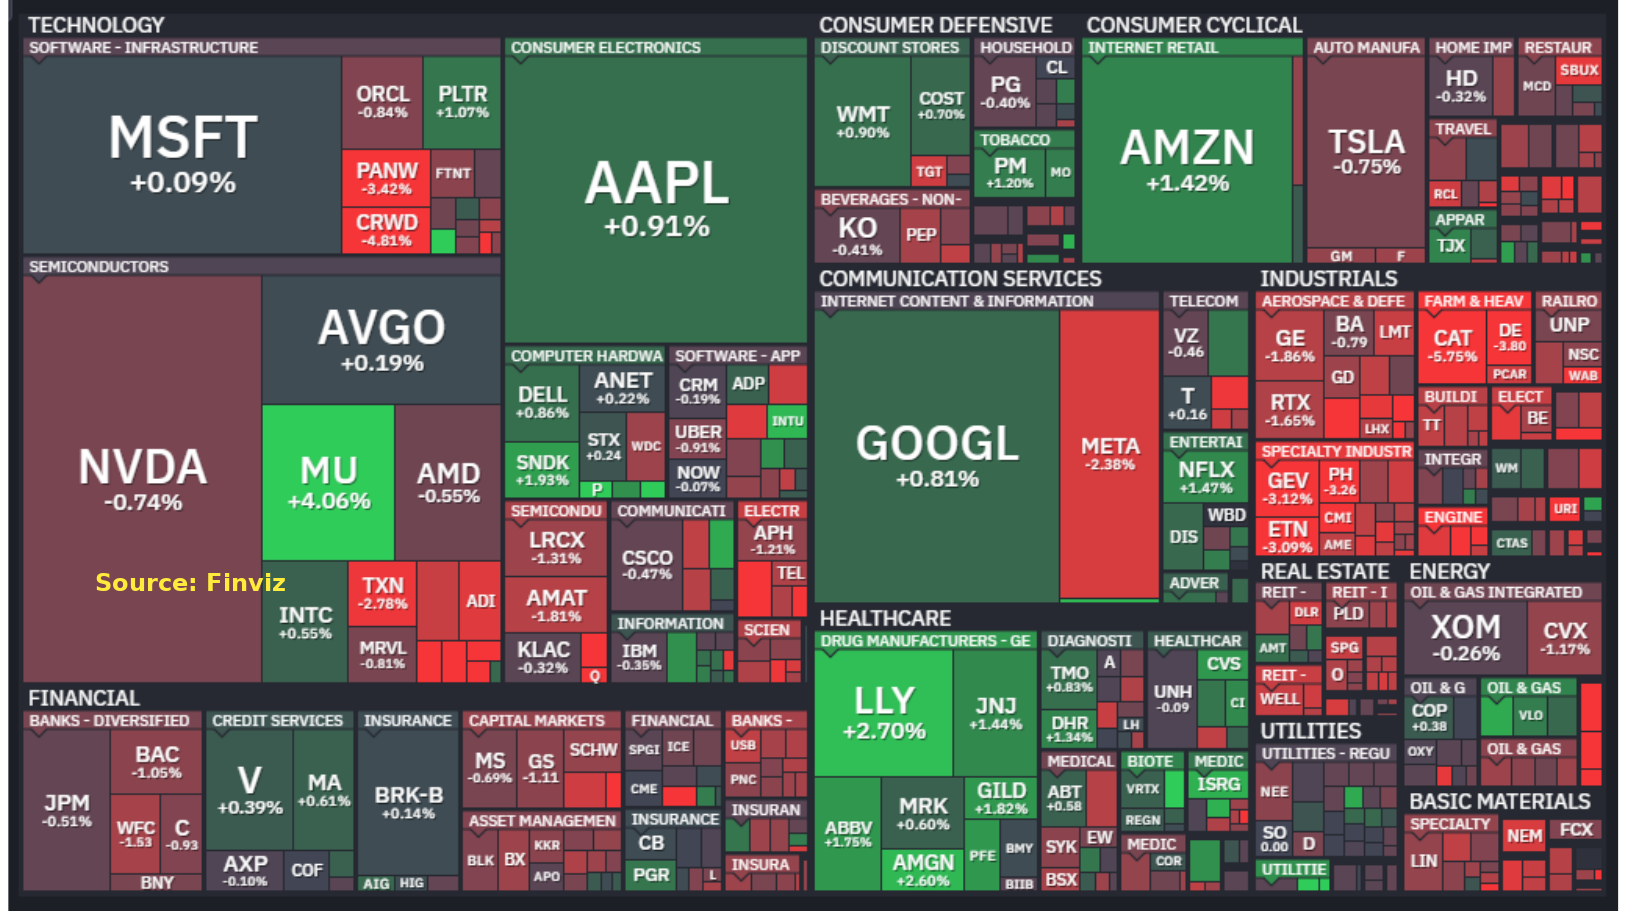
Sector returns, October 7 (Finviz):
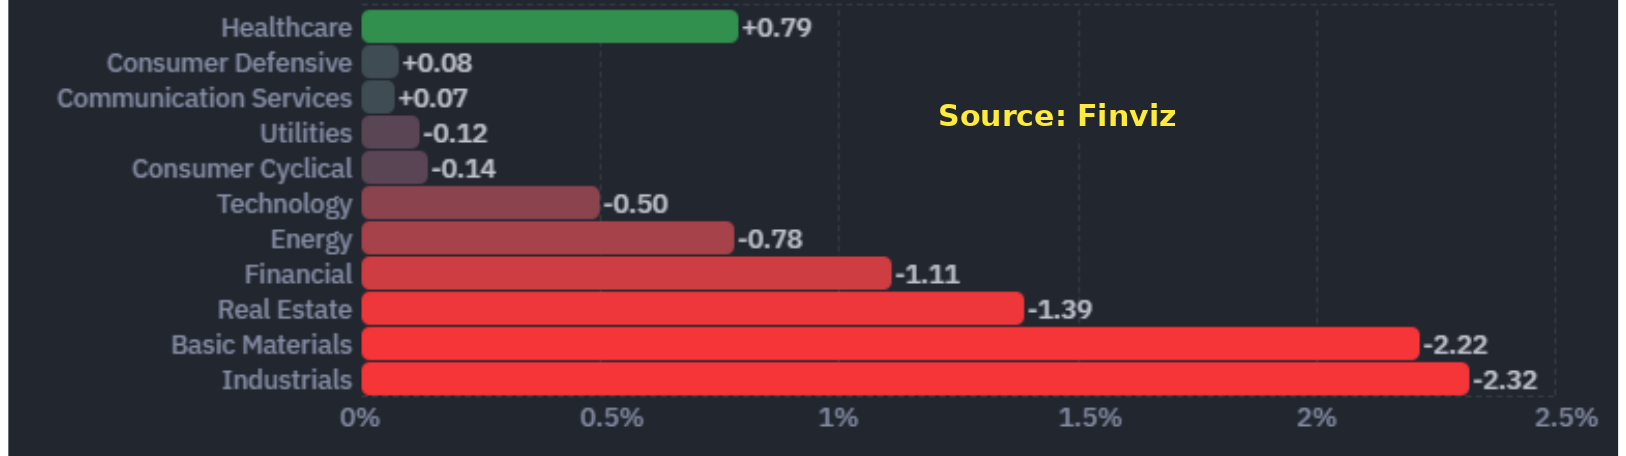
Sector Oct 7 Healthcare +0.79% Consumer Defensive +0.08% Communication Services +0.07% Utilities -0.12% Consumer Cyclical -0.14% Technology -0.50% Energy -0.78% Financial -1.11% Real Estate -1.39% Basic Materials -2.22% Industrials -2.32% Yields, Dollar & Commodities
Asset Level Move 10-year Treasury ~5.33% Higher (premarket) 30-year Treasury ~5.70% Higher 2-year Treasury 4.77% Lower (Oct 7) Dollar Index 102.28 Higher (Oct 7) Gold ~$4,136/oz Flat to higher (premarket) Brent crude ~$104.60 +4.4% (premarket) WTI crude ~$92.20 +4%+ (premarket) Natural gas $3.22 Higher (Oct 7) Bitcoin ~$82,400 -1% (premarket) The 10-year briefly touched 5.365% on Wednesday — its highest since 2002 — before a strong auction (5.300% vs. 5.317% when-issued) pulled it back. This morning it’s climbing again on the oil spike.
Economic Data
- Jobless claims — 8:30 a.m. ET today. Consensus ~200K; last week 197K.
- 30-year bond auction — 1:00 p.m. ET. Yesterday’s 10-year auction stopped through; the market will watch for a repeat.
- NY Fed 1-year inflation expectations — 3.90%, the highest since May 2023. Released Wednesday.
- EIA crude inventories — fell 3.19M barrels vs. a build of 1.72M expected.
Market Sentiment
The VIX sits near 15 — well below its long-run average — even as oil, yields, and geopolitical risk all climb. Hedging costs are near two-year lows, and Wall Street is calling it a rare window to add protection. Breadth is narrowing fast: money is crowded into AI and megacap tech while everything else gets sold. Bank of America notes that kind of concentration is a classic late-cycle signature.
Top Stories
Trump says he’s “not keen” on an Iran deal as strike options circulate. The president told a rally he doesn’t want an agreement with Tehran. The Atlantic reports the White House asked the Pentagon to prepare Iran strike options ahead of next month’s midterms. Axios adds that planning includes potential large-scale strikes on energy, infrastructure, and nuclear sites.
Oil surges on the escalation risk. Brent briefly topped $105 a barrel (+4.4%), WTI rose above $92. A tanker was struck off Qatar, freight rates hit a record $1.4M per day on the Middle East–China route, and Hurricane Isaias shut in 510K barrels per day of Gulf production. (Reuters, WSJ)
Samsung posts the biggest quarterly profit in tech history — and the stock falls. Samsung guided to Q3 operating profit of 107.4 trillion won (~$80.2 billion), roughly nine times last year’s 12.17 trillion, on record memory prices. It beat the LSEG SmartEstimate of 106.1T. Shares still fell 2.4% in Seoul as investors questioned how long the AI memory supercycle can last. The chill spread: Nvidia -0.6%, Broadcom -1.4%, Micron -1.2% premarket. (Reuters, WSJ)
TSMC’s Q3 revenue jumps 51% — and that fell flat too. Revenue of NT$1.49 trillion beat estimates, with September sales up 54.6%. TSMC shares still fell nearly 2% premarket. When record numbers can’t lift stocks, expectations are the problem, not the results. (IBD)
Tech giants are lining up mega-debt for AI chips. The WSJ reports Broadcom is arranging $50 billion+ in financing for its OpenAI co-developed AI chips, with Oracle also seeking funding and SpaceX discussing $40 billion for Nvidia chips. The market’s fear: a flood of tech debt competing for capital as yields sit at 24-year highs. (WSJ, Reuters)
Panmure Liberum calls for a 36% crash. Strategist Joachim Klement — among the first to call the bull market’s end — sees the AI bubble bursting in 2027–28, with the S&P 500 falling to 5,000 by end-2027 and the Stoxx 600 to 430. His advice isn’t to sell now, but to build a contingency plan — and rotate to defensives if the S&P breaks its 200-day moving average. (Bloomberg)
Waller: more hikes likely, but the pace is flexible. Fed Governor Christopher Waller said additional rate increases will probably be needed to reach 2% inflation, though not necessarily at consecutive meetings. Futures markets are leaning toward December for the next move. (Reuters)
France’s debt now looks riskier than its blue chips. About 38% of French corporate bonds — L’Oréal, TotalEnergies — now trade at lower yields than French government bonds, as deficit misses and political gridlock erode faith in OATs. (Bloomberg)
Crypto Desk
- Bitcoin ~$82,400, down ~1% premarket and well below this week’s $87K highs.
- Spot ETF flows: Bitcoin ETFs saw ~$484M in net outflows; Ethereum ETFs ~$160M out.
- Coinbase is expanding services for traditional financial institutions.
- Tron: Justin Sun says a stock token launches in Q4.
Single-Stock News — Earnings Whispers
PepsiCo (PEP) reported before the open: adjusted EPS of $2.34 on revenue of $25.27 billion (+5.6%), both ahead of estimates. But it cut full-year EPS growth guidance to 2.5–3.5% from 5–7%, blaming North American pressure. Shares rose ~1–2% premarket; the stock is down ~28% from its 52-week high. (Barron’s, WSJ)
Delta (DAL) reports before the open tomorrow — the first major airline read on fall travel demand.
Single-Stock Movers (premarket)
Ticker Move Driver PEP +1–2% Q3 beat, guidance cut TSM -2% Record Q3 sales met with selling NVDA -0.6% Samsung/TSMC chill AVGO -1.4% WSJ $50B financing report MU -1.2% Memory euphoria fading Movers via Reuters, Barron’s, IBD premarket coverage.
Calendar — Today & Tomorrow
- Today 8:30 a.m. ET — Jobless claims
- Today 1:00 p.m. ET — 30-year Treasury auction
- Today — PepsiCo earnings (reported); Microsoft Windows/Surface event
- Tomorrow (pre-open) — Delta Air Lines (DAL) earnings
- Next week — Big bank earnings begin; Q3 earnings season in full swing
Sources
- Reuters — Wall Street futures, Samsung guidance, Waller comments: reuters.com
- WSJ — futures selloff, Broadcom/Oracle/SpaceX debt, PepsiCo: wsj.com
- Barron’s — premarket movers, bond yields: barrons.com
- Bloomberg via BusinessLine — Panmure Liberum crash call: thehindubusinessline.com
- Barron’s — PepsiCo earnings: barrons.com
- Investor’s Business Daily — market open preview: investors.com
- Samsung Newsroom — Q3 2026 guidance: news.samsung.com
- Finviz — heat map and sector performance, October 7, 2026
Not financial advice. Do your own research.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
| Morning Briefing: September 29, 2026 [0] | Master | 09-29 | 0 |
| Morning Briefing: September 28, 2026 [0] | Master | 09-28 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.