 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
September 30, 2026 at 6:41 am #1939
U.S. stocks slipped on Tuesday as weak consumer confidence and soft job openings data reinforced slowdown worries — the S&P 500 fell 0.17% to 7,670.84 while the Dow dropped 0.26% to 51,349.92. The Nasdaq 100 managed a 0.21% gain as the bond selloff paused: the 10-year yield eased to 5.234% after spiking to 5.29%. Gold bounced 1.6% to $4,215 while WTI crude plunged 4.7% to $88.94. Today is the week’s main event — August PCE, Q2 GDP and ADP employment land before the open, and Micron reports after the close.
Market Snapshot — Tuesday, September 29
S&P 500 · Tue close
7,670.84 ▼ -0.17%
Prev close 7,683.69
52-wk high 7,816.70
52-wk low 6,316.91Nasdaq Composite · Tue close
26,797.54 ▼ -0.09%
Prev close 26,820.38
52-wk high 27,288.79
52-wk low 20,690.25Dow Jones · Tue close
51,349.92 ▼ -0.26%
Prev close 51,481.51
52-wk high 54,744.33
52-wk low 45,057.28The Nasdaq 100 rose 0.21% to 30,339.33 while the Russell 2000 slipped 0.35% to 2,807.92. Closes verified against SKN Finance and market data.
S&P 500 Sectors
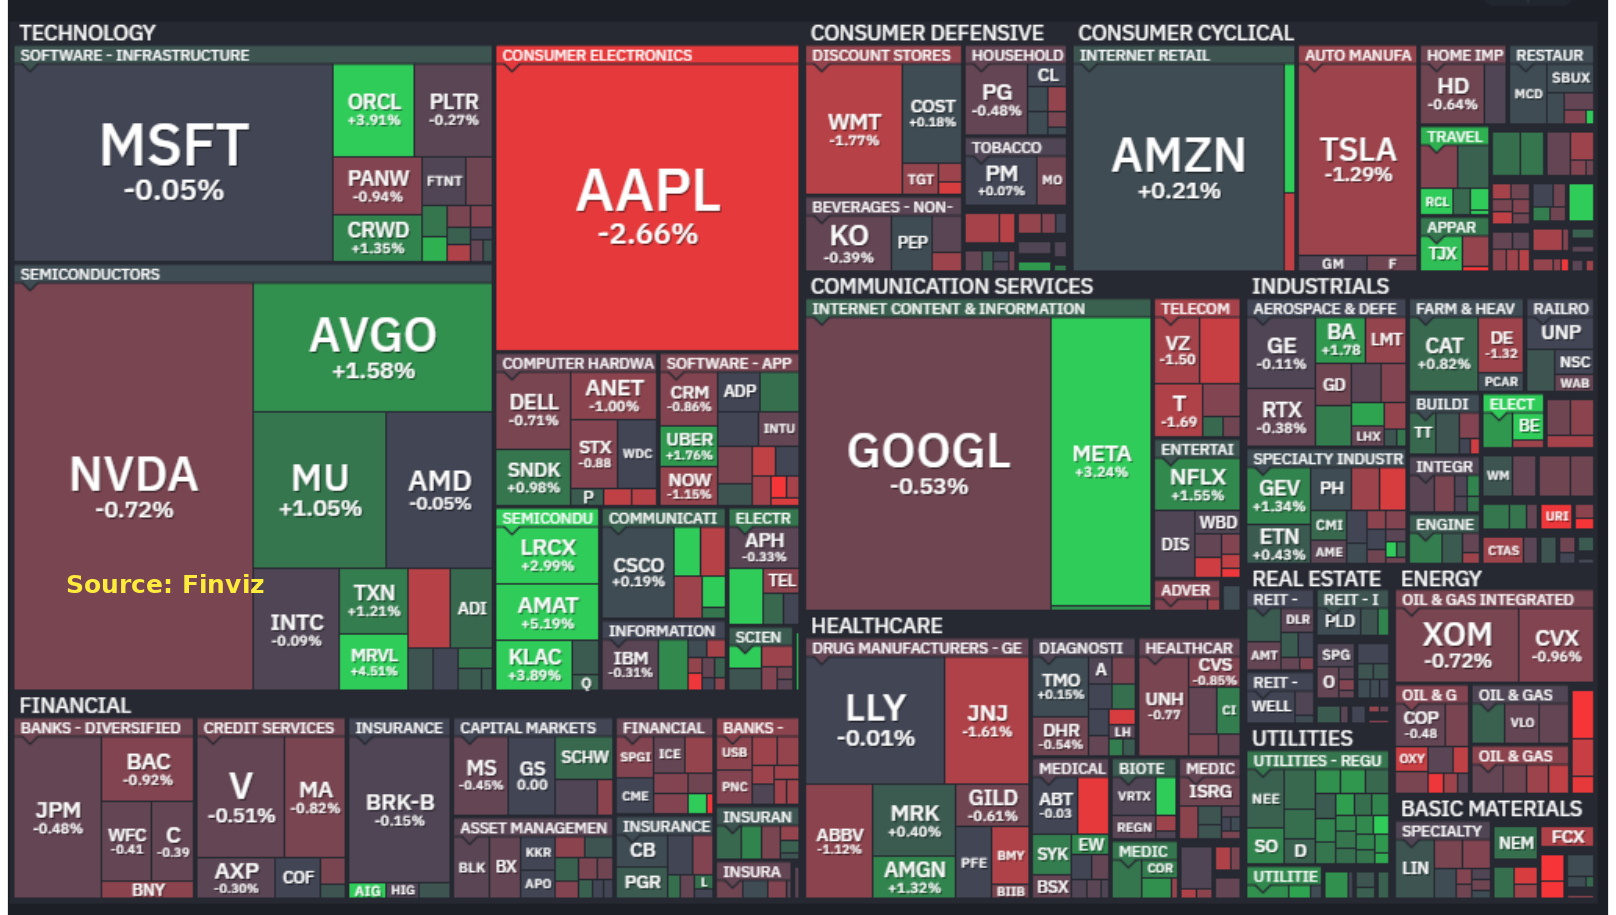
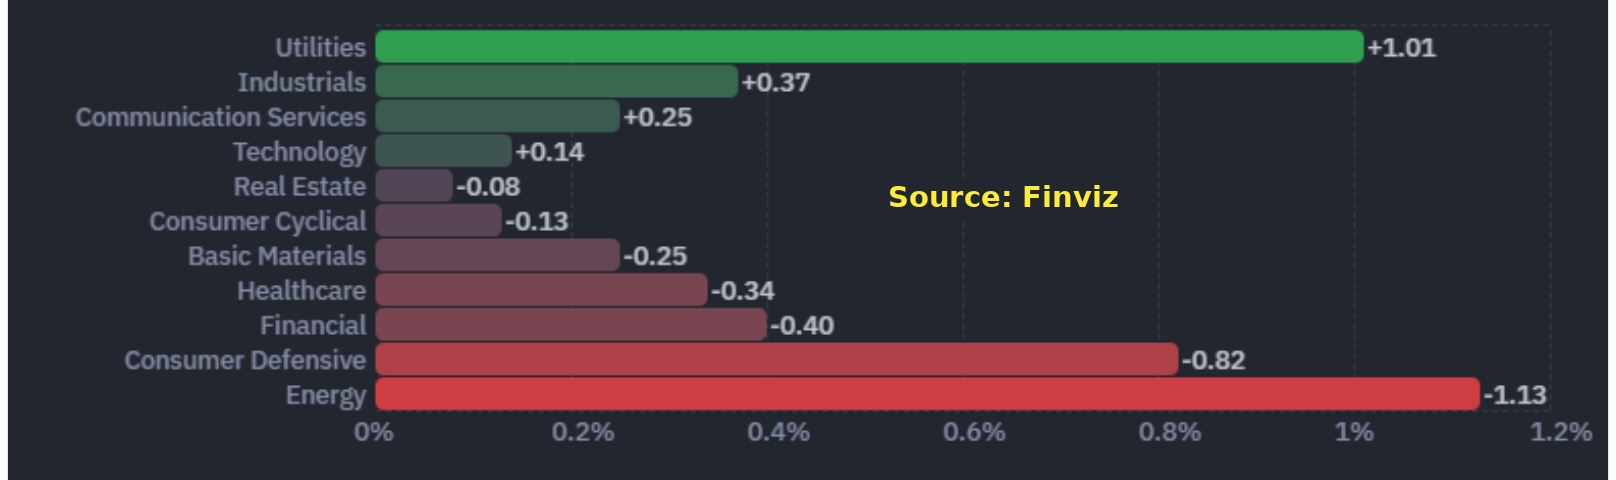
Utilities (+1.01%) led as yields eased, followed by industrials (+0.37%), communication services (+0.25%) and technology (+0.14%). Energy (-1.13%) was the biggest drag as crude plunged, with consumer defensive (-0.82%), financials (-0.40%), healthcare (-0.34%), basic materials (-0.25%), consumer cyclical (-0.13%) and real estate (-0.08%) also in the red. Source: Finviz.
Yields, Dollar & Commodities
2-YEAR TREASURY
4.879%
▼ -5.2bp from 4.931%10-YEAR TREASURY
5.234%
▼ -0.2bp from 5.236%DOLLAR INDEX (DXY)
101.379
▲ from 101.197GOLD
$4,215.0
▲ +1.6% from $4,148.5WTI CRUDE
$88.94
▼ -4.7% from $93.29NATURAL GAS
$3.014
▼ -4.1% from $3.143The bond selloff took a breather: the 10-year spiked to 5.29% intraday before settling at 5.234% as weak confidence and JOLTS data cooled hike fears. Gold rebounded 1.6% to $4,215 while WTI cratered 4.7% to $88.94 as Middle East oil flows recovered to near pre-war levels. Bank of Singapore’s Mansoor Mohiuddin still sees at least one more Fed hike this year, blaming America’s snowballing debt problem for the relentless rise in yields.
Economic Data
Indicator Actual Expected Previous Conference Board Consumer Confidence (Sep) 81.9 89.0 88.6 JOLTS Job Openings (Aug) 7.079M 7.228M 7.335M A double miss on the labor-and-consumer front: confidence plunged to 81.9 versus 89.0 expected (prior 88.6, revised from 89.4), and job openings fell to 7.079 million versus 7.228 million expected (prior 7.335M, revised from 7.271M). Both point to a cooling economy — welcome news for rate-cut hopes, less so for earnings. Fed speakers were out in force: Bowman, Barr, Goolsbee, Williams and Waller all took the mic, with Williams saying there is “no urgency” to tighten again.
Market Sentiment
CNN FEAR & GREED
32 — Fear
Updated Sep 30. Fear deepened from 34 as confidence data disappointed.VIX
16.04
Tuesday close (prev 16.07, -0.19%). Volatility stayed contained as the bond selloff paused and equities drifted.Top Stories
1. Micron reports today — the $370 billion question. Micron reports fiscal Q4 after the close, and the market wants one answer: will hyperscaler AI spending continue into next year? The stock is up 273% this year as AI infrastructure investment soaked up memory supply, but Wall Street expects revenue growth to slow sharply from FY2027. At roughly 7x forward earnings versus ~19x for the S&P 500, the bar for a re-rating is high — and so is the risk if management sounds cautious. (Bloomberg)
2. Consumer confidence craters; JOLTS misses. September consumer confidence collapsed to 81.9 against 89.0 expected, while August job openings fell to 7.079 million against 7.228 million expected. The one-two punch of weak demand signals landed a day before PCE and payrolls — the last big data before the October 28 FOMC. (Conference Board; BLS)
3. Bond selloff pauses at 5.23%. After the 10-year spiked to 5.29%, calm returned in Asian trading with the yield settling at 5.23%. Strong recent U.S. data had fueled bets on another Fed hike, but Tuesday’s soft confidence and JOLTS prints cooled things down. (FT)
4. Barclays: higher rates are sapping equity momentum. Emmanuel Cau’s team notes September still saw equity inflows, but rising rates are killing the TINA (“there is no alternative”) trade. For a year-end rally — and renewed rotation into Europe — oil needs to stay low and stable. With equity volatility still low, they say it’s time to hedge downside risk. (Barclays)
5. Goldman: it’s the pace of the selloff that matters. Peter Oppenheimer warns solid corporate earnings are holding stocks up, but a sharper bond selloff would leave equities vulnerable — the speed and reason for rising yields matter as much as the level. Investment banks are split: Morgan Stanley stays constructive, Barclays stays cautious. (Goldman Sachs)
6. Hyperscaler bond yields erode the equity premium. Another Barclays team (Venu Krishna) finds surging long-term yields are overwhelming strong earnings and upward revisions at the hyperscalers. AI infrastructure players have raised $346 billion this year — roughly double last year — pushing credit spreads and CDS costs higher. (Barclays)
7. Trump and AI CEOs sign voluntary safety pact. The President met OpenAI, Anthropic, Meta, Google and Nvidia leadership and announced a voluntary AI safety agreement: independent audits, internal controls, and no unauthorized hacking of external systems. Trump is weighing a 10-person oversight committee — while reaffirming support for rapid data-center expansion and directing federal agencies to say “Super Intelligence” instead of “Artificial Intelligence.” (Reuters)
8. How Meta turns data centers into billions in tax credits. The New York Times reports Meta has classified AI data centers as potentially-failable “experiments” with the IRS, applying research tax credits to Nvidia chip purchases. The credits ballooned from $700M (2023) to $2.0B (2024) to $3.9B (2025) — making Meta the largest corporate beneficiary. Meta itself admits the IRS could reverse billions. (NYT)
9. Boeing wins the Navy’s $20B next-gen fighter. The Pentagon picked Boeing for the F/A-XX carrier-based stealth fighter, a $20 billion development contract beating Northrop Grumman. It’s Boeing’s second fighter franchise win after last year’s Air Force F-47 — a program that could grow into the hundreds of billions with production and exports, aimed at countering China in the Pacific from the 2030s. (Pentagon)
10. Robinhood debuts weekend trading and perpetual futures. Robinhood will route orders through Bruce Markets to offer weekend trading in select stocks and ETFs — the first in the modern U.S. market (Sunday 8pm to Friday 8pm ET). Also coming: event-linked options on company metrics like Tesla deliveries (pending SEC approval) and up to 10x leverage perpetual futures on select crypto. Nasdaq and NYSE are pursuing 23-hour, 5-day trading within months. (Robinhood)
11. DeepSeek and Huawei open-source a CUDA alternative. DeepSeek and Huawei jointly released open-source software for Huawei’s Ascend AI accelerators — including TileLang, positioned as China’s answer to Nvidia’s CUDA. It’s the most direct Chinese challenge yet to Nvidia’s software moat. (Bloomberg)
12. Hedge funds hold a record slice of the $30T Treasury market. Hedge funds’ Treasury holdings tripled in five years to $2 trillion — 7% of marketable Treasuries, an all-time high. Regulators warn their leveraged basis trades funded with repo could trigger cascading margin calls in a stress event, even as the funds supply liquidity in calm times. (CNBC)
13. Kalshi nears $1B raise at $40B valuation. Reuters reports the prediction-market exchange is finalizing a ~$1 billion raise led by Tiger Global and Dragoneer at a $40 billion valuation — nearly double May’s $22B. Kalshi is expanding beyond sports and election betting into a multi-asset trading platform competing with CME and ICE. (Reuters)
14. Mideast oil flows back to 98% of pre-war levels. JPMorgan estimates crude shipments recovered to 17.5 million bpd — 98% of pre-war levels — with Saudi and other Gulf producers offsetting lost Iranian barrels. September’s global oil market was roughly balanced. But Brent still holds above $103, and Goldman warns re-escalation could hit energy infrastructure again. (Bloomberg)
15. China lithium futures plunge 25% in September. Lithium carbonate futures fell from over ¥160,000 to under ¥120,000 per ton on battery-demand fears — overcapacity, a new battery consumption tax, and China’s slowdown. Some see an overshoot: monthly supply deficits should support prices into year-end. (Bloomberg)
16. White House weighs diesel export ban before midterms. The FT reports emergency talks on banning diesel exports as prices run 70%+ above pre-war levels after seven months of war with Iran. Farm-state Republicans want the ban; the oil industry and some cabinet officials warn it could raise fuel prices in parts of the U.S. No decision yet. (FT)
Crypto Desk
BITCOIN
~$83.4K
steady near $83–84KETHEREUM
~$2,670
eased from $2,720BTC SPOT ETF (SEP 29)
+$66.2M
net inflowETH SPOT ETF (SEP 29)
-$2.8M
net outflowCrypto treaded water under the weight of 5%+ Treasury yields and a firm dollar: Bitcoin held near $83.4K and Ether near $2,670, giving back part of Monday’s bounce. BTC spot ETFs drew +$66.2M while ETH ETFs saw a small -$2.8M outflow. Tom Lee called for a “new bull market, stronger than before,” and Robinhood unveiled AI-agent trading plus crypto perpetual futures. (prices via CoinMarketCap/CoinGecko)
Single-Stock News — Earnings Whispers
MU — D-day after the close. All eyes on hyperscaler capex commentary; the stock has tripled-plus this year on the memory supercycle.
META — tax-credit scrutiny. NYT exposé on the $3.9B R&D credit play; IRS reversal risk acknowledged in Meta’s own filings. Separately, Meta’s Muse AI assistant rollout continues.
MRNA — Citi cuts to Sell. Citi downgraded Moderna from Neutral to Sell with an $80 price target.
BA — $20B Navy fighter win. F/A-XX award over Northrop; second major fighter franchise after the F-47.
HOOD — weekend trading. First modern-era weekend equities trading plus 10x crypto perps and event-linked options (SEC pending).
AMZN — joined as a strategic investor in Taiwan PCB maker Gold Circuit.
AAPL — Counterpoint sees ~6 million iPhone Duo foldables ($1,999) selling in 2026; Apple hit an unusual 33% China smartphone share as rival flagships got pricier.
BABA — AliExpress piloting “Elite” VIP membership for $800+/year shoppers, launching in Korea next month — a direct challenge to Amazon Prime.
PSKY — Paramount’s $52B Warner Bros. financing faces surging interest costs as rates climb.
CCL — earnings pop. Reported Tuesday morning; shares surged 13.4%, the S&P 500’s top gainer.
FICO — collapse. Plunged 26.5%, the day’s worst S&P 500 performer by far.
Earnings to watch: Micron (AMC today — the marquee), Jabil and Conagra (BMO today); Accenture and McCormick (BMO Thursday), Nike (AMC Thursday). Source: Earnings Whispers.
Single-Stock Movers — Trefis
1-day winners and losers in the S&P 500. Data as of Tuesday, September 29, 2026. Source: Trefis.
Top Winners 1-Day Top Losers 1-Day CCL Carnival Corporation +13.4% FICO Fair Isaac -26.5% BE Bloom Energy +10.8% STLD Steel Dynamics -3.9% RCL Royal Caribbean +7.5% LULU Lululemon Athletica -3.7% LITE Lumentum +5.7% NUE Nucor -3.6% CVNA Carvana +5.2% EFX Equifax -3.4% AMAT Applied Materials +5.2% SLB SLB -3.1% DASH DoorDash +4.9% ITW Illinois Tool Works -3.1% GLW Corning +4.7% FDS FactSet Research Systems -2.9% MRVL Marvell Technology +4.5% WYNN Wynn Resorts -2.8% EIX Edison International +4.1% PSKY Paramount Skydance -2.8% Carnival’s post-earnings 13.4% surge led the winners, with Bloom Energy rebounding 10.8% a day after its 8.9% plunge. Fair Isaac’s 26.5% collapse was in a league of its own among losers.
Calendar
Wednesday, Sep 30 — August PCE (8:30 ET), the week’s main event and the Fed’s preferred inflation gauge; ADP employment (8:15); Q2 GDP final revision (8:30); Chicago PMI; EIA crude inventories; Fed speakers Cook, Kashkari and Goolsbee. Q3 ends. Earnings: Micron (AMC, the marquee report), Jabil and Conagra (BMO), Cal-Maine.
Thursday, Oct 1 — Initial jobless claims (8:30); ISM Manufacturing PMI (10:00); construction spending. Earnings: Accenture and McCormick (BMO), Nike (AMC).
Friday, Oct 2 — September jobs report: nonfarm payrolls, unemployment rate, and average hourly earnings (8:30 ET); factory orders. No major earnings — payrolls own the day.
Sources
Index closes, yields, commodities, sentiment: SKN Finance, vistapglobal, TradingView and market data. Sector maps: Finviz. Single-stock movers: Trefis. Single-stock news and earnings calendar: Earnings Whispers. Crypto prices and flows: CoinMarketCap, CoinGecko. Fear & Greed: CNN. Economic calendar: Schwab Network, WSJ. Data as of Wednesday morning, September 30, 2026 (ET) unless noted.
Not financial advice. This briefing is for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any security.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — Oct 16: Warsh Cools Hike Bets, Dow Jumps, Tesla Roadster Flies [0] | Master | 10-16 | 0 |
| Morning Briefing — Oct 15: CPI Aftershock, Anthropic’s $16.8B Quarter, TSMC Record [0] | Master | 10-15 | 0 |
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.