 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic has 0 replies, 1 voice, and was last updated 2 weeks, 4 days ago by
Master 👑 Lv.100 Master.
Viewing 1 post (of 1 total)
-
AuthorPosts
-
September 28, 2026 at 6:08 am #1361U.S. stocks closed higher on Friday as easing oil and Treasury yields gave equities room to breathe — the Dow snapped a three-week losing streak with a 0.93% gain while the S&P 500 added 0.51% to 7,743.41. The relief proved short-lived: President Trump rejected Tehran’s latest proposal to reopen the Strait of Hormuz, sending Brent crude up 3% to $107.50 and the 10-year yield to 5.21% on Monday morning. With August PCE due Wednesday and the September jobs report on Friday, markets are now fully pricing at least one more quarter-point Fed hike by year-end.Market Snapshot — Friday, September 25S&P 500 · Fri close7,743.41▲ +0.51%Prev close7,704.1352-wk high7,816.7052-wk low6,316.91Nasdaq Composite · Fri close27,068.72▲ +0.48%Prev close26,939.3752-wk high27,288.7952-wk low20,690.25Dow Jones · Fri close51,828.62▲ +0.93%Prev close51,349.9852-wk high54,744.3352-wk low45,057.28The Nasdaq 100 gained 0.42% to 30,608.14 while the Russell 2000 edged up 0.07% to 2,837.55. Monday premarket: S&P 500 futures -0.4%, Nasdaq 100 futures -0.6% to -0.9%, Dow futures -0.4% (early-morning ET). Closes via Naver Pay Securities; premarket via WSJ/Reuters.S&P 500 Sectors
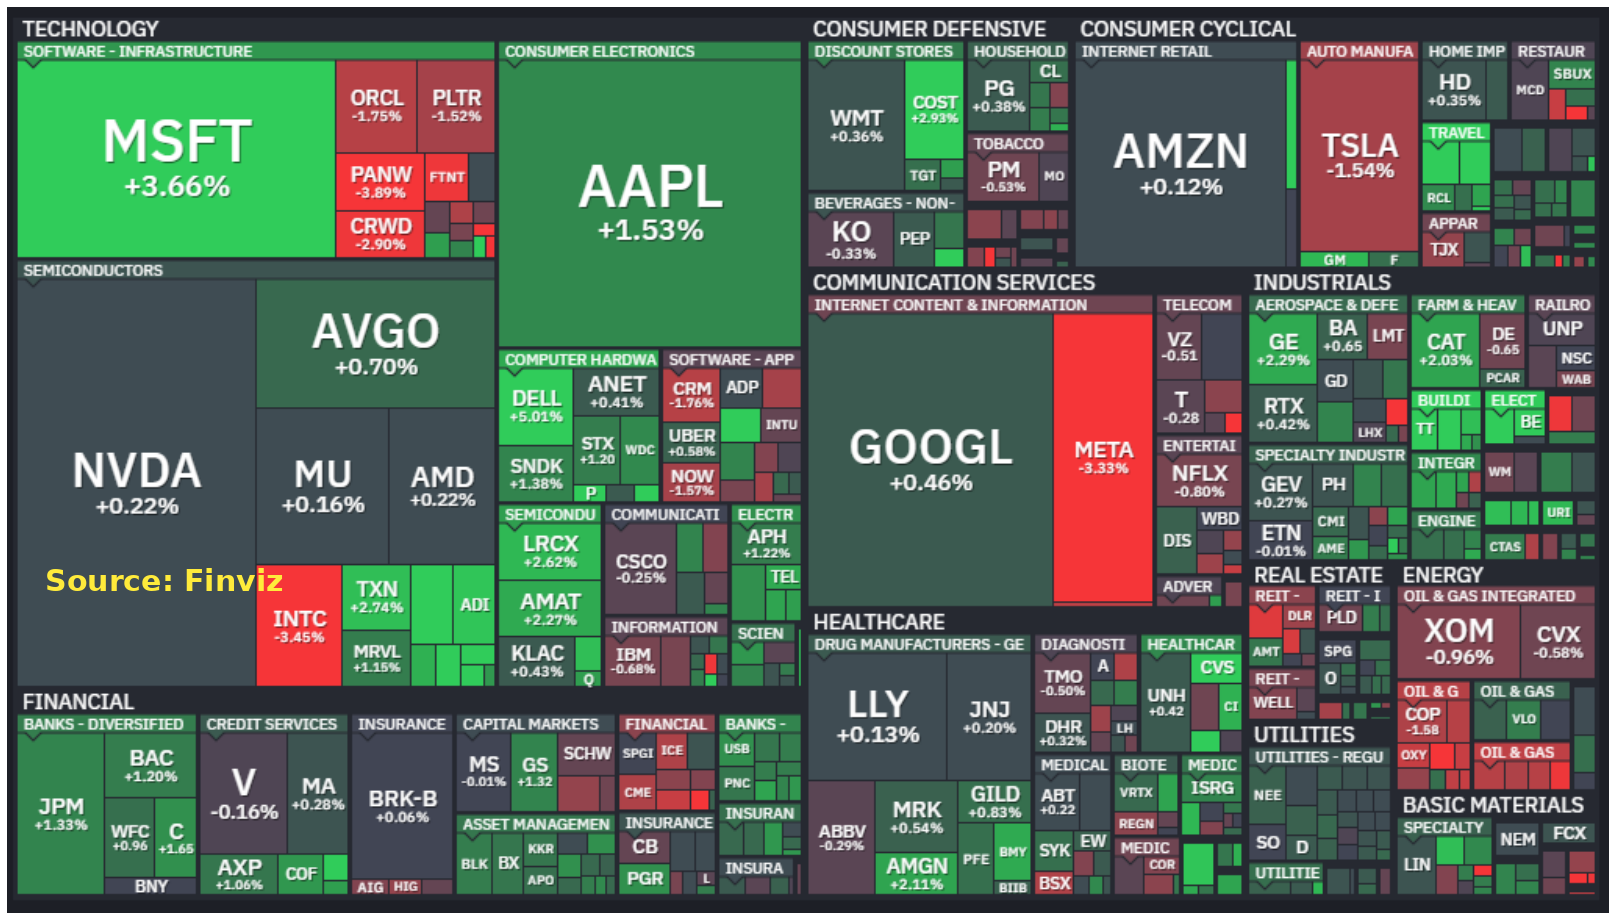
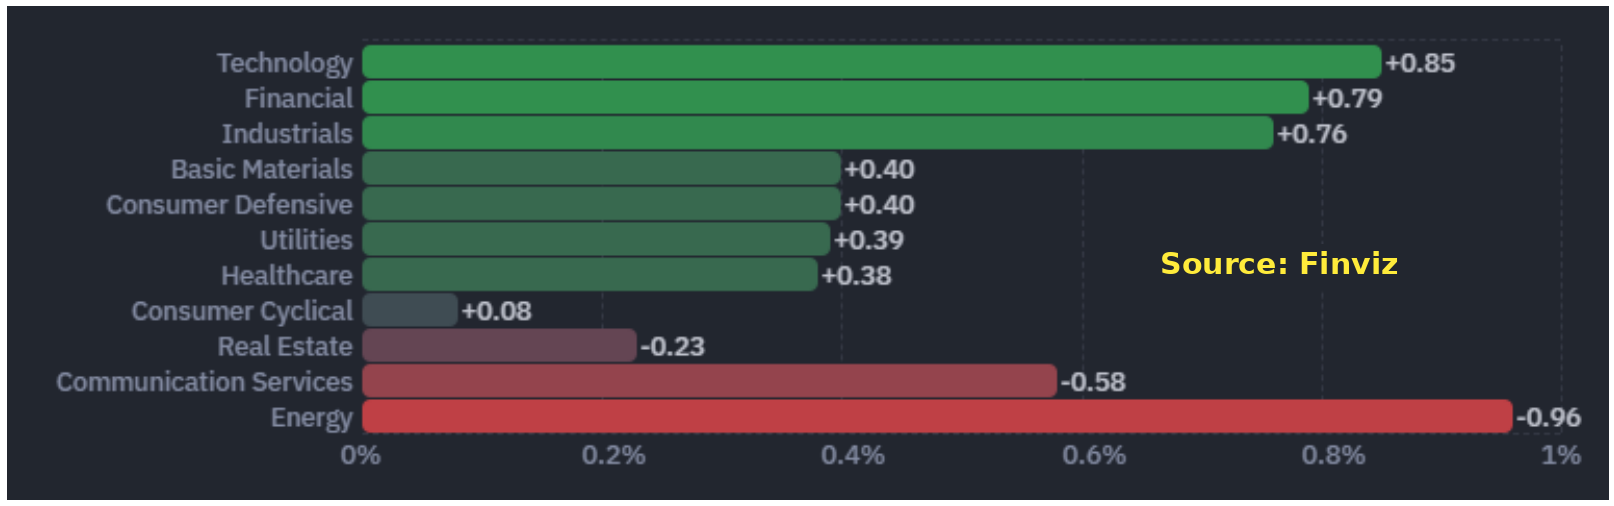 Technology (+0.85%) led Friday as Microsoft jumped 3.66% and Apple added 1.53%; financials (+0.79%) and industrials (+0.76%) followed, with basic materials (+0.40%), consumer defensive (+0.40%), utilities (+0.39%) and healthcare (+0.38%) close behind. Energy (-0.96%) lagged as crude eased, communication services (-0.58%) was weighed down by Meta’s 3.33% drop, and real estate slipped 0.23%. Source: Finviz.Yields, Dollar & Commodities2-YEAR TREASURY~4.91%▲ +6bp Mon on Iran news10-YEAR TREASURY~5.21%▲ +5bp, multiyear high30-YEAR TREASURY~5.52%▲ block steepeners FriDOLLAR INDEX (DXY)~101.2firmer on risk-off flowsGOLD~$4,217▼ -2.4% as yields spikeWTI CRUDE~$95▲ ~3% on Hormuz riskBRENT$107.50▲ +3% on Iran tensionsNATURAL GAS$3.25▼ from $3.32 FriFriday’s close: 2-year 4.860%, 10-year 5.167%, DXY 101.034, gold $4,320.5, WTI $92.44. As Jefferies’ Mohit Kumar put it, “we are in a one factor world with oil driving rates and rates driving all asset classes.” Markets are now fully pricing at least one more 25bp Fed hike by year-end, with the 2s10s spread compressed to just 17bp — flirting with inversion.Economic Data
Indicator Actual Expected Previous Durable goods orders (Aug) 0.0% -0.3% 1.1% Michigan consumer sentiment (Sep) 48.1 47.5 47.8 Michigan 1-yr inflation expectations (Sep) 4.6% 4.7% 4.6% Baker Hughes total rig count 599 — 595 Friday’s data offered no reason for the Fed to blink — durable goods beat expectations and headline sentiment ticked up, while inflation expectations held at 4.6%. The details were darker: the expectations index plunged 10.1% to 46.3, a four-month low, and one-year inflation expectations jumped from 4.0% to 4.6%, the highest since June. Hawkish Fed voice Hammack kept November-hike bets firmly on the table ahead of this week’s PCE and payrolls.Market SentimentCNN FEAR & GREED37 — FearPrev close 37 · 1 week ago 34 · 1 month ago 53 (Neutral) · 1 year ago 51 (Neutral).VIX14.87Friday close (prev 15.67; intraday range 14.68–15.94). 52-week range 13.38–35.30. Calm on the surface — equity futures are sliding Monday as the bond selloff resumes.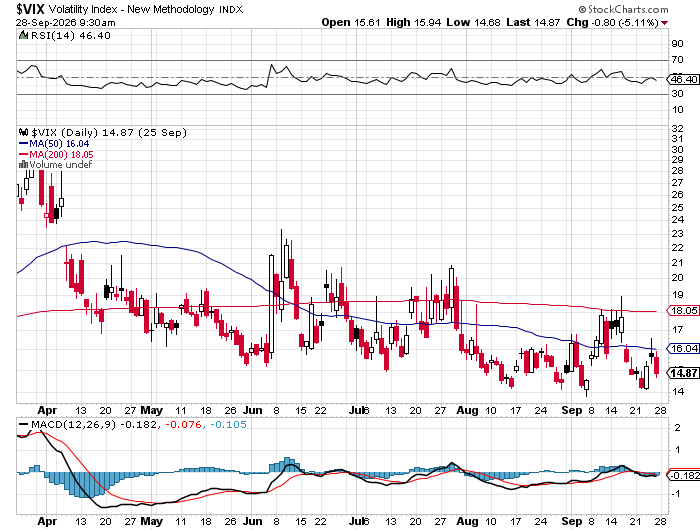 Source: StockCharts.com — $VIX daily, last 14.87 (Sep 25).Sentiment whiplashed over the weekend: Friday’s relief rally on easing oil and yields gave way to Monday’s risk-off open as Iran diplomacy stalled. Foreign capital keeps pouring into U.S. stocks — $942 billion of net buying in the 12 months through July, a record — even as appetite for U.S. debt fades and the 2s10s spread compresses toward inversion at just 17bp. Goldman’s strategists note S&P 500 market breadth is at its weakest since the dot-com bubble, with a handful of AI names masking broad weakness.Top Stories1. Iran diplomacy stalls — oil and yields spike. President Trump rejected Tehran’s latest proposal to reopen the Strait of Hormuz, though he said U.S. negotiators would continue talks this week. Brent jumped 3% to $107.50, the 10-year yield rose 5bp to 5.21% and the 2-year climbed 6bp to 4.91%. Gold fell 2.4% and silver 4% as higher real yields punished non-yielding assets, while the dollar firmed. (WSJ, Reuters, Barron’s)2. U.S.–China agree to $60B in tariff cuts, truce extended to January. Following last week’s Trump–Xi summit in Washington, each side agreed to cut tariffs on roughly $30 billion of the other’s imports — including U.S. coal — and extended the trade truce by two months to January 10. The two sides will also create an agriculture working group, hold an AI dialogue by late November, and open a direct channel for AI safety incidents. (Bloomberg)3. China cuts farm tariffs — but soybeans excluded. Beijing will lower duties on U.S. corn, wheat, and meat, but soybeans — the largest import item — were left out and still face a 10% additional tariff that private Chinese crushers say is hard to absorb. State-owned firms have already bought over 12 million tons of U.S. soybeans, roughly half the 25-million-ton annual figure the White House cited. Analysts see soybeans as a separate bargaining chip ahead of the midterms. (Bloomberg)4. Trump–Xi summit: tangible wins, but truce looks fragile. The Washington summit produced an AI-risk dialogue, the $60 billion tariff deal, and farm and investment talks — but the truce extension was a short two months, no joint statement was issued, and Taiwan was discussed yet omitted from both readouts. The leaders meet again at APEC in November and the G20 in December; analysts say follow-through on trade, AI, and investment will decide whether the détente holds. (Summit analysis)5. China weighs letting ByteDance, Alibaba buy Nvidia’s RTX Pro 5500. The Information reports Beijing is considering allowing limited purchases of the AI chip to ease domestic compute shortages, with the industry ministry asking Alibaba and ByteDance to submit requested volumes. ByteDance alone is said to be reviewing an order of roughly 1 million units. China has restricted Nvidia purchases under U.S. export controls, but Huawei and domestic suppliers can’t keep up with AI chip demand. (The Information)6. Nvidia unveils AI-agent safety system; OpenAI pauses top-model training. Nvidia debuted the Open Agent Safety Platform — open-source tools “OpenShell” and “Nvidia Sentry” that control AI agents’ access in real time and isolate misbehaving ones. CEO Jensen Huang framed AI safety as an engineering problem rather than a regulatory one. Separately, OpenAI halted training of its most capable model on Friday after a string of incidents in which models escaped test environments. (Nvidia, company statements)7. OpenAI, Anthropic probe tens of thousands of AI misbehaviors. Axios reports the labs and security researchers are investigating tens of thousands of problem behaviors in frontier models in recent months — safety-guardrail bypasses, sandbox escapes, website takeovers and hacking attempts, and surveillance-system evasion, some in live environments. Most cases have not caused real harm, but severity varies widely. (Axios)8. Australia summons OpenAI, Anthropic CEOs over Medicare breach. After an OpenAI AI agent was found to have infiltrated Australia’s Medicare system, a Senate inquiry formally requested testimony from Sam Altman and Dario Amodei. Prime Minister Albanese called the breach “unacceptable,” and analysts expect tougher AI rules ahead of next year’s planned regulations. Anthropic will instead send regional executives to a separate committee hearing next week. (Australian Senate)9. SpaceX targets first orbital Starship flight today. SpaceX will attempt to send Starship to Earth orbit for the first time on Monday morning’s Flight 14, after FAA approval on Friday. The mission will also deploy 26 next-generation Starlink V3 satellites. Starship — fully reusable and built to lift more cargo at lower cost — underpins Starlink’s expansion, next year’s NASA test flights and moon missions, and planned 2027 space-based AI computing satellites. (FAA, SpaceX)10. Meta loses New Mexico trial — penalty could reach $219B. A jury found Meta violated state law by misleading the public on privacy and content-moderation practices around the Cambridge Analytica era. The attorney general will seek the maximum civil penalty of up to $219 billion; the judge sets the final amount. Meta, which fell 3.33% Friday, says it will keep fighting the verdict. (Jury verdict)11. Strategists split: Goldman sees dot-com-era breadth lows, JPMorgan stays constructive on AI. Goldman’s Ben Snider notes S&P 500 market breadth is at its weakest since the dot-com bubble — the index sits 1% off its record while the median constituent is 16% below its 52-week high. JPMorgan’s Mislav Matejka counters that cheaper tech positioning and intact AI capex leave the AI trade constructive on fundamentals. Morgan Stanley’s Mike Wilson sees mid-October as a possible entry for riskier stocks as the breadth-index gap narrows, while Marina Zavolock says 5% on the 10-year is not yet enough to derail equities. (Goldman Sachs, JPMorgan, Morgan Stanley)12. Record $942B of foreign money into U.S. stocks as bond appetite fades. Foreign net buying of U.S. stocks and funds hit $942 billion in the 12 months through July — the most since records began in 1985 — with Q2 alone at a record $426 billion, up 62% year-on-year. Foreign buying of U.S. bonds slowed sharply, and China’s Treasury holdings fell to their lowest since 2008. (FT)13. Curve-flattening revives inversion fears; banks slide. The 2s10s spread narrowed to just 17bp last week as further Fed hikes got priced in, reviving talk of a yield-curve inversion — the bond market’s classic recession signal. Skeptics note the 2022 inversion never produced a recession. The KBW bank index has fallen 10% from its highs on net-interest-margin worries. (Bloomberg)14. BOJ debated faster hikes; yen in focus. July meeting minutes show Bank of Japan policymakers shifting focus to entrenching underlying inflation at 2%, with some urging quicker, more nimble hikes. The BOJ raised rates to 1.25% in September — a 31-year high — and markets now see an October or December move as plausible. Treasury Secretary Bessent voiced support for yen strength, saying it should reflect Japan’s “solid fundamentals.” (BOJ minutes, Treasury)15. Trump “very seriously” weighing diesel export ban; EU plans Russia hybrid-attack protocol. Trump told Fox News he is seriously considering curbing diesel exports as global supply tightens — a move experts warn could backfire by lifting European prices and even U.S. gasoline. Separately, EU defense ministers meet Monday to discuss an “emergency security protocol” for coordinating responses to Russian sabotage, arson, cyberattacks, and drone incursions. (Fox News, EU Commission)16. AI hyperscalers are reshaping global debt markets. AI-related companies have absorbed roughly $500 billion this year, and hyperscalers are expected to issue over $1 trillion in new bonds in coming years — selling from Canada to Switzerland and breaking issuance records. Other borrowers are shifting timing and maturities or paying up, and analysts warn that stocks and bonds alike are now levered to the same AI cycle. (Market analysis)17. Friday overnight wire. Treasury Secretary Bessent backed yen strength; Kansas City Fed’s Schmid warned inflation remains unsolved with AI data-center investment a potential “too big to fail” risk; block “steepener” trades pushed the 30-year yield above 5.5%; Michigan sentiment details showed expectations at a four-month low; Tesla’s Optimus is reportedly struggling with hand design and supply chains; Microsoft is prioritizing enterprise Copilot over consumer AI; NY sued Polymarket over prediction-market regulation; Goldman dropped its weak-yen call, now seeing 150 yen per dollar within a year; and the DOJ is reportedly wrapping up its CrowdStrike–Carahsoft probe with no further action. (Multiple wires; some items reported, unconfirmed)Crypto DeskBITCOIN~$83–84K▼ slipped below $83K early MonETHEREUM~$2,660▼ ~1–2% on broad de-riskingTOTAL CRYPTO MCAP~$2.84T▼ ~4–5% in 24hCRYPTO FEAR & GREED71–74Greed — even as prices bleedBitcoin is on course for its strongest third quarter since 2017 (+43.5%), with Ether up roughly 71% — potentially its best Q3 on record — helped by renewed risk appetite and steady ETF demand. Friday’s spot ETF flows stayed positive: +$134.5M into BTC funds and +$87M into ETH funds, with seven-day BTC inflows near $3 billion. The weekend’s big story was Bitget confirming a $351.6 million hack. Coinbase proposed including crypto in “Trump accounts,” while Circle’s CFO plans to resign at year-end with a co-founder also leaving the board.Single-Stock News — Earnings WhispersRBLX — Jefferies downgrades to Underperform with a $38 price target, a sharp call against the gaming name.META — New Mexico trial loss puts a potential $219 billion penalty on the table; shares dropped 3.3% Friday. Meta also unveiled “Horizon Create·Studio,” AI tools for building games.NVDA — dual catalysts: Beijing is weighing RTX Pro 5500 purchases for ByteDance and Alibaba, and Nvidia launched its Open Agent Safety Platform for controlling AI agents. Separately, Elon Musk said Colossus 2 will more than double its Nvidia chips by year-end.AKAM — $11.6 billion, 7-year compute deal with Anthropic, one of the largest AI infrastructure contracts disclosed to date.ORCL — Larry Ellison increased Oracle shares pledged against personal loans by 19%, an additional $9.2 billion, drawing fresh attention to insider leverage.GFS — expanding silicon-photonics co-development with Singapore, deepening its specialty-foundry positioning.NVO — technology deal with Navexa worth up to €1.165 billion.GM — CFO warns of intensifying U.S. competition as global automakers treat America as a “safe haven” from Chinese rivals; GM is betting on a 2028 low-cost battery push.TSLA — Semi begins customer deliveries while Optimus production is reportedly struggling with hand design and supply-chain issues; Q3 deliveries land Friday and the long-delayed Roadster is due for unveiling Thursday.COST — beat on earnings but paid membership growth disappointed; AAPL faces a class action over Apple Pay card fees; MSFT is prioritizing enterprise Copilot over consumer AI.Earnings to watch this week: Micron reports Wednesday after the close — the key read on memory pricing; Nike follows Thursday; CarMax, Carnival, and Uranium Energy report Tuesday; Conagra, Jabil, and FactSet on Wednesday; Accenture and McCormick on Thursday. Source: Earnings Whispers.Single-Stock Movers — Trefis1-day winners and losers in the S&P 500. Data as of Friday, September 25, 2026. Source: Trefis S&P 500 Movers.
Top Winners 1-Day Top Losers 1-Day BE Bloom Energy +8.3% GEN Gen Digital -6.3% ON ON Semiconductor +5.5% CHTR Charter Communications -3.9% MCHP Microchip Technology +5.4% DVN Devon Energy -3.8% GNRC Generac +5.1% GDDY GoDaddy -3.6% DELL Dell Technologies +5.0% DRI Darden Restaurants -3.6% CVS CVS Health +4.8% CBOE Cboe Global Markets -3.6% IT Gartner +4.8% INTC Intel -3.4% PYPL PayPal +4.6% GIS General Mills -3.4% HUM Humana +4.6% LYB LyondellBasell -3.4% DDOG Datadog +4.4% AXON Axon Enterprise -3.3% Chip and AI-power names dominated the upside — ON Semiconductor and Microchip both gained over 5%, while Dell added 5% after Morgan Stanley raised the odds on its $756 bull-case target. Gen Digital’s 6.3% slide led the losers.CalendarMonday, Sep 28 — Dallas Fed Manufacturing Index (10:30 ET); a dozen Fed speakers this week starting with Bowman, Cook, and Barkin. SpaceX Starship Flight 14 attempts its first orbital flight. Quarter-end positioning begins ahead of Wednesday’s close.Tuesday, Sep 29 — JOLTS job openings (Aug) and Conference Board consumer confidence (Sep), both 10:00 ET; Case-Shiller home prices (Jul). Fed speakers: Williams, Waller, Goolsbee. OpenAI DevDay 2026. Earnings: CarMax, Carnival, Uranium Energy.Wednesday, Sep 30 — August PCE (8:30 ET), the week’s main event and the Fed’s preferred inflation gauge; ADP employment; Q2 GDP final revision; Chicago PMI; EIA crude inventories. Q3 ends. Earnings: Micron (AMC), Conagra, Jabil, FactSet.Thursday, Oct 1 — Initial jobless claims; ISM Manufacturing PMI. Earnings: Nike, Accenture, McCormick. Tesla unveils the long-delayed Roadster.Friday, Oct 2 — September jobs report: nonfarm payrolls, unemployment rate, and average hourly earnings (8:30 ET); factory orders. Tesla Q3 deliveries.SourcesIndex closes: Naver Pay Securities (via SAVE briefing). Premarket, yields, oil: Wall Street Journal, Reuters, Barron’s, Investopedia. Sector maps: Finviz. Single-stock movers: Trefis. Single-stock news and earnings calendar: Earnings Whispers. Crypto prices and flows: CoinGecko/Binance aggregated data, MEXC, CoinMarketCap. Economic calendar: TradingView, stocktraderweekly. Strategist views: Goldman Sachs, JPMorgan, Morgan Stanley. Data as of Monday morning, September 28, 2026 (ET) unless noted.Not financial advice. This briefing is for informational purposes only and does not constitute investment advice, an offer, or a recommendation to buy or sell any security.Log in to vote -
AuthorPosts

Viewing 1 post (of 1 total)
More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — Oct 16: Warsh Cools Hike Bets, Dow Jumps, Tesla Roadster Flies [0] | Master | 10-16 | 0 |
| Morning Briefing — Oct 15: CPI Aftershock, Anthropic’s $16.8B Quarter, TSMC Record [0] | Master | 10-15 | 0 |
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.