 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic is empty.
-
AuthorPosts
-
October 14, 2026 at 6:57 am #2354
Inflation just crashed the party. September CPI came in hotter than expected on both headline (3.7%) and core (2.6%), sending the 10-year to 5.29% and putting an October Fed hike back on the table.
Today is a gauntlet: CPI fallout, Morgan Stanley earnings, the Beige Book at 2 PM ET — and PPI plus retail sales tomorrow morning. Here’s everything you need before the open.
Yesterday’s Close
Index Close Change S&P 500 7,805.45 -0.02% Dow Jones 51,670.10 -0.35% Nasdaq Composite 27,204.38 -0.15% Russell 2000 2,783.37 -0.40% VIX 15.21 +0.5% 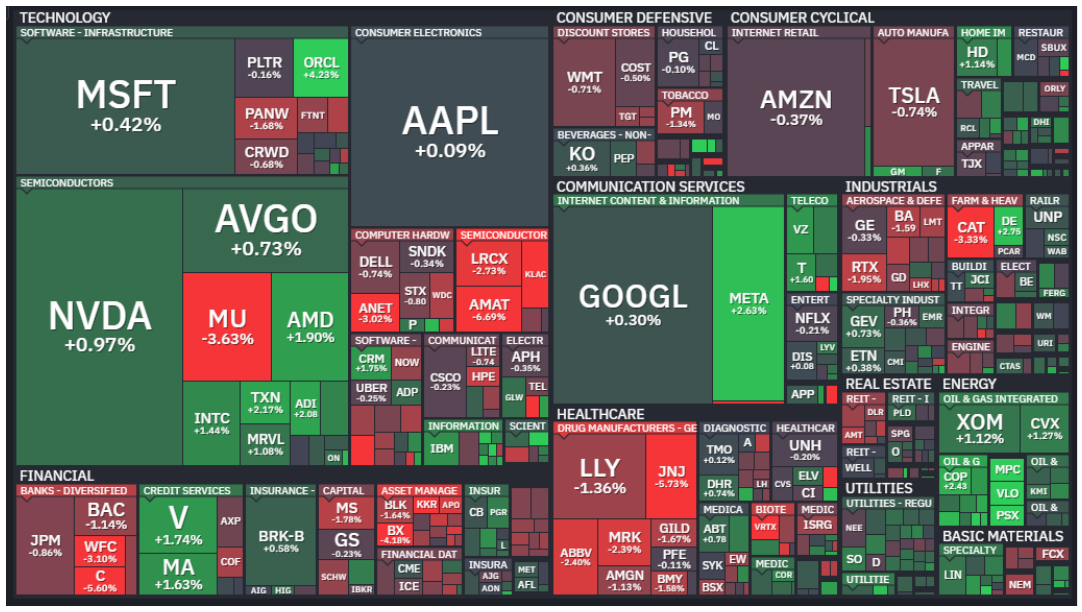
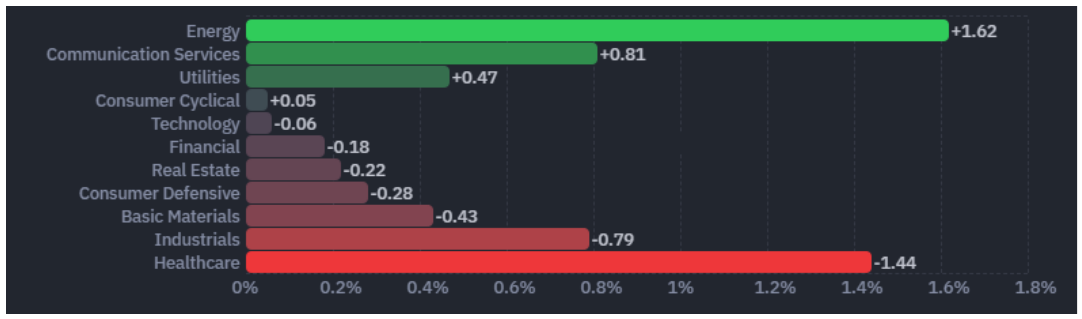
Source: Finviz. Data as of October 13 close.
Yields, Dollar & Commodities
Asset Level Move 10-year Treasury 5.29% +10bp post-CPI 2-year Treasury 4.92% +13bp post-CPI Dollar index 102.18 steady Gold $4,184/oz -0.3% WTI crude $94.79 +1.7% Brent crude ~$106 elevated Natural gas $3.32 +4.5% Bitcoin ~$83,000 flat Economic Data
- September CPI (released 8:30 AM ET today): Headline 3.7% y/y (vs 3.6% expected, up from 3.4%); core 0.3% m/m (vs 0.2% expected), 2.6% y/y. Energy +5.2% m/m drove the beat; shelter accelerated to +0.4%. Full CPI breakdown here.
- Existing home sales (Sept): 3.99m — beat the 3.95m consensus. Housing holding up despite high rates.
- ADP weekly employment: 24.75K — consistent with the cooling labor trend (September payrolls added just 29K).
Market Sentiment
- Fear & Greed Index: 45 — Neutral. Neither panic nor euphoria; the market is waiting on the Fed.
- VIX at 15.21 — complacent given the CPI shock and two Fed meetings ahead. Volatility is arguably underpriced.
- BofA survey: Tech allocation at a 6-year high while 45% of managers expect an AI bubble by 2027. Cash at 3.9%.
Top Stories
Hot CPI revives October hike bets. Core inflation beat on both monthly and annual readings. Pre-CPI odds were 22% for an October 28 hike and 88% by December — expect October pricing to jump toward a coin flip. The 2-year’s 13bp spike says the market is repricing Fed policy itself.
ASML’s record quarter vs. the chip rout. ASML posted €4.96B net income (vs €4.1B expected) and raised 2026 guidance for the third time (€44–45B). The CEO says 2027–2028 supply won’t meet demand. Meanwhile the CXMT-driven memory selloff continued: Micron -3.6%, SK Hynix -3.2%.
RBC downgrades US tech. RBC cut US technology from Overweight to Neutral, upgrading Healthcare to Overweight — a rotation call that matches yesterday’s tape. Jefferies also urges diversification beyond AI, liking healthcare services, transports, and biotech.
Oil’s war premium grows. Iran’s IRGC claims a container ship hit a mine in Hormuz and sank. The Houthis are reportedly building a 1,200-mile ballistic missile with Chinese parts. Trump’s Russia diesel deal (4.8M tons ≈ 10 days of US demand) and US diesel at $6.28/gal (+72% YoY) keep energy inflation front and center. The IEA warns of a diesel squeeze into H2 2027.
IMF’s debt warning. Managing Director Georgieva says growth alone can’t fix US debt — now past $40T — with the CBO estimating 6% sustained growth would be needed. Germany is pushing EU import quotas on China after a record $34.8B September trade deficit.
Deal flow: SK Group’s Chey Tae-won is selling a 1.34% SK Inc. stake to Michael Dell’s family office for ₩544B (~$406M) toward his divorce settlement. Tencent issued ~$5.7B in bonds — offshore yuan 10-year at 2.4% vs 6%+ dollar rates. Taiwan agreed to buy 30% of Alaska LNG output for 20 years.
AI infrastructure watch: Google launched Gemini 4 Argon ($2/$10 per 1M input/output tokens). Nvidia partnered with LSEG on tick-data. CoreWeave is targeting “unlimited” insurer capital with $52B in debt and leases on the books.
Crypto Desk
- ETF flows flipped positive: BTC +$175M, ETH +$24.84M in daily inflows — a sharp reversal from last week’s outflows.
- Solana’s Alpenglow mainnet beta goes live October 21 — the biggest Solana upgrade of the year.
- Polymarket is reportedly mulling an IPO — prediction markets going mainstream.
- Bitcoin holding ~$83,000 into the CPI/Fed gauntlet; direction follows macro this week.
Single-Stock News: Earnings Whispers
- Today before the open: Morgan Stanley — the last big bank. Watch trading revenue vs Goldman’s 72% equities surge.
- Reported this morning: BlackRock beat big (adj. EPS $15.93, AUM $15.49T, +3% premarket). Bank of America missed on a $1.2B AML fine (EPS $0.91 vs $1.10, -4%). Full 8-company earnings roundup.
- Tomorrow: TSMC (2:00 AM ET) — the AI supply-chain tell; PNC, Charles Schwab before the open.
Single-Stock Movers (Oct 13, via Trefis)
Winners Losers Valero Energy (VLO) +4.5% Johnson & Johnson (JNJ) -5.7% Expand Energy (EXE) +4.5% Citigroup (C) -5.5% Meta (META) +2.6% Blackstone (BX) -4.2% AMD +1.9% Micron (MU) -3.6% Movers as of October 13 close. Data via Trefis/Investopedia.
Today’s Calendar (ET)
Time Event Before open Morgan Stanley earnings 8:30 AM September CPI — released, hot (3.7%) 10:30 AM EIA crude inventories 2:00 PM Fed Beige Book Thursday 8:30 AM PPI + Retail Sales + Jobless claims Sources
- Bureau of Labor Statistics — CPI September 2026 (via Morningstar): morningstar.com
- Investor’s Business Daily — CPI Inflation Overshoots: investors.com
- Reuters — US consumer prices accelerate in September: reuters.com
- TipRanks — ASML Posts Record Q3 2026 Results: tipranks.com
- Barron’s — Bank of America Stock Falls on $1.2B Fine: barrons.com
- Finviz — S&P 500 heatmap and sector performance
Not financial advice. Do your own research.
Log in to vote -
AuthorPosts

More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
| Morning Briefing: September 29, 2026 [0] | Master | 09-29 | 0 |
| Morning Briefing: September 28, 2026 [0] | Master | 09-28 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.