 BTC
 ETH
 XRP
 SOL
 DOGE
- This topic has 0 replies, 1 voice, and was last updated 2 weeks, 6 days ago by
Master 👑 Lv.100 Master.
Viewing 1 post (of 1 total)
-
AuthorPosts
-
September 25, 2026 at 6:30 am #475U.S. stocks closed mixed on Thursday as a historic bond rout collided with tentative diplomatic progress. The Dow fell for a third straight session while the S&P 500 and Nasdaq finished essentially flat. The 30-year Treasury yield touched 5.48% — its highest since 2004 — even as hopes for a phased U.S.–Iran deal to reopen the Strait of Hormuz cooled crude. Strong labor and housing data, with jobless claims at 197K and new home sales surging to 684K, kept Fed hike bets firmly alive. (With Friday’s session yet to begin, this edition covers Thursday’s close.)Market Snapshot — Thursday, September 24S&P 500 · Thu close7,704.13▼ -0.02%Prev close7,706.0352-wk high7,816.7052-wk low6,316.91Nasdaq Composite · Thu close26,939.37▲ +0.01%Prev close26,936.0452-wk high27,288.7952-wk low20,690.25Dow Jones · Thu close51,349.98▼ -0.31%Prev close51,511.5952-wk high54,744.3352-wk low45,057.28The Nasdaq 100 edged up 0.03% to 30,478.86 while the Russell 2000 slipped 0.11% to 2,835.57. Closes via Stooq; 52-week ranges per market data.S&P 500 Sectors
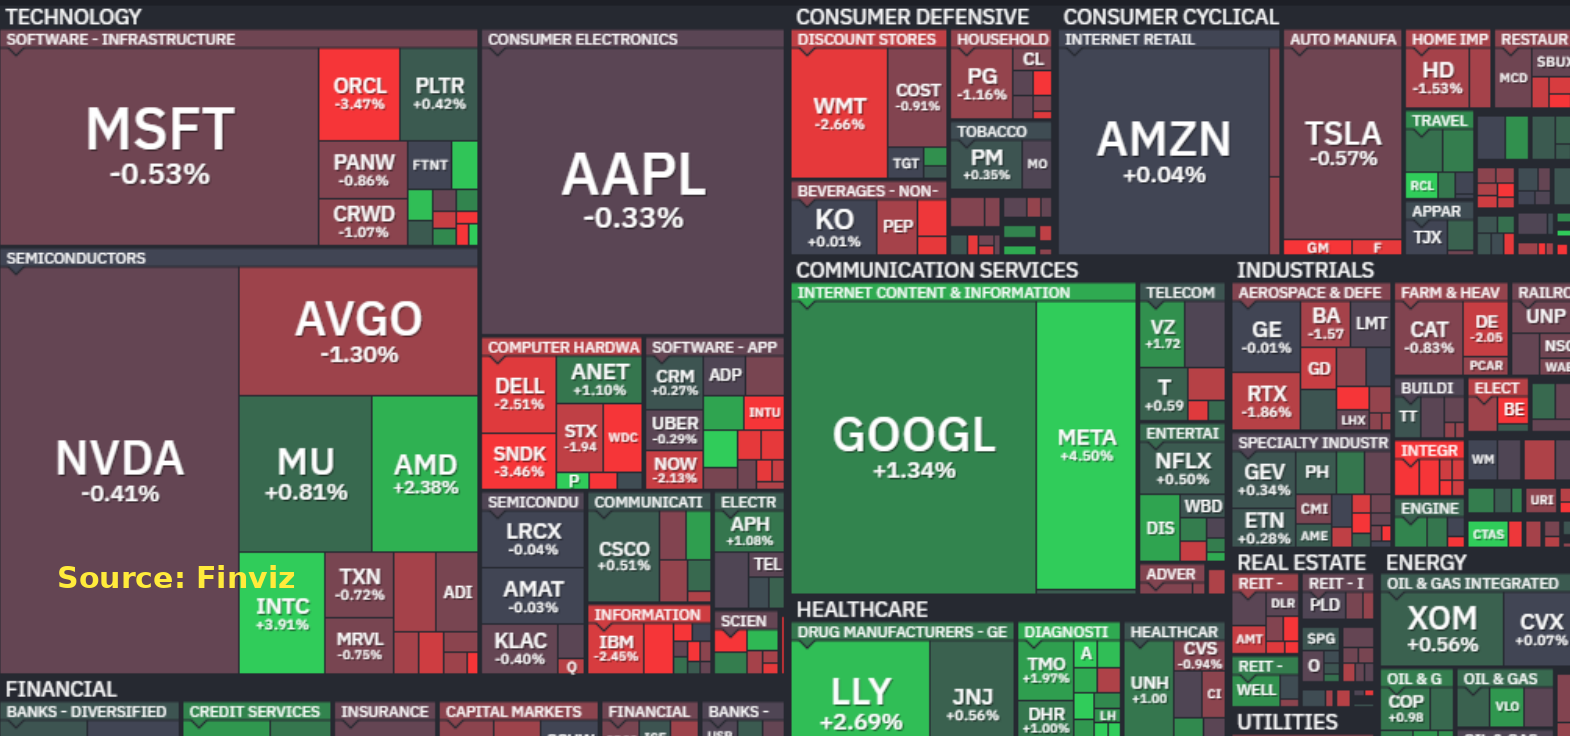
 Communication services (+1.67%) led as META jumped 4.5% and Alphabet added 1.3%; health care (+0.63%) followed on Lilly’s 2.7% gain. Rate-sensitive utilities (-1.00%) and materials (-1.04%) lagged as yields ripped. Source: Finviz.Yields, Dollar & Commodities2-YEAR TREASURY4.931%▲ from 4.897%10-YEAR TREASURY5.208%▲ from 5.110%30-YEAR TREASURY5.48%▲ highest since 2004DOLLAR INDEX (DXY)101.26+0.1%GOLD$4,310▼ on hike repricingWTI CRUDE$94.76+2.2%BRENT~$106eased on Iran-deal hopesNATURAL GAS$3.318+4.6%Economic Data
Indicator Actual Expected Previous Initial jobless claims 197K 200K 196K New home sales (Aug, annualized) 684K 616K 607K EIA natural gas storage 53 Bcf 50.7 Bcf 44 Bcf 7-year Treasury auction 5.085% 5.078% (WI) — Q2 current account balance -$246.0B -$257.4B -$226.8B The labor market refuses to crack — 197K jobless claims keeps the “no landing” narrative alive — while new home sales blowing past 684K shows housing demand surviving 7% mortgage rates. On the wires: hawkish Cleveland Fed President Beth Hammack and neutral voter Anna Paulson both spoke, and a soft 7-year auction (5.085% vs 5.078% when-issued) added to the bond market’s bad day.Market SentimentVIX~15.7Up from 15.18 — creeping higher with the bond rout, but still calm by historical standards.CNN FEAR & GREED INDEX36 — Fear0 Extreme Fear50 Neutral100 Extreme GreedFear is creeping back: the index sits at 36 after reading 30 a week ago, a long way from the 59 (Greed) of a month ago. Bonds are screaming while the VIX whispers — a divergence that usually resolves with one of them moving fast.Top Stories1. U.S., Iran Explore Phased Deal to Reopen HormuzNegotiators in New York are exploring a phased agreement — Iran reopens the Strait of Hormuz while the U.S. lifts its blockade of Iranian ports, with frozen assets addressed after — under Qatari mediation. The framework echoes the June MOU that collapsed within weeks. Tehran’s conditions include an immediate blockade lift, release of frozen assets, and an end to the war “on all fronts”; Iran’s foreign minister has floated reopening the strait within 7 days if conditions are met. Brent, up more than 7% over two days, stalled near $106 on the headlines.Why it matters: sequencing is the whole game — neither side wants to surrender leverage first. Until ships actually move, oil volatility stays bid.2. Bond Rout Deepens: 30-Year Hits 5.48%, Highest Since 2004The global bond selloff rolled on Thursday, with the U.S. 30-year yield spiking to 5.48% — a level not seen since 2004 — and the 10-year closing around 5.21%. The cocktail: Iran-war energy costs, resilient growth, expanding government borrowing, and rising odds of another Fed hike. Treasury Secretary Bessent’s buybacks and FX interventions have so far failed to break the momentum, and 30-year mortgage rates are back at 7%.Why it matters: at 5%+ risk-free, every long-duration asset — growth stocks, housing, crypto — faces a steeper valuation headwind.3. Trump Wraps Xi Summit; Taiwan Takes Center StageTrump and Xi close out the summit Friday with a joint visit to the National Archives. Thursday’s talks produced modest trade progress and AI as a cooperation area — but no breakthrough. Xi pressed Washington to move from “not supporting” to “opposing” Taiwan independence, while a roughly $14 billion Taiwan arms package sits on hold as a bargaining chip. Senate Democrats blasted the outcome, demanding already-approved military support for Taiwan proceed immediately.Why it matters: the two-month truce extension keeps tariff risk hanging over Q4 trade — and Taiwan is now the variable to watch.4. Trump–Xi State Dinner Draws Big Tech and Wall StreetElon Musk, Tim Cook, Mark Zuckerberg, Jensen Huang, and Jeff Bezos were among the headliners at the White House state dinner honoring Xi — a guest list that doubled as the agenda, with AI and trade the expected dinner topics. The red-themed evening, curated by Melania Trump, nodded to the 1972 Nixon–Zhou toast.Why it matters: when the guest list is the agenda, watch what the CEOs say next about China exposure.5. Anthropic Signs $11.6B, 7-Year Compute Deal With AkamaiAnthropic committed $11.6 billion over seven years for Akamai cloud capacity — the largest deal in Akamai’s history — with room to expand by another $9 billion. Akamai will spend about $5.5 billion on servers, chips, and networking to deliver it, and issued Anthropic a warrant for 7.7 million shares (up to ~5% of the company) at $111.33. Akamai shares surged 22% in extended trading. Wall Street flagged the “circular AI deal” structure, with the customer taking equity in the supplier.Why it matters: another multi-billion-dollar vote of confidence in AI compute demand — and a template for how AI labs are locking up capacity.6. Musk: Colossus 2 Nvidia Chips to More Than Double by Year-EndElon Musk said xAI’s Colossus 2 cluster — currently running 110,000 Nvidia GB200s and 440,000 GB300s — could more than double its Nvidia chip count by year-end, with 220,000 more GB300s going live next week, another 220,000 in November, and possibly 220,000 more in December. It is the most detailed expansion timeline Musk has shared for the Memphis-area buildout targeting 1 million GPUs.Why it matters: a concrete, dated capex signal for Nvidia’s data-center demand into year-end.7. Tesla Begins Semi Electric-Truck DeliveriesNearly nine years after its reveal, Tesla started customer deliveries of the Semi this week. The long-haul electric truck promises up to 500 miles of range fully loaded — landing just as U.S. diesel prices hit record highs. Tesla reaffirmed its 50,000-unit annual production target in Nevada, with 2,500 trucks ordered by a global shipper coalition including Microsoft and PepsiCo, plus 500 from Sweden’s Einride.Why it matters: Tesla’s first real push beyond passenger cars, into freight — where fuel economics now favor electric.8. Oracle on the Hook for Project Jupiter Payments Despite Force MajeureThe Financial Times reports Oracle must keep covering bondholder interest in full and a minimum return for Blue Owl investors for up to three years at its New Mexico “Project Jupiter” data center — even though it invoked force majeure over power-delivery delays with developer Blue Owl Capital. The project carries $18 billion in construction loans now quoted below 90 cents on the dollar. Oracle insists the notice implies no schedule change.Why it matters: a window into credit stress building around AI data-center debt as Oracle borrows at unprecedented scale.9. OpenAI to Preview “GPT-6 Cyber” Within DaysFortune reports OpenAI will preview a cybersecurity-specialized model, “GPT-6 Cyber,” within days — its fourth security-focused model this year — likely at Tuesday’s DevDay in San Francisco, alongside a product to help customers deploy it more safely. The launch lands amid growing alarm over autonomous agents, from the June breach of an Australian government health site to warnings about OpenAI’s flagship “Astra” model.Why it matters: cybersecurity is emerging as AI’s fastest-growing commercial vertical — and its most urgent safety debate.10. Costco Beats on Tariff Refunds; Membership Growth DisappointsCostco’s quarterly profit beat estimates, boosted by tariff refunds, with adjusted same-store sales up 6.7% and digital sales up nearly 20%. But paid membership growth came in below expectations, sending shares swinging after hours. Management is using tariff-refund windfalls to cut prices on beef, gasoline, and other staples to defend its price edge.Why it matters: the consumer bellwether is navigating inflation by turning tariff refunds into lower shelf prices — watch whether rivals can follow.11. Apple Pay Antitrust Case Wins Class-Action StatusA federal judge in Oakland granted class-action status to the antitrust suit alleging Apple used its mobile-device dominance to block rival payment apps and charge card issuers fees through Apple Pay. The class covers financial institutions that contracted with Apple to link their cards — with damages potentially measured against the total fees Apple collected.Why it matters: class certification sharply raises Apple’s exposure; a loss could run into the billions in fees disgorged.12. Yen in Focus: Trump Raises Concern; Goldman Flips BullishJapan’s finance minister said Trump raised concerns about yen weakness in his meeting with PM Takaichi, who agreed the undervalued yen is a problem — classic verbal intervention that lifted the yen. Separately, Goldman Sachs strategist Karen Reichgott Fishman reversed her bearish yen call, cutting the 12-month dollar/yen forecast from 165 to 150 on a faster BOJ hiking path.Why it matters: a coordinated turn toward yen strength raises carry-trade unwind risk — the market’s favorite volatility amplifier.13. New York and Polymarket Sue Each Other Over Prediction MarketsNew York’s attorney general and Polymarket filed dueling lawsuits over whether prediction markets are illegal gambling and who regulates them — the state, or the CFTC. New York alleges Polymarket operated without a gambling license and exposed 18-to-20-year-olds to betting; Polymarket counters that the CFTC has exclusive jurisdiction. With appeals courts split, the fight could reach the Supreme Court.Why it matters: the outcome will define the regulatory map for the prediction-market industry that called the 2024 election better than the polls.14. Bitget Hit by $352M Hack, Points to North KoreaCrypto exchange Bitget suffered a roughly $352 million hack — attackers forged transfer data through its backend wallet system to drain hot and warm wallets. Cold wallets were unaffected and private keys were not compromised, the company said. Bitget says its $464 million user-protection fund can cover the full loss; withdrawals were paused and are expected to resume within days.Why it matters: one of the largest crypto hacks in months — and another data point in the Lazarus Group’s relentless campaign against exchanges.15. China’s August EV Registrations Rose 9.3% From JulyBattery-electric vehicle registrations in China hit 684,210 in August, up 9.3% month-on-month (down 3% year-on-year), taking a 44.2% share of all new registrations, per CATARC. BYD led with 111,952, followed by Leapmotor and Tesla at 50,037.Why it matters: a demand pulse for the EV and battery supply chain heading into Q4.Crypto DeskBITCOIN~$84,200holding above $84KETHEREUM~$2,680-0.3% (24h)BTC SPOT ETF FLOWS+$346MSep 24 · sustained demandETH SPOT ETF FLOWS+$104MSep 24 · steady bidBitcoin held near $84,000 on Friday as the crypto market absorbed the bond-market shock — a leverage reset after the run toward $87,000, with nearly $80 million in BTC longs liquidated on the dip below $83,000. Spot ETF demand remains the ballast: $346 million into BTC funds and $104 million into ETH funds on Thursday, with weekly BTC ETF inflows tracking the strongest since October 2025. Friday also brings one of Deribit’s largest quarterly options expiries of the year — $15.9 billion in BTC and $2.1 billion in ETH contracts, with positioning leaning bullish.On the policy front: the administration is reportedly weighing ways to support dollar stablecoins abroad, the CFTC chair says a crypto framework is being built within existing law, and the White House crypto czar says the push for the CLARITY Act continues.Single-Stock News — Source: Earnings Whispers
Source: Earnings Whispers
GFS — GlobalFoundries expands silicon-photonics co-development with SingaporeThe chipmaker is deepening its joint silicon-photonics development work with Singapore, betting on optical interconnects for the AI data-center buildout.NVO — Novo Nordisk signs technology deal worth up to €1.165B with NanexaThe agreement adds another technology pillar as Novo defends its obesity-drug franchise.META — Unveils “Horizon Create” and “Horizon Studio”: build games with AIMeta’s new tools let users create games with AI inside its Horizon metaverse platform — another attempt to make its virtual worlds stick.AAPL — Apple Pay card-fee suit granted class-action statusSee Top Stories #11 — the Oakland ruling opens Apple to potentially billions in fee-based damages.AKAM — $11.6B, 7-year Anthropic compute deal, the largest in company historySee Top Stories #5 — plus a warrant for up to ~5% of Akamai’s stock; shares jumped 22% after hours.ORCL — “Project Jupiter” force-majeure notice, but investor payments remain (reported)See Top Stories #8 — FT reports Oracle must keep bondholders and Blue Owl investors whole for up to three years despite power delays.NVDA — Musk says Colossus 2 chip count to more than double by year-endSee Top Stories #6 — xAI’s most detailed GPU expansion timeline yet, a direct read-through to Nvidia data-center demand.TSLA — Semi electric-truck customer deliveries beginSee Top Stories #7 — 500-mile range, 50K/year Nevada target, with Microsoft/PepsiCo among early fleet orders.COST — Profit beats on tariff refunds; paid membership growth disappointsSee Top Stories #10 — comp sales +6.7% and digital +20%, but the membership miss kept the stock choppy after hours.Source: Earnings Whispers · via SAVE briefing, Sep 25 edition.Single-Stock MoversTop S&P 500 gainers and losers. Source: Trefis S&P 500 Movers (latest article published Sep 21 — data as of Friday, Sep 18 close; no Sep 24 edition available)
Top Gainers Move COIN Coinbase Global +11.7% SNDK SanDisk +11.0% HOOD Robinhood Markets +9.1% COHR Coherent +7.2% LRCX Lam Research +7.0% Top Losers Move NUE Nucor -6.3% QCOM Qualcomm -5.8% ARE Alexandria Real Estate -5.4% GM General Motors -5.1% ACN Accenture -4.7% Friday’s Calendar (ET)Time Event 5:15 AM Fed’s John Williams speaks (Oxford, UK) 8:30 AM Durable Goods Orders, August prelim (cons. -0.3%, prev +1.1%) · Core CapEx (cons. +0.5%) 10:00 AM Michigan Consumer Sentiment, Sep final (cons. 47.5, prev 47.8) · 1-yr inflation expectations 1:00 PM Baker Hughes weekly rig count 2:00 PM Fed’s Beth Hammack speaks Watch: whether durable goods confirms manufacturing resilience under 5%+ long yields, whether Michigan sentiment stabilizes after the rate hike, and whether any Fed speaker pushes back on the market’s growing hike conviction. Into the weekend, U.S.–Iran headlines from New York will set the tone for crude — plus Friday’s massive Deribit crypto options expiry.
Sources: Reuters · EU Today · Mappr · GlobeNewswire · MarketWatch · eOption · Finviz · Trefis S&P 500 Movers · Earnings Whispers · SAVE briefing PDF, Sep 25 edition (supplied by the site owner) · CNN Fear & Greed · Finnhub/CoinGecko crypto pricesAuto-posted by the Bull Lounge news desk.Not financial advice.Log in to vote -
AuthorPosts

Viewing 1 post (of 1 total)
More from Morning Briefingmore +
| Title | Author | Date | Replies |
|---|---|---|---|
| Morning Briefing — Oct 15: CPI Aftershock, Anthropic’s $16.8B Quarter, TSMC Record [0] | Master | 10-15 | 0 |
| Morning Briefing Oct 14: Hot CPI Shocks, ASML Beats, MS Earnings Today [0] | Master | 10-14 | 0 |
| Morning Briefing Oct 13: Chip Rout Deepens, Bank Earnings, CPI Ahead [0] | Master | 10-13 | 0 |
| Morning Briefing Oct 12: Energy Ceasefire, Saudi Strikes, AI Deals [0] | Master | 10-12 | 0 |
| Morning Briefing: October 9, 2026 [0] | Master | 10-09 | 0 |
| Morning Briefing: October 8, 2026 [0] | Master | 10-08 | 0 |
| Morning Briefing: October 7, 2026 [0] | Master | 10-07 | 0 |
| Morning Briefing: October 6, 2026 [0] | Master | 10-06 | 0 |
| Morning Briefing: October 5, 2026 [0] | Master | 10-05 | 0 |
| Morning Briefing: October 2, 2026 [0] | Master | 10-02 | 0 |
| Morning Briefing: October 1, 2026 [0] | Master | 10-01 | 0 |
| Morning Briefing: September 30, 2026 [0] | Master | 09-30 | 0 |
Get the Morning Briefing in your inbox
One short email with what matters for the trading day. No spam, ever.